Financing a luxury home in Puerto Rico begins with finding a lender willing to evaluate the specific property, loan amount, occupancy plan, and borrower profile. A large purchase price does not automatically mean one loan product or one down-payment requirement. The practical starting point is to compare current mortgage options and ask each lender how it handles Puerto Rico collateral, appraisals, insurance, and closing.
Key Takeaways
- Start with lenders that currently offer Puerto Rico mortgage services.
- Ask about the property type, occupancy, loan size, and down payment before assuming eligibility.
- Compare written Loan Estimates using the same loan amount and terms.
- Budget for appraisal, insurance, closing costs, and cash reserves in addition to the down payment.
- Confirm that a mainland lender finances homes in Puerto Rico before applying.
What Is Luxury Real Estate Financing?

Luxury real estate financing is borrowing to purchase or improve a higher-priced property. The right structure depends on the property and the lender’s underwriting: a completed residence, a beachfront lot, a pre-construction home, and a mixed-use building may call for different products. For more on purchase conditions, see the appraisal contingency guide and the mortgage basics guide.
Financing option | Question to ask |
|---|---|
Purchase mortgage | Does the lender finance this property type, location, occupancy, and requested loan amount? |
Construction financing | Can the lender finance the land, construction draws, or both, and what plans and permits are required? |
Bridge financing | Is short-term financing available while an existing property is being sold, and what is the repayment plan? |
Home equity borrowing | Can existing home equity be used, and what are the costs and risks of securing another property? |
Five Lender and Mortgage Resources for Puerto Rico Luxury Buyers
These resources offer three current Puerto Rico mortgage entry points and two independent tools for comparing offers. Their inclusion is a starting point for research, not an endorsement or a claim that any lender will approve a particular luxury purchase.
1. Banco Popular de Puerto Rico

Banco Popular’s mortgage prequalification page explains how to begin its mortgage process. Ask its mortgage team whether it can finance your property type and proposed loan amount, and what documentation it needs for your income and assets.
Image Source: Wikipedia
2. FirstBank Puerto Rico

FirstBank’s Puerto Rico mortgage page describes its current mortgage offerings. Confirm the applicable product, property eligibility, down payment, reserves, and closing timeline directly with the lender.
Image Source: FirstBank investor site
3. Oriental Bank

Oriental Bank maintains a Puerto Rico mortgages page. Ask about financing for the specific residence or project under consideration, including appraisal requirements and the treatment of insurance and association dues.
Image Source: Mayagüez Mall
4. CFPB guide to requesting Loan Estimates
The Consumer Financial Protection Bureau explains how to request multiple Loan Estimates. Ask several eligible lenders for written estimates based on comparable loan details; a marketing rate alone does not show the complete cost.
5. CFPB Loan Estimate explainer
The CFPB’s Loan Estimate explainer identifies the payment, closing costs, cash to close, and other terms to review. Compare offers on the same loan amount, property, occupancy, and rate-lock assumptions, and ask lenders to explain differences.
Lending Tips for Luxury Home Buyers
Luxury transactions can involve unusual collateral and larger cash commitments. These steps help turn a lender conversation into a useful, comparable financing decision.
Prepare financial records
Ask each lender for its document checklist. Income records, tax returns, bank and investment statements, debt information, and explanations of large deposits may be requested depending on the application.
Check credit and available cash
Review credit reports for errors and calculate the funds available for the down payment, closing costs, insurance, and any lender-required reserves. There is no universal 20% to 30% down-payment rule for every luxury home; the requirement depends on the lender, loan, borrower, and property.
Compare total borrowing costs
Compare the interest rate, annual percentage rate, payment, lender fees, estimated taxes and insurance, and cash to close on each written estimate. The Puerto Rico interest rate guide explains why rate alone is an incomplete measure of affordability.
Plan for appraisal and property review
Discuss appraisal, title, insurance, condominium or association documents, and inspections early. A lender appraisal serves underwriting; buyers should also decide which independent property inspections and professional reviews they need.
Can a Mainland U.S. Lender Finance a Puerto Rico Home?

Possibly, but eligibility must be confirmed with the lender for the Puerto Rico address and the specific property. Ask whether the lender originates mortgages secured by Puerto Rico real estate, which products are available for your intended occupancy, and who handles local appraisal, title, and closing requirements. A U.S. mainland address or an existing relationship with a bank does not establish that its mortgage products cover Puerto Rico.
Buyers can also ask Puerto Rico mortgage lenders to review the same property and compare written estimates. Government-backed programs may be relevant for eligible borrowers and eligible homes, but their rules and loan limits should be checked for the exact purchase; they should not be assumed to finance every luxury property.
Puerto Rico Luxury Properties for Sale
Financing questions become more precise when a lender can review an actual listing. These luxury properties for sale include land, a beachfront condominium, a multi-residence property, and a mixed-use building, each of which may call for different underwriting. Listing details and availability can change, so verify them before applying.

2021 Calle Italia, San Juan
This Ocean Park listing is a beachfront building lot with permitted plans. Ask prospective lenders about land and construction financing before assuming a standard completed-home mortgage applies.
3307 Avenida Isla Verde, PH, Carolina
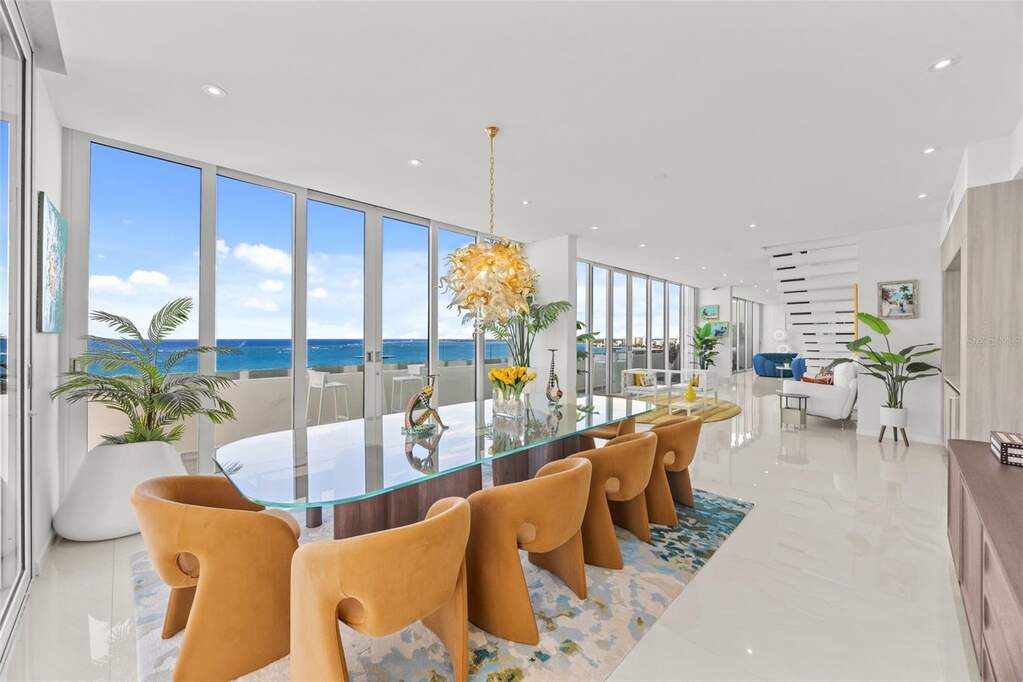
This Isla Verde penthouse is a five-bedroom condominium with ocean views. Ask lenders how condominium documentation, insurance, and any association obligations enter their review.

1858 McLeary, San Juan
This San Juan residential listing contains three living units and a pool. Discuss the property’s actual use and configuration with a lender before selecting a loan product.
103 Cristo Street, San Juan
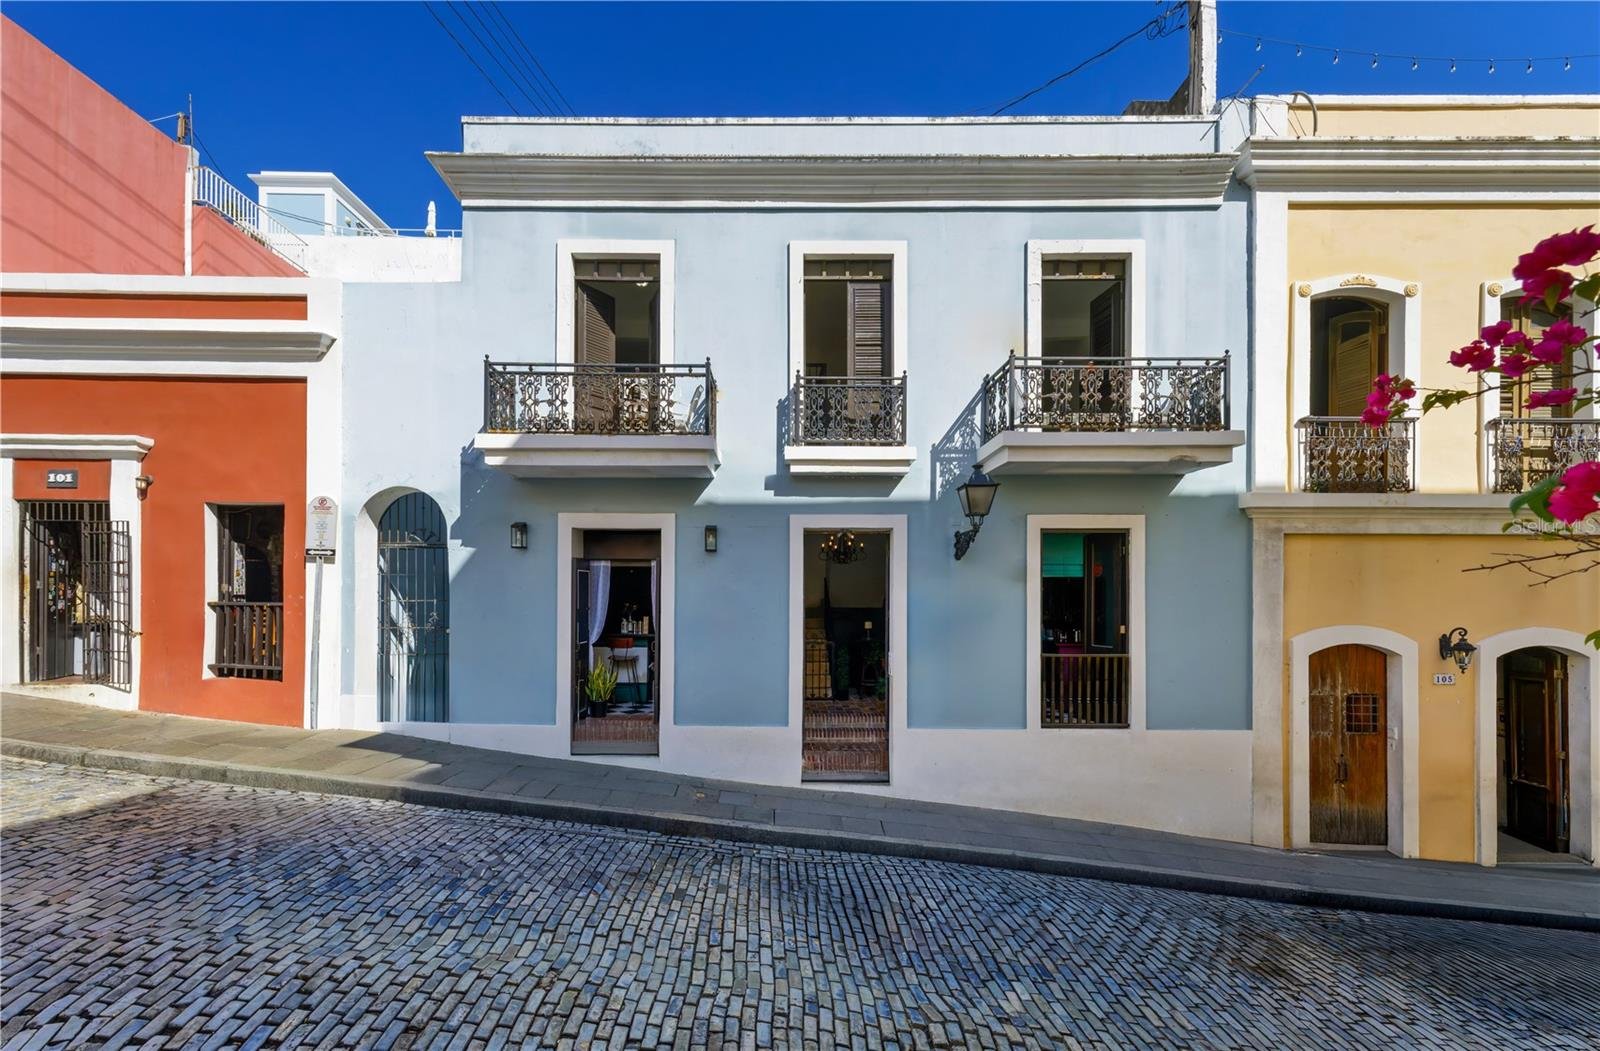
This Old San Juan listing is classified as a multi-family property rather than a single-family home. Ask a lender whether its financing fits the building’s actual use and income profile.
Conclusion
Luxury home financing in Puerto Rico depends on the property as much as on the buyer’s financial profile. Banco Popular, FirstBank, and Oriental offer current Puerto Rico mortgage starting points, while CFPB tools help buyers compare written offers. Confirm property eligibility, total costs, and closing requirements with each lender before selecting a loan.
If you want to rent, buy, or sell luxury property in Puerto Rico, Christie's International Real Estate Puerto Rico can help you evaluate the market and connect the property search with your financing questions. Explore Puerto Rico luxury properties and contact the team for guidance on your next step.
FAQs
Can a mainland U.S. lender finance a Puerto Rico property?
It depends on whether the lender finances the Puerto Rico address, property type, occupancy, and loan amount. Confirm these points with the lender before relying on a prequalification or comparing its offer with local lenders.
How much down payment does a Puerto Rico luxury mortgage require?
There is no single percentage that applies to every luxury purchase. Ask lenders for the down payment and reserve requirements for the specific borrower, property, and loan product, then compare the resulting Loan Estimates.
Can a lender finance land or a mixed-use building?
Some lenders offer products beyond a completed-home purchase mortgage, but eligibility and terms vary. Identify the property’s actual use and ask lenders about land, construction, or multi-family financing as appropriate.
Related Articles
These guides provide more detail on mortgage basics, interest costs, and appraisal conditions in Puerto Rico.