Puerto Rico mortgage interest rates affect the cost of financing a home, not the rate at which that home gains value. A lower borrowing rate can improve monthly affordability, but it cannot guarantee appreciation, rental income, or a profitable resale.
For a luxury purchase, compare the loan structure and total ownership budget alongside the property itself. The useful question is not simply whether rates will fall, but whether the purchase remains affordable under the financing terms available to that borrower.
Key Takeaways
- Mortgage interest, APR, and property appreciation measure different things.
- Federal Reserve decisions do not directly set a buyer’s mortgage rate.
- Compare loan terms, fees, cash to close, and total monthly costs.
- USDA direct loans are not a general luxury-investment financing option.
- Test affordability without assuming refinancing or rising property values.
How Mortgage Interest Rates Work in Puerto Rico

Image Source: Unsplash
A mortgage rate is the annual percentage charged on the outstanding loan balance. Understanding mortgage financing starts with separating that borrowing cost from changes in the home’s market value.
Interest Rate, APR, and Appreciation
The CFPB’s APR explanation distinguishes the loan’s interest rate from its annual percentage rate, which incorporates certain fees and charges. Appreciation, by contrast, is a change in property value and is not a return promised by the mortgage.
Measure | What it means | How to use it |
|---|---|---|
Interest rate | The borrowing rate applied to the unpaid principal. | Calculate principal-and-interest payments using the loan amount and term. |
APR | A broader borrowing-cost measure that includes certain loan charges. | Compare similar loan products while reviewing fees and timing separately. |
Appreciation | An increase in a property’s market value. | Evaluate comparable sales without assuming future growth. |
APR is not the property’s investment yield or the total cost of homeownership. Comparisons between fixed and adjustable loans also require care because an ARM’s disclosed APR does not show its maximum possible interest rate.
Why Mortgage Rates Rise or Fall
The Federal Reserve influences financial conditions, but it does not directly set individual mortgage rates. The Atlanta Fed’s mortgage-rate analysis explains the importance of longer-term yields, inflation expectations, credit risk, and other factors; mortgage rates can move differently from the federal funds rate.
For the same loan balance and repayment term, a higher rate increases the principal-and-interest payment. That can constrain a financed buyer’s budget, but it does not mechanically force every home’s price to fall: supply, comparable sales, property condition, and the mix of cash and financed buyers also matter.
Compare Current Offers, Not an Old Rate Table
There is no single advertised rate that applies to every Puerto Rico buyer. Request dated, property-specific offers using the same loan amount, occupancy, term, and points assumptions, and confirm that the lender finances the intended property and use.
The CFPB’s loan comparison guidance recommends comparing interest rates, monthly payments, lender charges, credits, and cash to close. Rates can change daily, so offers prepared on different dates may not be directly comparable.
- Confirm whether the quoted rate is locked and when the lock expires.
- Separate the down payment from closing costs, prepaid items, and reserves.
- Ask whether a lower rate requires upfront points.
- Compare the same loan structure rather than only the lowest headline rate.
Fixed-Rate and Adjustable-Rate Mortgages
With a fully amortizing fixed-rate mortgage, the contractual interest rate and scheduled principal-and-interest payment remain unchanged over the loan term. Taxes, insurance, association charges, and other ownership costs can still change.
An adjustable-rate mortgage can reset according to its contractual terms after an initial period. Review the index, margin, adjustment dates, and rate caps using the CFPB’s fixed-versus-adjustable mortgage guidance, and test whether the higher permitted payment would remain manageable.
Where USDA Direct Loans Fit
The Puerto Rico USDA direct-loan program serves eligible low- and very-low-income applicants in eligible rural areas. It requires primary-residence occupancy and excludes properties designed for income-producing activities, so it should not be presented as a general financing route for luxury rental investments or vacation homes.
USDA’s page lists a 5.750% rate effective October 1, 2026, with payment assistance potentially reducing the effective rate for qualifying applicants. This is program-specific information, not a conventional mortgage quote or a rate available to every buyer; eligibility and current terms must be confirmed directly with USDA.
What Else Affects Financing and Property Value?

Borrower qualifications help determine a loan offer, while a property’s location and condition affect its value and ownership costs. Keeping those questions separate makes a financing comparison more useful.
Borrower and Loan Characteristics
The CFPB identifies credit history, loan amount, down payment, term, rate structure, loan type, and property location among the factors affecting mortgage rates. Ask how the lender treats a primary home, second home, or investment purchase rather than assuming identical pricing or documentation.
For a larger luxury loan, request the lender’s applicable loan-size limits, reserve requirements, appraisal conditions, and income-documentation standards. A preapproval is not a substitute for final underwriting or confirmation that the particular property meets the loan program’s requirements.
Location, Supply, and Comparable Sales
Evaluate recent comparable sales, condition, amenities, days on market, and competing inventory at the neighborhood level. Coastal addresses do not automatically appreciate faster than inland homes, and a desirable location does not by itself secure a lower mortgage rate.
Buyers considering beachfront property should include maintenance and exposure in their comparison, not just the view. A purchase price that appears attractive may be less compelling after insurance, repairs, or association assessments are included.
Property Taxes, Legal Review, and Closing Costs
Obtain the property’s current CRIM assessment, account information, and applicable exemptions rather than applying one percentage to every home. The Puerto Rico Municipal Code distinguishes municipal property-tax rates and a separate special contribution; the previously stated 1.03% is not a universal total property-tax rate.
Review Puerto Rico property taxes with qualified local advisers and confirm the actual account before closing. Legal review should also cover title, existing liens, permitted use, and contractual obligations; buying a property does not automatically create a tax exemption.
Infrastructure, Insurance, and Property Condition

Evaluate roof condition, water intrusion, drainage, backup utilities, and maintenance records alongside the financing offer. The cost of addressing coastal infrastructure challenges can materially affect a home’s annual budget.
Obtain property-specific insurance quotes and confirm coverage, deductibles, exclusions, and any separate flood-insurance needs before relying on an estimated monthly payment. Neither geographic diversification nor a backup system guarantees protection against storm damage or interruption.
Economic and Population Context
Use dated, municipality-specific information when assessing demand, rather than assuming islandwide population change predicts a particular neighborhood’s prices. The Census Bureau’s municipal population estimates provide a starting point, but population trends alone do not establish investment returns.
Example: How Interest Rates Change Mortgage Payments

A transparent payment example is more useful than an invented historical appreciation path. The following comparison holds the loan balance and repayment term constant so the rate’s effect can be seen clearly.
Illustrative $1 Million Loan
Assume a $1,250,000 purchase with a $250,000 down payment, leaving a $1,000,000 loan amortized over 30 years. These hypothetical fixed rates are calculation assumptions, not current lender offers or an assurance that 80% financing is available.
Illustrative rate | Monthly principal and interest |
|---|---|
6% | $5,995.51 |
7% | $6,653.02 |
8% | $7,337.65 |
The difference between 6% and 8% is approximately $1,342.14 per month before property taxes, insurance, association dues, mortgage insurance if applicable, and upkeep. Closing costs are additional; they are not included in the illustrated down payment.
Test the Full Ownership Budget
Use the Loan Estimate explainer to distinguish principal and interest from estimated total payments and cash to close. Add any costs not collected through the lender, including association charges and maintenance reserves.
For an investment property, compare conservative income assumptions with operating expenses and debt payments, including periods without rent. Do not make affordability depend on refinancing at a lower rate or selling at a higher price, because neither outcome is assured.
Puerto Rico Luxury Properties to Compare
Financing analysis should support a property search rather than replace due diligence. These four existing references to luxury properties for sale were verified as active on October 15, 2026, but availability and financing eligibility can change.
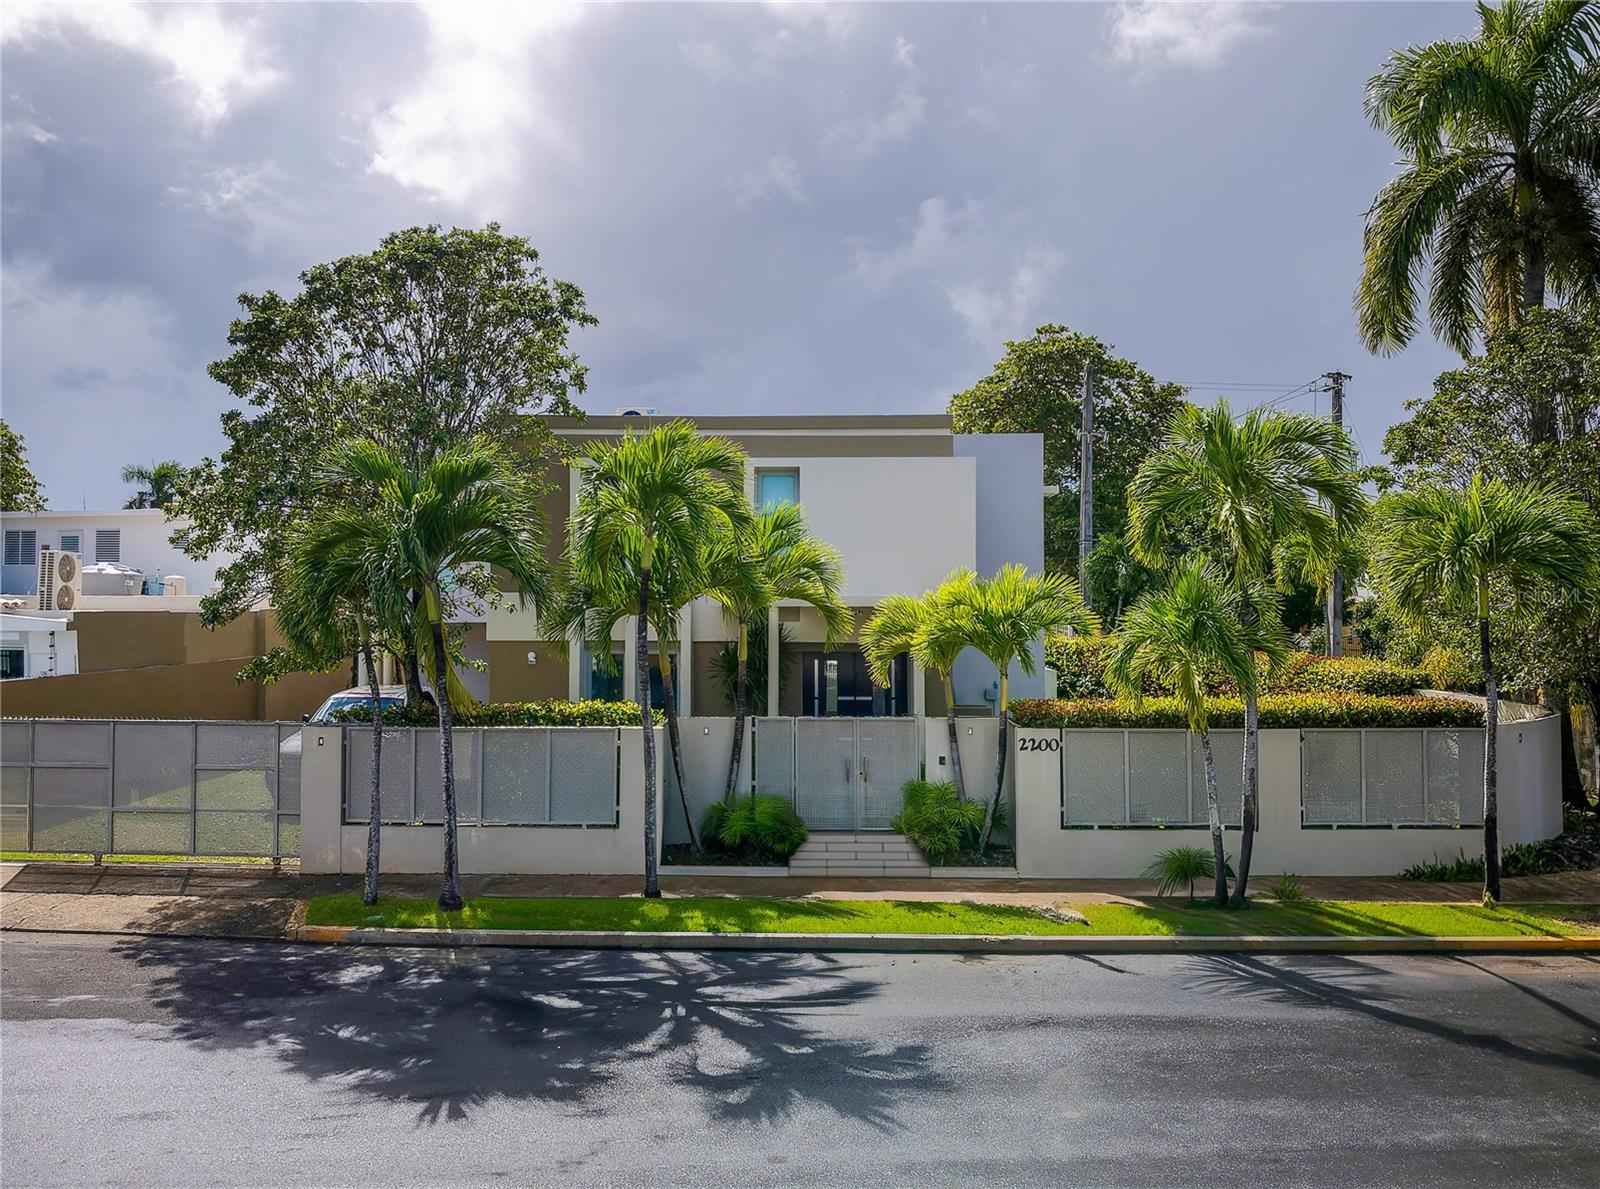
2200 Cacique Street, San Juan
This Santa Teresita residence has five en-suite bedrooms, a pool, and a covered terrace. Its generator and cistern are useful features to inspect when preparing a maintenance and ownership budget.
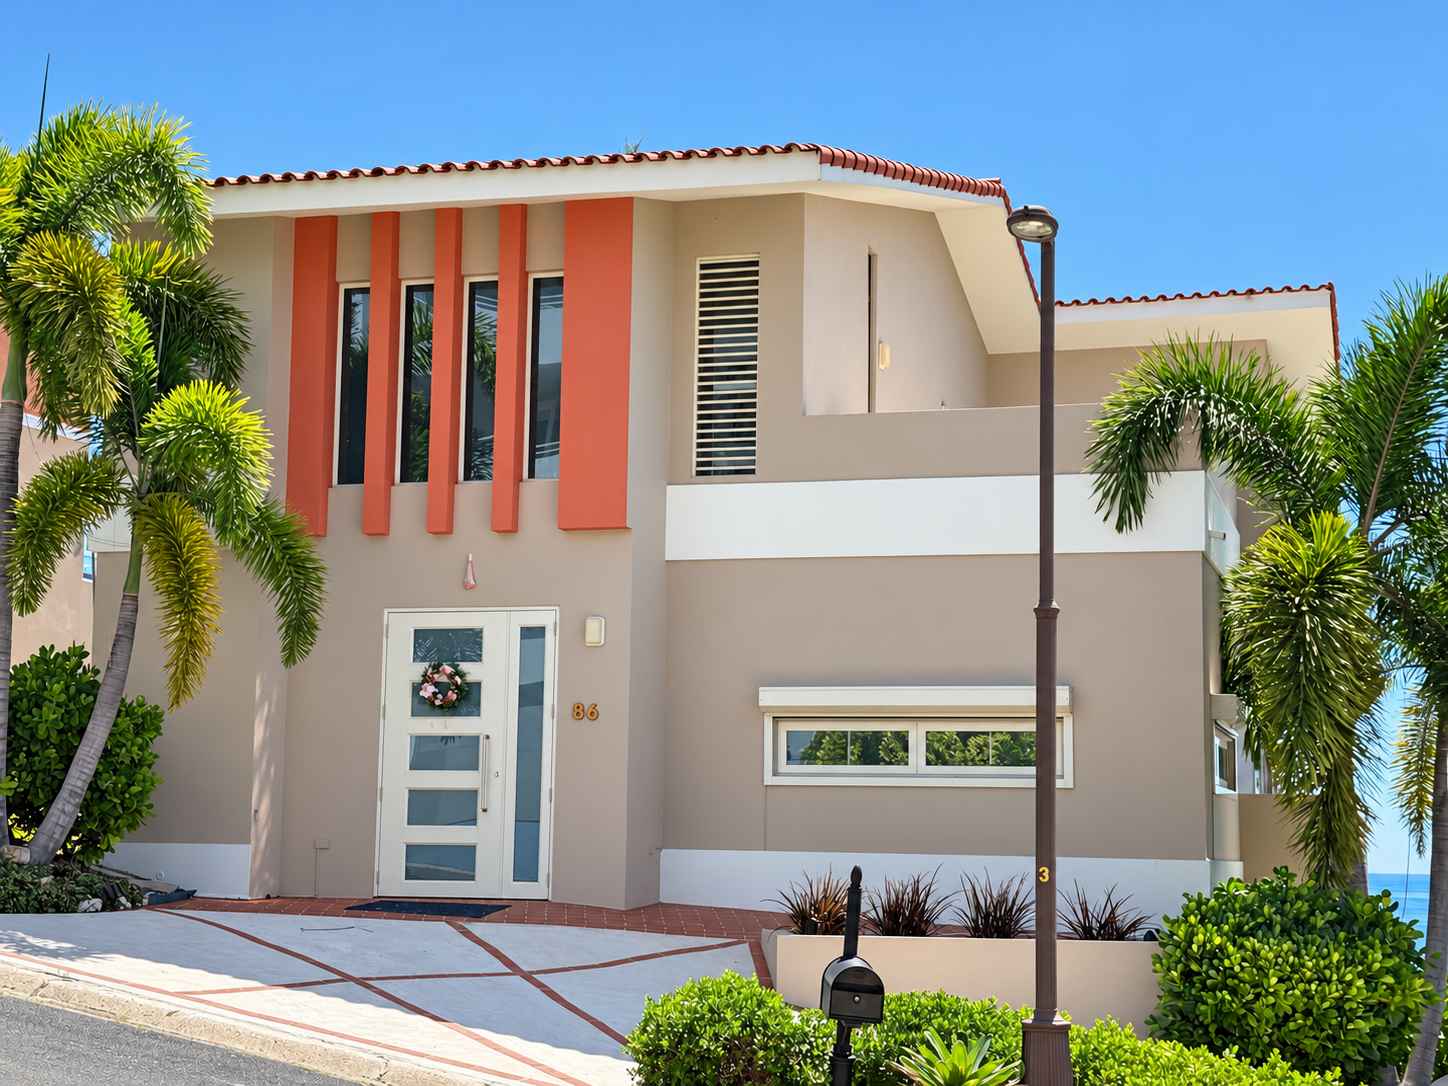
SHELL CASTLE CLUB #86, HUMACAO, PR
This three-level oceanfront residence in Palmas del Mar offers sweeping Caribbean Sea views, an adjoining lot, resort amenities and short-term rental potential.
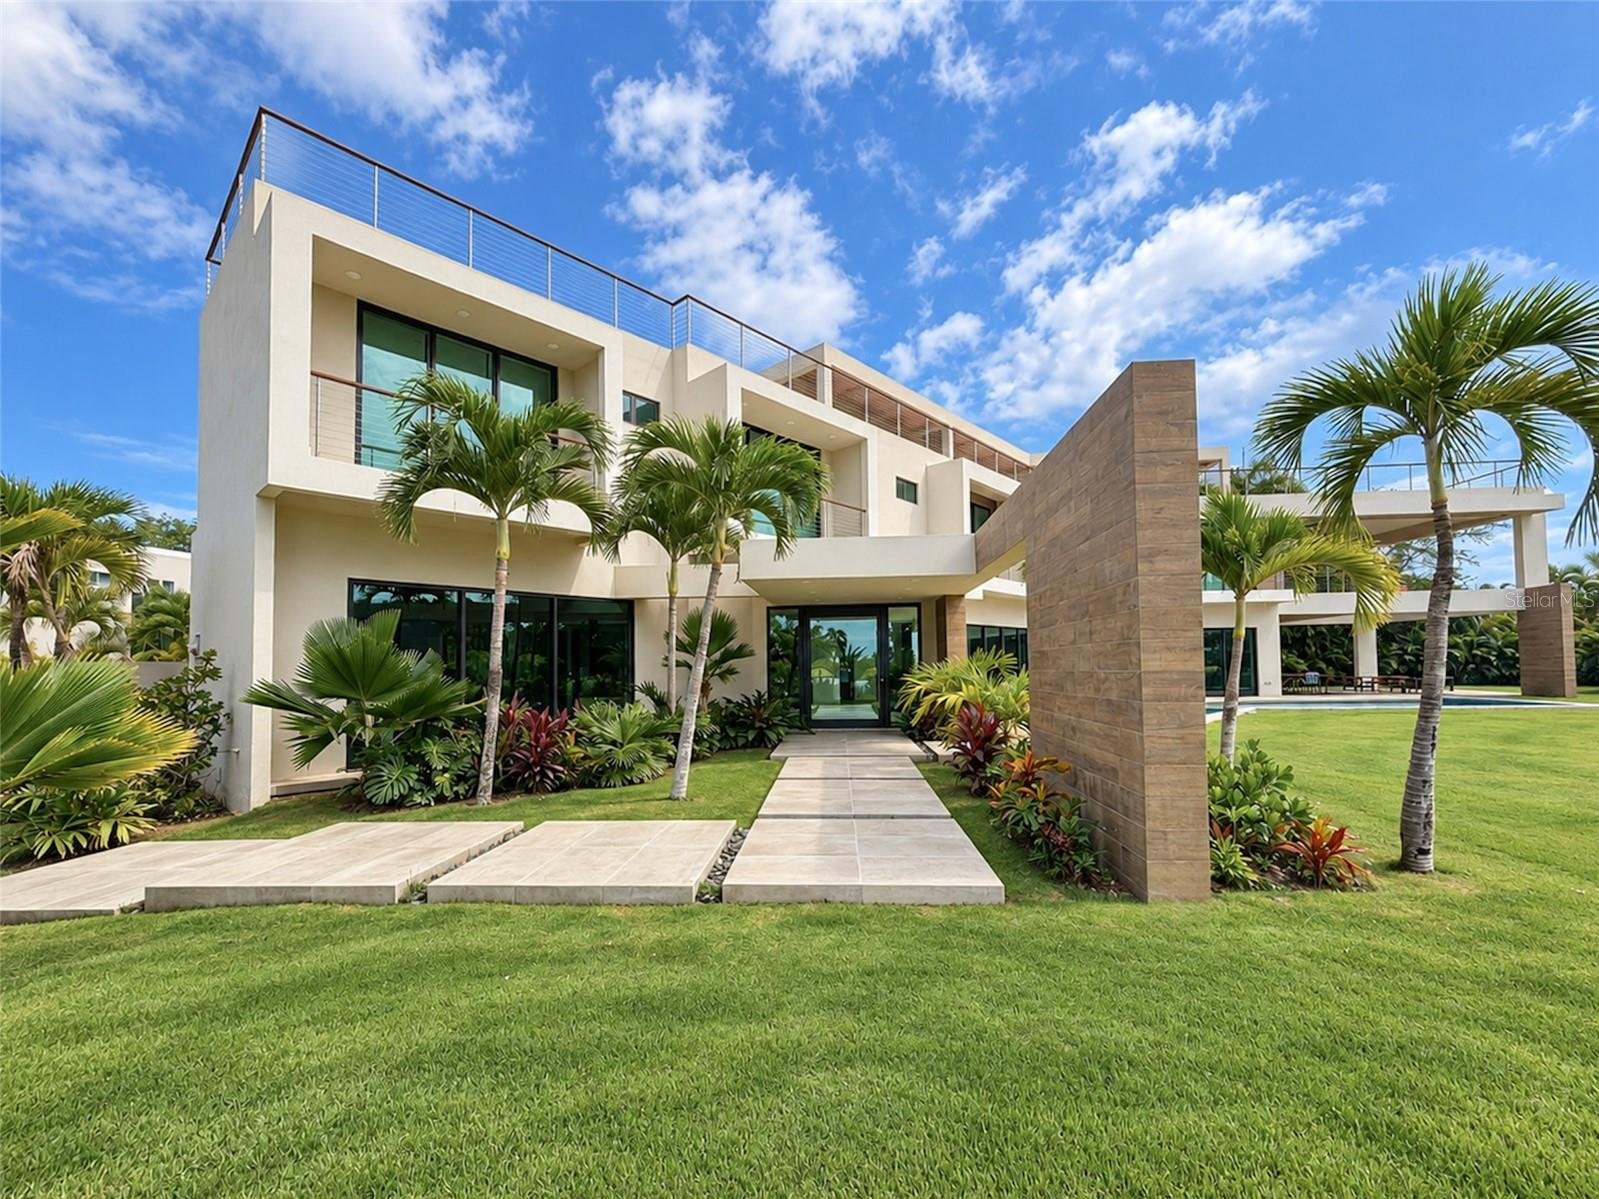
24 LAUREN LN DORADO COUNTRY ESTATES, DORADO
This six-bedroom, nine-bathroom Dorado Country Estates residence showcases Puerto Rico luxury real estate with approximately 10,000 square feet of interior space, a private elevator, custom pool, and rooftop terrace overlooking four TPC Dorado Beach West fairways and mountain sunsets.
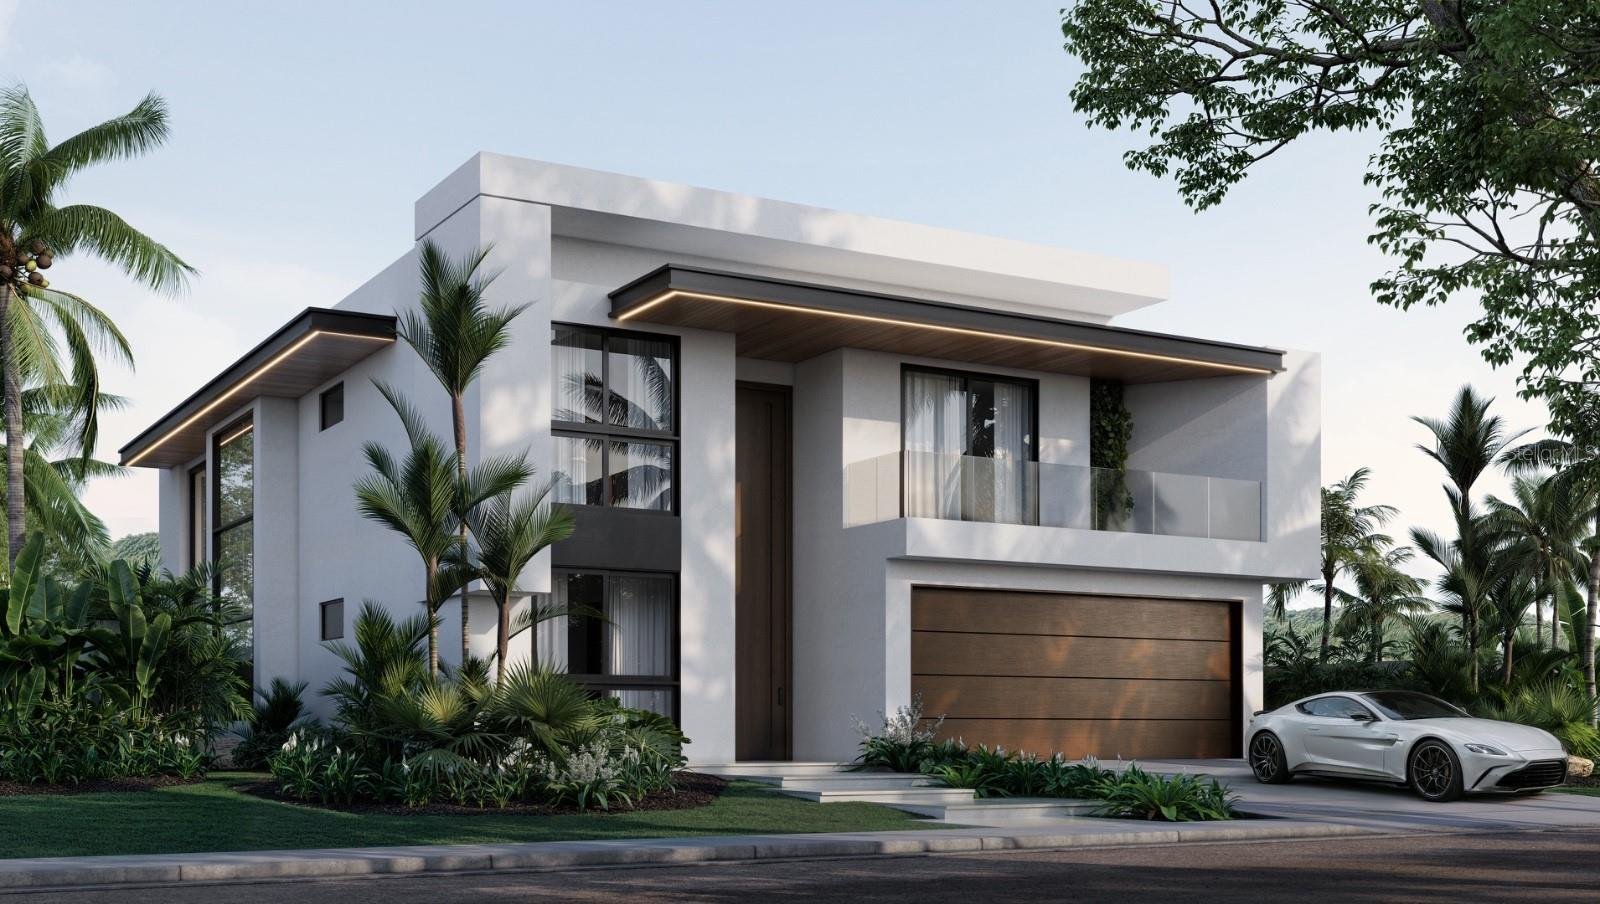
47 Sereno, Guaynabo
This Sereno listing describes a four-bedroom, four-and-a-half-bathroom home with an open living area that connects to a terrace and pool. Confirm construction status, specifications, community charges, and lender requirements before finalizing the purchase budget.
Conclusion
Mortgage interest rates affect borrowing costs, while a property’s future value depends on different market and property-specific factors. Comparing loan terms, cash requirements, and ongoing expenses gives buyers a clearer basis for evaluating Puerto Rico luxury real estate. A purchase should remain manageable without relying on guaranteed appreciation, rental income, or future refinancing.
If you want to rent, buy, or sell luxury property in Puerto Rico, Christie's International Real Estate Puerto Rico is here to guide you. Explore Puerto Rico luxury properties and connect with our team to discuss homes that fit your goals and budget.
FAQs
These answers clarify common financing questions and do not replace a lender’s property-specific quote or professional advice. Confirm the terms that apply to the intended purchase before committing.
What are current mortgage rates in Puerto Rico?
Rates vary by lender, borrower, loan product, occupancy, points, and quote date. Request comparable written offers rather than treating a program rate, national average, or website payment calculator as a personal loan offer.
Does a Federal Reserve rate cut lower my mortgage payment?
Not automatically: a fixed-rate loan’s contractual rate does not change because the Fed changes its policy rate. An adjustable loan follows its own reset terms, and refinancing requires a new loan approval and a review of costs.
Is Puerto Rico a good place to buy an investment property?
That depends on the purchase price, permitted use, financing, operating expenses, demand, and the buyer’s circumstances. Evaluate the specific property under conservative assumptions rather than relying on broad claims about tourism or coastal appreciation.
How should you include property taxes in the budget?
Use verified CRIM records and applicable local rates and exemptions to estimate the property’s obligation. Do not assume that 1.03% is the total tax rate or that a listing calculator provides a confirmed assessment.
Related Articles:
These guides provide additional context for evaluating property costs and purchase options. Verify time-sensitive claims against current official sources before acting.