Financing a home in Puerto Rico starts with the same basic questions lenders ask elsewhere in the United States: how the property will be used, how income and assets will be documented, how much equity the buyer will contribute, and whether the property qualifies for the selected loan program. Luxury purchases add another layer because larger loan amounts, limited comparable sales, condominium or resort rules, insurance, and complex income sources can affect underwriting.
This 2026 Puerto Rico mortgage guide explains the main loan structures, the application and closing process, and the questions buyers should resolve before relying on financing. Rates, programs, loan limits, down payments, and approval standards vary by lender and borrower, so written terms from a lender and advice from qualified financial and legal professionals should guide any transaction.
Key Takeaways
- A Puerto Rico mortgage is secured by the property, but the available terms depend on the borrower, occupancy, loan amount, property type, appraisal, insurance, and lender.
- The 2026 conforming loan limit for a one-unit property in Puerto Rico is $832,750; financing above the applicable limit is generally treated as jumbo lending.
- Luxury buyers may be asked for substantial documentation, reserves, and a larger equity contribution, especially when income is self-employed, investment-based, or earned outside Puerto Rico.
- A preapproval is not a final commitment. The property, title, appraisal, insurance, condominium documents, and closing conditions must still satisfy the lender.
- Buyers should compare the Loan Estimate and Closing Disclosure rather than judging a mortgage by the advertised interest rate alone.
What Is a Mortgage in Puerto Rico Real Estate?
A mortgage is a loan secured by real property. The borrower signs a promissory note agreeing to repay the debt and grants the lender a mortgage over the property; if the borrower does not meet the loan obligations, the lender may pursue remedies allowed by the loan documents and Puerto Rico law.
Monthly housing costs can include principal, interest, property taxes, homeowners insurance, flood or wind coverage, mortgage insurance, and association charges, although not every item is necessarily collected through escrow. The CFPB mortgage overview provides a useful starting point, but the lender's written disclosures determine the terms of a specific loan.
Mortgage Fundamentals for Puerto Rico Buyers
The right structure depends on the buyer's timeline, risk tolerance, income profile, property use, and plans for the asset. A lender licensed and willing to finance the specific Puerto Rico property should confirm which programs are actually available.
Fixed-Rate and Adjustable-Rate Mortgages
A fixed-rate mortgage keeps the note rate unchanged for the loan term, which makes principal-and-interest payments more predictable. An adjustable-rate mortgage usually has an initial fixed period followed by scheduled adjustments tied to an index and margin; buyers should review the first adjustment date, adjustment caps, maximum rate, and payment scenarios before choosing it.
Conforming, Jumbo, and Portfolio Loans
Conforming loans meet the size and other requirements for purchase by Fannie Mae or Freddie Mac. Jumbo loans exceed the applicable conforming limit, while portfolio loans are retained by the lender and may use institution-specific underwriting standards that can accommodate complex income or assets.
For 2026, the FHFA conforming loan limit is $832,750 for a one-unit property throughout Puerto Rico. A loan above that amount is not automatically unavailable, but buyers should expect the lender to set its own standards for reserves, down payment, appraisal, and documentation.
Government-Backed and Specialized Programs
FHA, VA, USDA, construction, renovation, bridge, interest-only, and other specialized loans may be available when the borrower, property, occupancy, and proposed use meet the program rules. Government backing does not remove underwriting, appraisal, insurance, title, or property-condition requirements, and not every lender offers every program in Puerto Rico.
Puerto Rico Mortgage Application and Closing Process
The financing process moves from early qualification to property-specific underwriting and closing. Starting with a Puerto Rico-capable lender before making an offer can expose documentation or property-eligibility issues while there is still time to address them.
- Prequalification or preapproval: The lender reviews preliminary income, assets, debts, credit, occupancy, and the requested loan amount. A stronger preapproval may include document review, but it is still conditional.
- Property and loan application: After a contract is signed, the buyer submits the complete application and receives the applicable written disclosures.
- Appraisal and property review: The lender evaluates value, marketability, condition, insurance, title, and, when relevant, condominium or association documentation.
- Underwriting: The lender confirms the borrower's financial capacity, source of funds, reserves, and satisfaction of outstanding conditions.
- Closing preparation: The lender, notario, brokers, insurers, and other professionals reconcile final documents, funds, and recording requirements.
For mortgages covered by the federal disclosure rules, the Loan Estimate is generally issued within three business days after the lender receives an application, and the Closing Disclosure must generally be received at least three business days before closing. The CFPB recommends comparing the final figures with the latest Loan Estimate and resolving discrepancies before signing.
What Happens If a Borrower Defaults?
Default is governed by the loan documents, servicing rules, and applicable law; there is no safe universal statement that a fixed number of missed payments always triggers foreclosure. A delinquent borrower may receive notices, loss-mitigation information, and an opportunity to discuss repayment, modification, forbearance, or other options, depending on the loan and circumstances.
Foreclosure in Puerto Rico is a judicial process. Anyone facing difficulty should contact the loan servicer promptly and obtain independent legal or housing-counseling guidance rather than waiting for a court filing or assuming that a verbal arrangement changes the written obligations.
Compare the Full Cost, Not Only the Interest Rate
The interest rate is only one part of mortgage cost. Buyers should compare the annual percentage rate, points, origination charges, lender credits, third-party services, prepaid interest, insurance, escrow funding, reserves, and total cash required to close.
Item to Compare | Why It Matters |
|---|---|
Interest rate and APR | The rate affects interest, while APR incorporates certain loan costs and can help compare offers with similar assumptions. |
Points and lender credits | Paying points may reduce the rate; accepting a lender credit may reduce upfront costs in exchange for a higher rate. |
Cash to close | This combines the equity contribution with remaining costs, prepaids, adjustments, deposits, and credits. |
Rate-lock terms | The expiration date and extension cost matter when appraisal, title, condominium, or construction issues delay closing. |
Prepayment or balloon provisions | These features can materially change the cost or refinancing risk and should be identified before signing. |
The CFPB Closing Disclosure guide shows where to find the loan amount, rate, estimated monthly payment, closing costs, and cash to close. Buyers should also build a property-specific budget using current insurance, association, tax, inspection, title, and notarial figures.
Mortgage Insurance and Equity Requirements
There is no universal down-payment percentage for Puerto Rico luxury real estate. The required equity depends on the lender, loan type, purchase price, occupancy, property, borrower profile, and whether the loan is conforming, jumbo, government-backed, or held in portfolio.
Private mortgage insurance may apply to some conventional loans with higher loan-to-value ratios. For many covered principal-residence loans, the CFPB explains PMI cancellation rights at specified balance thresholds, but FHA, VA, lender-paid, investment-property, and other mortgage-insurance structures follow different rules.
How Luxury Lenders Evaluate the Borrower and Property
High-value financing often requires a deeper review of both the borrower and the collateral. Buyers with business income, trusts, investments, foreign income, multiple properties, or entity ownership should ask early which documents and ownership structures the lender accepts.
- Income and assets: Tax returns, financial statements, bank and brokerage records, business documents, trust distributions, and explanations of large transfers may be required.
- Liquidity and reserves: The lender may require funds beyond the down payment and closing costs to remain available after closing.
- Appraisal: Unique homes can be difficult to value when there are few recent comparable sales, so appraisal timing and review should be built into the contract.
- Property eligibility: Condominium budgets, insurance, litigation, deferred maintenance, permits, intended rental use, and association rules can affect approval.
- Insurance and resilience: Wind, flood, hazard, backup-power, and water-system details can influence coverage availability and lender conditions.
The most useful questions are property-specific: whether the lender finances the municipality and ownership structure, whether a rate lock can survive the expected closing timeline, and which conditions must be cleared before the financing contingency expires. A local overview of Puerto Rico lender resources can help buyers organize those conversations.
Economic Conditions and Mortgage Decisions
Mortgage pricing can change with bond markets, inflation expectations, lender capacity, credit risk, loan size, and the borrower's profile. Rather than trying to predict a single perfect rate, buyers can compare offers using the same loan amount, property, term, occupancy, lock period, and assumptions.
A financed offer should also allow enough time for appraisal, insurance, title, condominium review, and lender conditions. Buyers can review a separate Puerto Rico closing-cost guide to build a fuller cash-to-close budget.
Puerto Rico Luxury Properties for Sale
Financing needs vary widely across Puerto Rico's luxury market, from resort estates and private compounds to coastal residences and buildable land. The examples below show why buyers should confirm loan size, property eligibility, appraisal strategy, insurance, and required reserves before making an offer. Explore additional luxury properties for sale and confirm current price and availability with the listing team.
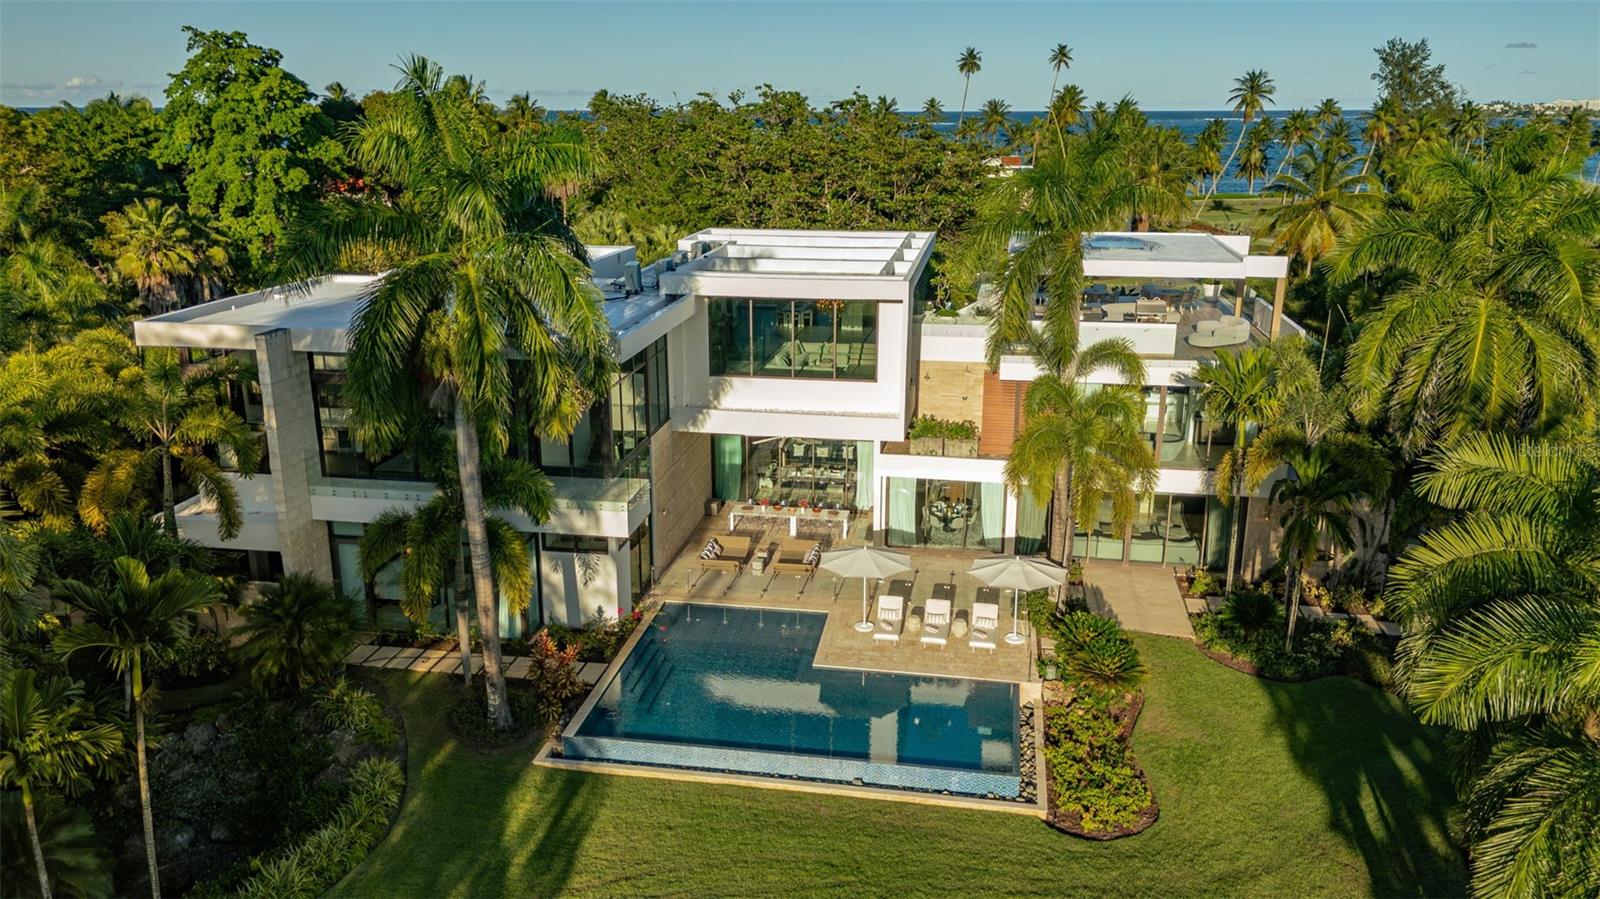
200 Dorado Beach Drive #2210, Dorado
Villa D'Or is an active seven-bedroom East Beach estate with 10,701 square feet of interior space on a 1.06-acre homesite. Its scale, resort setting, and $35 million asking price make lender capacity, appraisal support, insurance, reserves, and association obligations central financing questions.
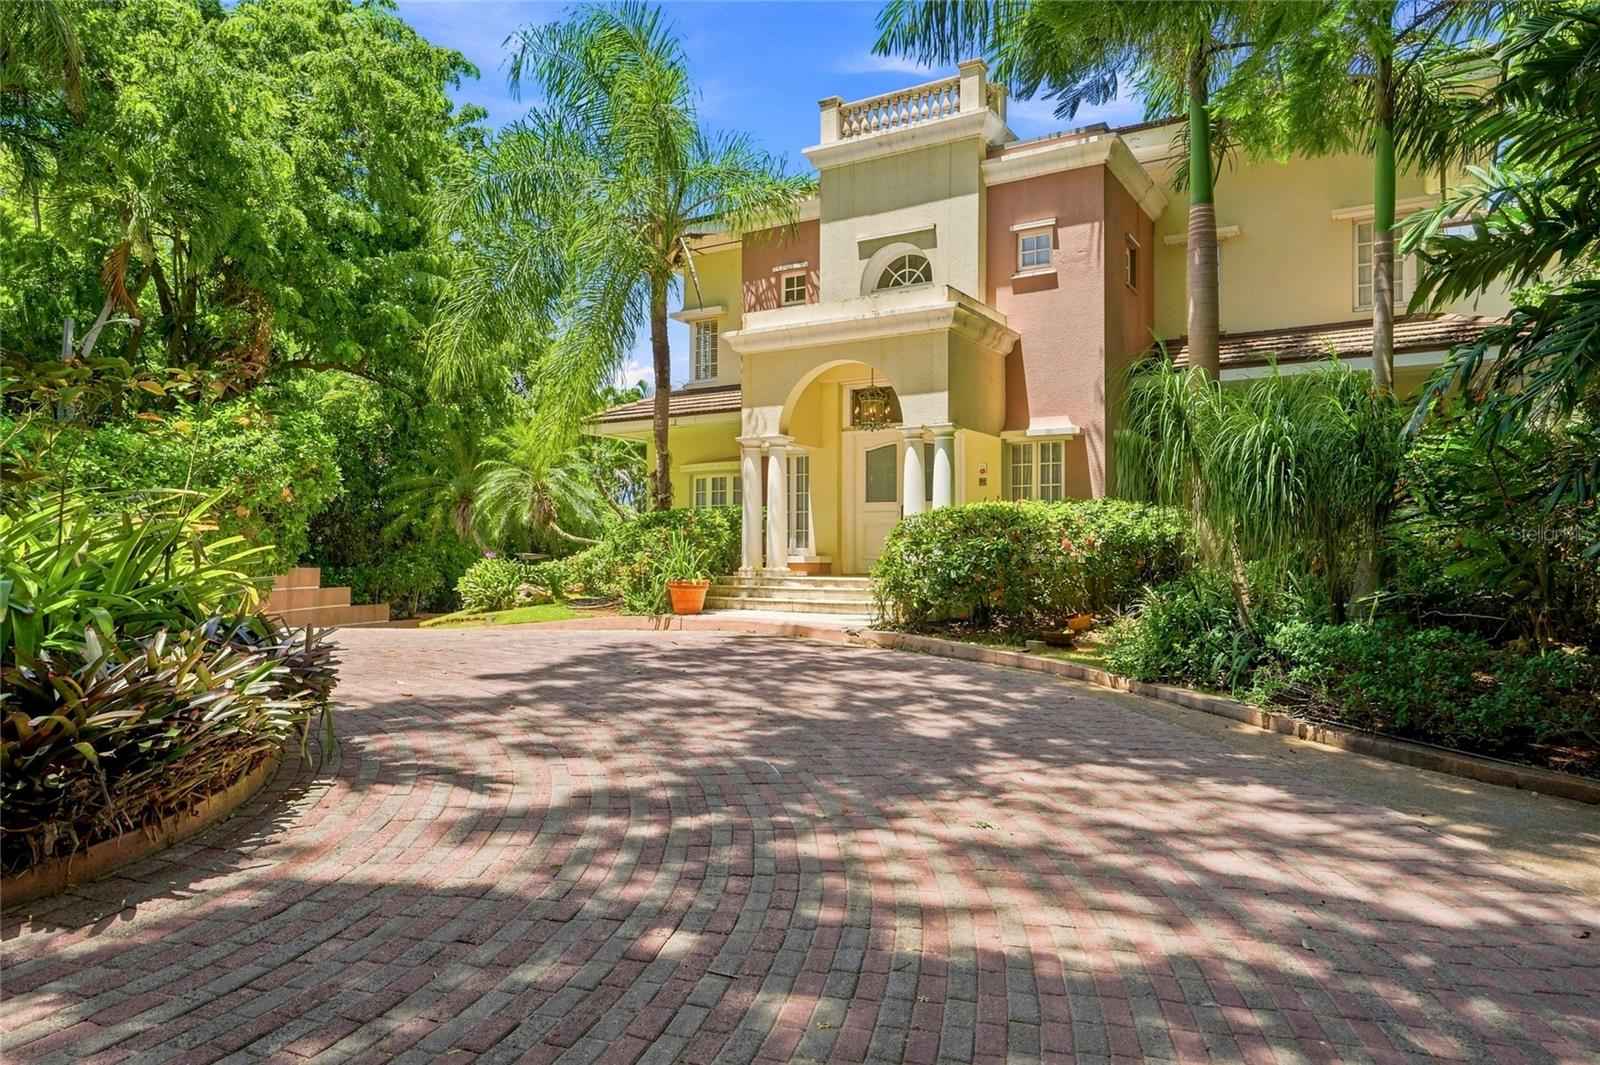
17 Calle Durazno, San Patricio, Guaynabo
This active five-suite Guaynabo estate offers 14,265 square feet of construction on approximately 1.54 acres. A buyer should confirm the appraisal scope, property insurance, pool and amenity condition, and financing treatment for the estate's scale and specialized features.
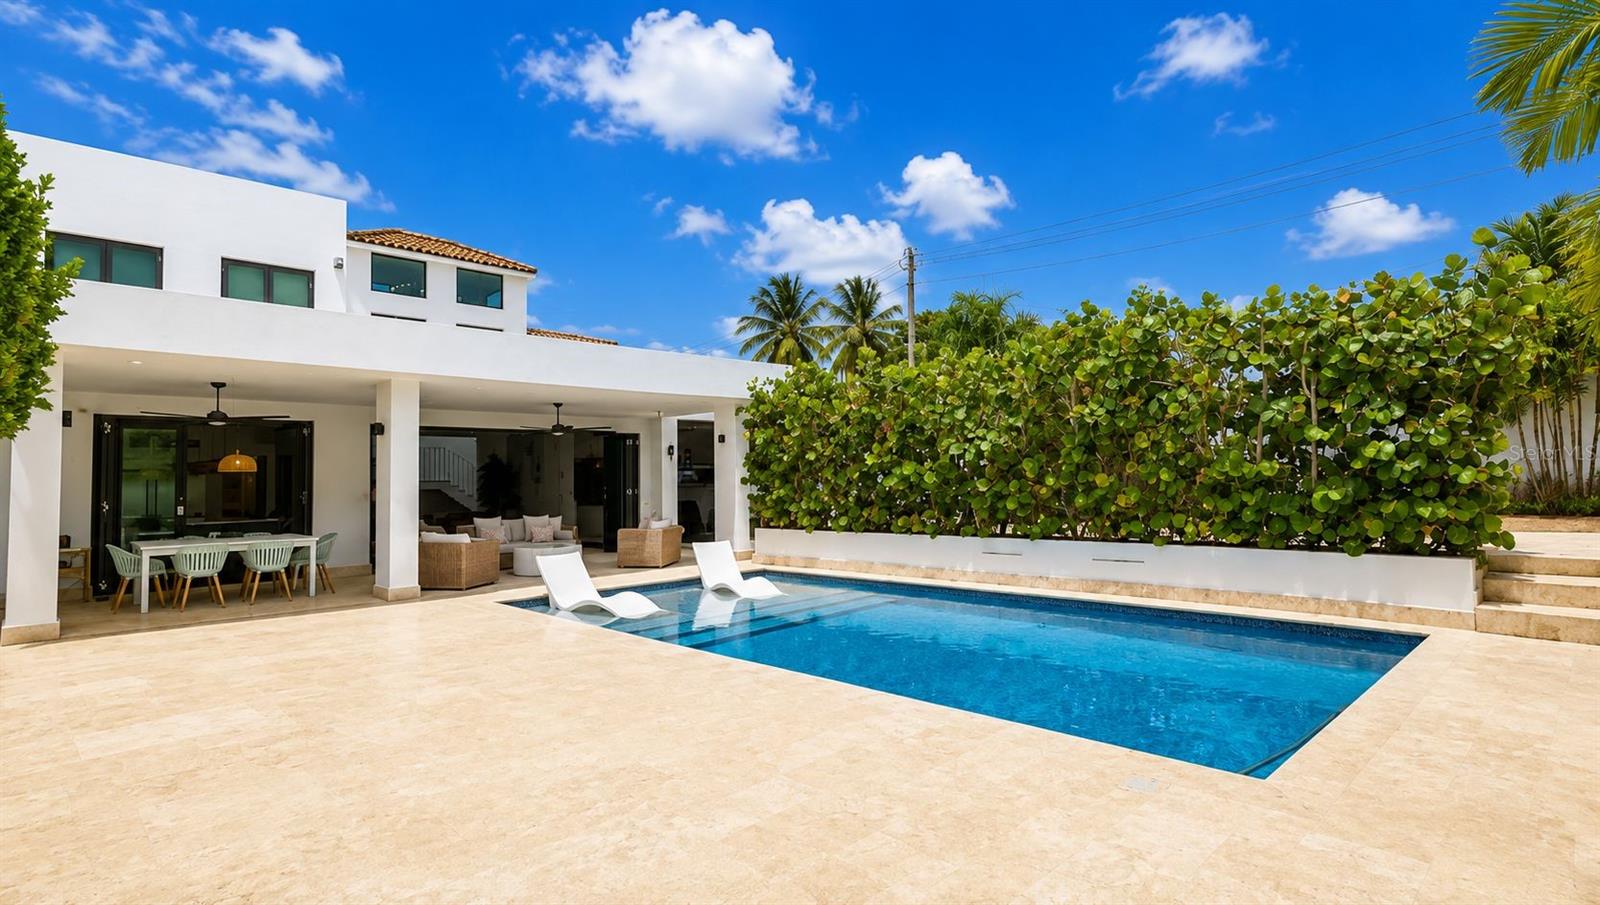
60 Soldado Serrano, San Juan
Villa Blanca is an active seven-bedroom residence near Ocean Park Beach with a pool, solar equipment, backup utilities, and flexible residential or rental use. Buyers should verify the permitted use, documented income if relevant, insurability, and whether the lender accepts the intended occupancy and rental structure.

2021 Calle Italia, San Juan
This active Ocean Park offering is an approximately 8,276-square-foot beachfront lot with permitted plans and direct beach access. Land and construction financing can differ from an existing-home mortgage, so buyers should confirm the accepted appraisal basis, draw structure, equity requirement, permits, insurance, and construction timeline.
Conclusion
A Puerto Rico mortgage should be evaluated as a complete financing and property package, not simply an advertised rate. The strongest preparation combines verified income and asset documentation with early review of appraisal, insurance, title, condominium, and intended-use issues. Written lender disclosures and property-specific professional advice should control the final decision.
If you want to rent, buy, or sell Puerto Rico luxury properties, Christie's International Real Estate Puerto Rico can help you coordinate the real estate side of the transaction and identify property questions to raise with your lender and advisers. Contact the team to compare current homes and plan the next steps for a Puerto Rico purchase or sale.
FAQs
Can a Mainland U.S. Lender Finance a Home in Puerto Rico?
Some mainland institutions finance Puerto Rico property, but many do not operate or lend on the island. Confirm that the lender is authorized and willing to finance the specific municipality, property type, condominium, ownership structure, and intended use before relying on a preapproval.
What Is the 2026 Conforming Loan Limit in Puerto Rico?
The 2026 conforming loan limit for a one-unit property in every Puerto Rico municipio is $832,750. Limits are higher for qualifying two-, three-, and four-unit properties, and a lender should confirm the limit and program applicable to the transaction.
How Much Down Payment Is Required for a Puerto Rico Luxury Home?
There is no single required percentage. The lender determines the equity contribution based on the loan program, price, occupancy, property, appraisal, borrower finances, reserves, and risk profile.
Does a Preapproval Guarantee the Mortgage?
No. A preapproval remains subject to underwriting, verification of the borrower's finances, an acceptable appraisal, title and insurance review, property eligibility, and any other lender conditions.
What Should a Buyer Compare Between Mortgage Offers?
Compare the rate, APR, points, origination charges, lender credits, mortgage insurance, required reserves, rate-lock period, estimated monthly payment, closing costs, and cash to close using the same assumptions. Review possible prepayment, balloon, or adjustable-rate terms as well.
Related Articles
These guides cover lender selection, borrowing structures, and the additional costs that can affect a financed Puerto Rico purchase.


