A buyer’s decision to finance a luxury home does not, by itself, mean the seller has accepted an appraisal contingency. Before signing, the parties generally negotiate the offer’s conditions; after signing, the agreed contract and any applicable loan-program requirements determine their obligations.
An appraisal contingency clause addresses what happens if the valuation falls below an agreed threshold. For a Puerto Rico purchase, review the wording with a local real estate attorney and coordinate it with the lender’s requirements before committing a deposit or waiving protection.
Key Takeaways
- An appraisal contingency is a negotiated contract condition, not a guarantee of value.
- A low appraisal may affect borrowing capacity and the cash needed to close.
- Cancellation rights and deposit refunds depend on the signed terms and timely notice.
- Financing contingencies and appraisal contingencies address different risks.
- Before waiving protection, confirm the maximum cash exposure and remaining obligations.
What Is an Appraisal Contingency Clause?
An appraisal contingency clause makes specified purchase obligations conditional on a property valuation meeting the threshold stated in the agreement. Depending on its terms, it may give the buyer a process for requesting a price adjustment or terminating if that threshold is not met.
An appraisal is a professional opinion of value, not a promise that the buyer will never overpay or that the home will appreciate. The CFPB’s guidance on a low appraisal recommends reviewing the report and considering price negotiations, while emphasizing that cancellation consequences depend on the purchase contract.
What Are Its Advantages for Buyers?
A carefully drafted clause can help a buyer manage valuation risk, but each protection has limits. Read it alongside the deposit provisions, financing conditions and notice requirements rather than assuming the heading alone provides a right to withdraw.
Potential benefit | What to confirm |
|---|---|
A valuation checkpoint | The minimum acceptable value, the appraisal to be used and the date by which it must be received. |
A negotiation opportunity | Whether the agreement provides a negotiation period; a low valuation does not automatically compel a price reduction. |
A possible exit right | The precise circumstances, notice method and deadline for termination, plus the deposit-release process. |
Better cash planning | The lender’s revised loan amount, required reserves and estimated cash to close. |
A clearer decision | Whether the purchase still fits the buyer’s budget after considering the valuation and other due-diligence findings. |
For Fannie Mae purchase-loan LTV calculations, the value generally used is the lower of the sales price or current appraised value. Luxury buyers using jumbo or portfolio financing should obtain their own lender’s calculation and conditions; an appraisal contingency does not guarantee loan approval.
Appraisal Contingency Addendum: Formalizing the Agreement
The clause may appear in the purchase agreement or in an agreed addendum. Have counsel confirm that the documents work together and that any modification is properly accepted; a generic mainland form should not be assumed suitable for a Puerto Rico transaction.
Key Elements to Review
- Threshold: The value required and whether it is tied to the purchase price or another amount.
- Evidence: Which valuation qualifies and what supporting documentation must be supplied.
- Deadlines: Appraisal delivery, objections, negotiation, extension requests and termination notices.
- Deposit treatment: The conditions for a refund and the procedure for releasing funds.
- Gap coverage: Any agreed cap on additional cash and how it interacts with the financing clause.
- Other requirements: Loan-program provisions and remaining inspection, title or property-approval conditions.
Possible Outcomes After the Appraisal
Result | What it means for the decision |
|---|---|
Value meets the agreed threshold | The valuation condition may be satisfied, but other contract and loan conditions can remain outstanding. |
Value falls below the threshold | Follow the clause’s notice and negotiation process; evaluate any available termination right. |
Buyer waived the appraisal condition | Do not assume a low appraisal creates an exit right. Ask counsel about remaining obligations and potential remedies. |
Owner’s Contingency: A Separate Construction Budget Concept
An owner’s contingency in a construction budget is a reserve for unexpected project costs, not an appraisal contingency in a purchase agreement. A renovation reserve does not create a cancellation right or require a seller to reduce the sale price.
For a luxury home requiring work, ask the project team to assess design changes, concealed defects, permitting issues and material substitutions. Set the reserve from the project’s scope and risks rather than applying an unsupported fixed percentage to every build or renovation.
Financing Contingency vs. Appraisal Contingency
A financing contingency concerns the buyer’s ability to obtain the financing described in the agreement. An appraisal contingency concerns the valuation threshold; the two can overlap in practice, but they are not interchangeable.
- Financing condition: Check the required loan terms, application duties, evidence of a denial and response deadline.
- Appraisal condition: Check what valuation triggers action and which options remain if it falls short.
- Timing: The appraisal can be part of underwriting, so it need not occur after final financing approval.
- Waiver: Removing one condition does not explain what the other protects; review both together.
The CFPB explains that the financing clause governs whether a deposit is refundable when a purchase fails because a loan cannot be obtained. Refusing a loan or missing a deadline is not automatically a penalty-free exit, and a seller may have rights beyond retaining a deposit.
How Long Does a Financing Contingency Last?
Use the deadline in the signed agreement; there is no single 21–30-day period that should be assumed for every transaction. Confirm how time is counted, what notice is required and whether an extension must be agreed in writing.
A preapproval can support an offer, but it is not final underwriting approval and does not automatically keep a contingency active. Ask the lender what borrower and property conditions remain, then coordinate the contract timetable before a deadline expires.
- Keep a calendar of application, appraisal, financing and closing dates.
- Respond promptly to document requests and retain confirmation of delivery.
- Ask about an extension early if the lender expects a delay.
- Obtain legal advice before cancelling, allowing a deadline to pass or signing a waiver.
How Does an Appraisal Contingency Work?
The process runs from negotiating the clause to reviewing the valuation and following the agreed response procedure. Keep the purchase-contract deadlines separate from the lender’s internal underwriting timetable.
1. Inclusion and Acceptance
The buyer proposes the appraisal contingency clause as part of the offer, and the seller can discuss its threshold, timing and remedies before accepting the agreement. Once a clause has been agreed, the seller cannot simply treat it as absent because a low valuation is inconvenient; counsel should explain the signed obligations.
Review Puerto Rico real estate financing early enough to align the offer with the loan being sought. Ask the lender whether the selected program requires any specific valuation-related language or protections.
2. Appraisal Process
For a financed purchase, the lender generally arranges the valuation required by its program. Fannie Mae’s appraisal overview explains that property characteristics, condition, location and comparable sales can influence the assessment, and that an appraisal is distinct from a home inspection.
Luxury homes may have features that need careful documentation, such as substantial renovations, a large site or an unusual layout. Supply accurate property information through the appropriate channel; neither an asking price nor construction cost alone establishes the appraised value.
Under Regulation B’s appraisal-copy rules, applicants for credit secured by a first lien on a dwelling generally receive copies of appraisals and other written valuations promptly upon completion or at least three business days before consummation, whichever is earlier, subject to the rule’s exceptions and permitted timing waivers. Waiving advance delivery is not the same as waiving a purchase-contract appraisal contingency.
3. Reviewing the Appraisal
Compare the report with the contractual threshold and ask the lender for its effect on the proposed loan. If the value is low, separate three questions: whether the report is accurate, how much cash the loan now requires, and what the contract permits.
- Request a price adjustment if appropriate; the seller’s agreement is not guaranteed.
- Evaluate additional cash only after receiving the lender’s revised figures.
- Use any available termination procedure precisely, including notices and deadlines.
If the report appears inaccurate, ask the lender about a reconsideration of value. Identify specific errors, omissions or relevant comparable evidence; requesting a review does not guarantee a higher value or automatically extend a contract deadline.
4. Negotiation and Resolution
Document any agreed price change, extension or gap contribution in the form advised by counsel, and send changes to the lender. A seller credit is not necessarily equivalent to a price reduction or additional buyer cash, so confirm how the proposed solution affects underwriting.
If there is no agreement, the next step depends on the existing contract rather than an automatic right for either party to cancel. Confirm which conditions remain in effect and how the deposit will be handled before treating the transaction as terminated.
Partial Waiver of the Appraisal Contingency Clause
A limited appraisal-gap commitment can define how much valuation shortfall a buyer is willing to accept while retaining specified protection below that limit. The exact drafting matters: a gap cap, a minimum acceptable value and a cap on total cash to close are different instructions.
Hypothetical example: A $700,000 contract and a $675,000 appraisal create a $25,000 price-to-value gap. A clause addressing that amount still needs to state what happens below the threshold and how other financing requirements are treated; it does not promise a timely closing.
Questions Before Agreeing to a Partial Waiver
- Is the commitment a fixed dollar amount, a minimum valuation or another formula?
- Does it limit total additional cash, or only the difference between price and appraisal?
- What happens if the shortfall exceeds the agreed limit?
- Are financing, inspection and other protections retained?
Appraisal Gap vs. Additional Cash: An Illustration
Assume a $1,500,000 purchase and an illustrative lender limit of 80% of the lower of price or appraised value, with no other loan constraints. These are hypothetical calculations, not a lender quote or a description of a completed Puerto Rico sale.
Scenario | Loan at assumed 80% LTV | Buyer cash toward price |
|---|---|---|
Appraisal: $1,500,000 | $1,200,000 | $300,000 |
Appraisal: $1,400,000 | $1,120,000 | $380,000 |
In this illustration, the $100,000 appraisal gap increases the cash toward the price by $80,000, not automatically $100,000. Closing costs, reserves and other charges are excluded; ask the lender to calculate the actual cash to close under the proposed structure.
What Influences a Seller’s Acceptance of an Appraisal Contingency?
Sellers may weigh the offer price, funding evidence, timing and conditions together. Neighborhood reputation alone does not establish whether a particular property has competing offers or whether a seller will accept a clause.
Competing Offers
A seller comparing several offers may prefer fewer conditions, but removing an appraisal clause does not guarantee financing or a faster closing. For a home in Dorado or another luxury market, assess the actual offer situation rather than assuming every listing has the same negotiating dynamic.
Buyer’s Leverage
The property’s time on the market, the seller’s priorities and the strength of the buyer’s proposal can inform negotiations. A Palmas del Mar address alone does not establish that the market is slow or that the seller must accept a contingency.
Risk and Available Cash
A buyer considering a waiver should assess both liquidity and the consequences of being unable to close. Whether purchasing in Condado or elsewhere, do not assume the earnest-money deposit is the maximum possible exposure; obtain advice on the agreement and applicable law.
Negotiated Terms
Buyers and sellers can discuss the threshold, response period and any capped gap commitment before signing. For a San Juan purchase, have Puerto Rico counsel check how the language fits the rest of the agreement, rather than relying on an informal promise to “split the difference.”
Puerto Rico Luxury Properties to Compare
The existing selections below illustrate different property types and locations; none is represented here as independently appraised or guaranteed to qualify for financing. Three were listed as active when checked, while The Meadows Estates property was pending. Explore luxury properties for sale with our team and confirm status and lender requirements before making an offer.
2 RAMPLA DEL ALMIRANTE #A, SAN JUAN, PR
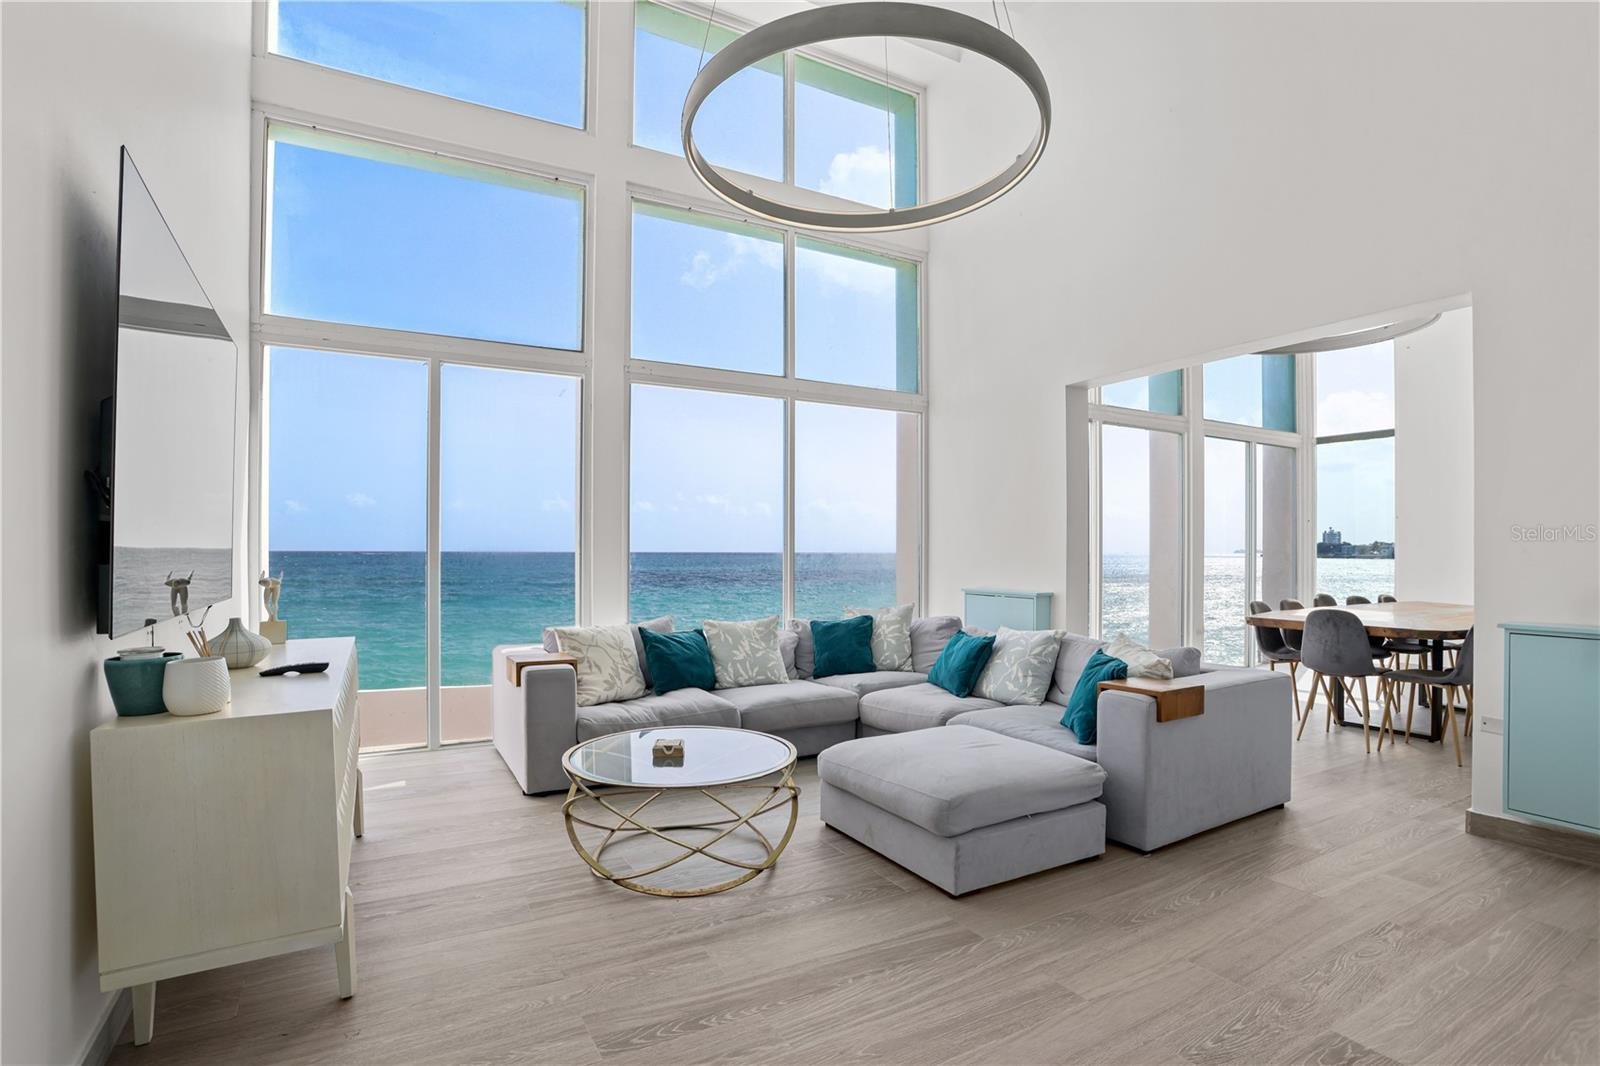
This Ocean Park residence in San Juan is listed with five bedrooms, five full bathrooms and one half bathroom, with ocean views and a rooftop terrace. Its listing also describes a pool, backup generator, water cisterns and garage parking for up to four vehicles.
2200 DORADO BEACH DR #3, DORADO, PR
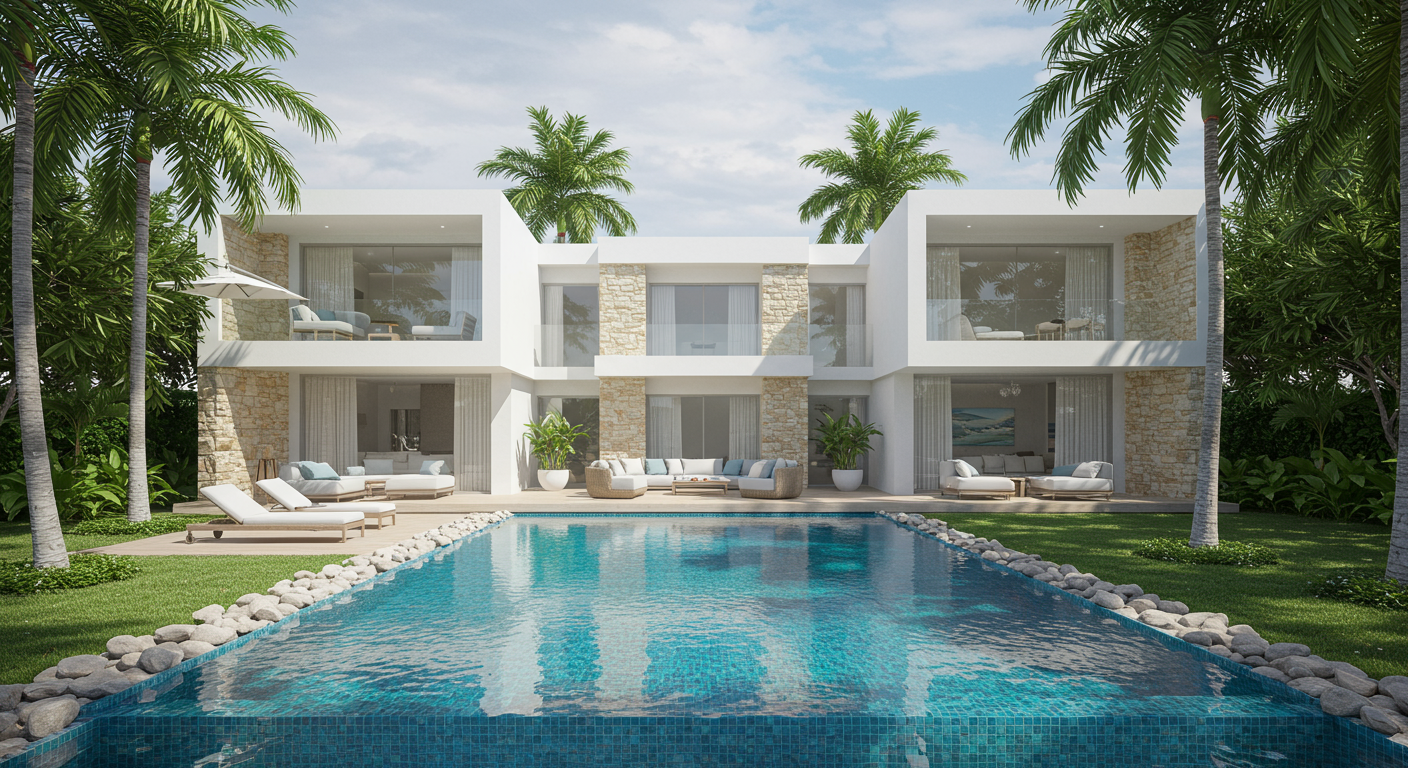
This East Beach estate in Dorado is listed with five bedrooms, approximately 5,611 square feet of interior space and a one-acre lot. The property description includes a pool, garden terraces and golf-course views, features to review alongside the lender’s valuation requirements.
7 CALLE ROSA #PH, CAROLINA, PR
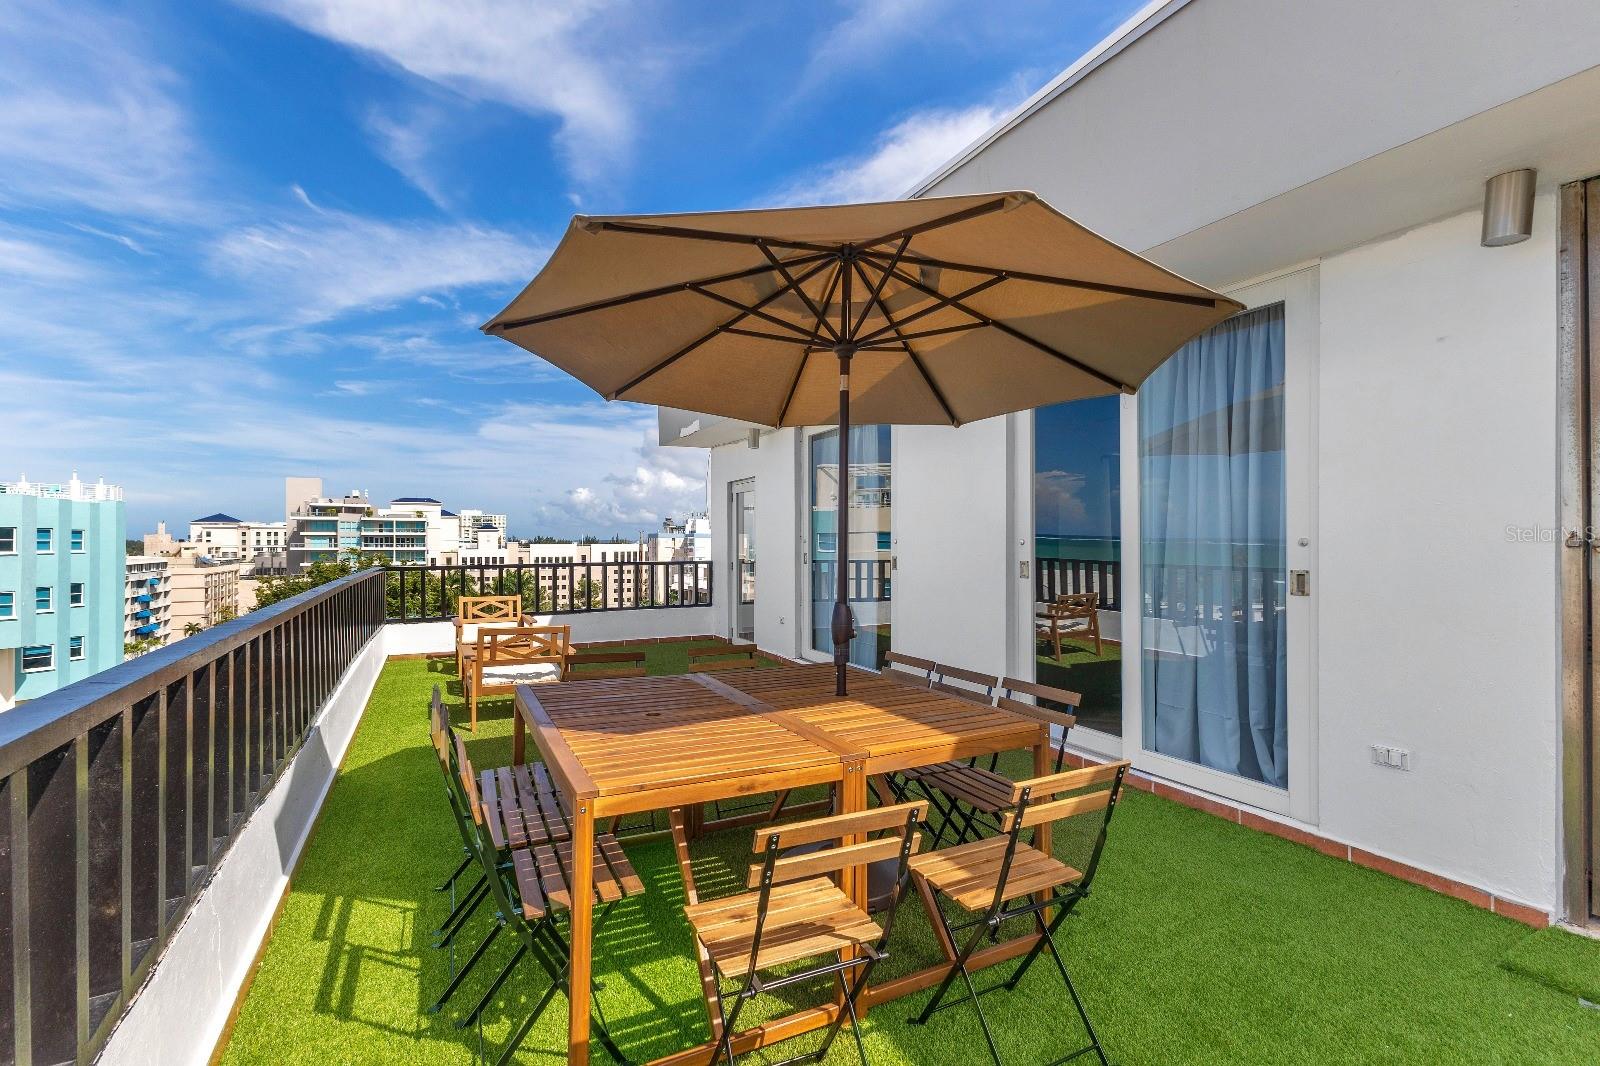
This Isla Verde penthouse in Carolina is listed with six bedrooms, five bathrooms, ocean views and two dedicated parking spaces. Before planning rental use or financing it as an investment, independently verify condominium rules, applicable permissions and the lender’s occupancy requirements.
13 THE MEADOWS ESTATES, GUAYNABO, PR — Pending
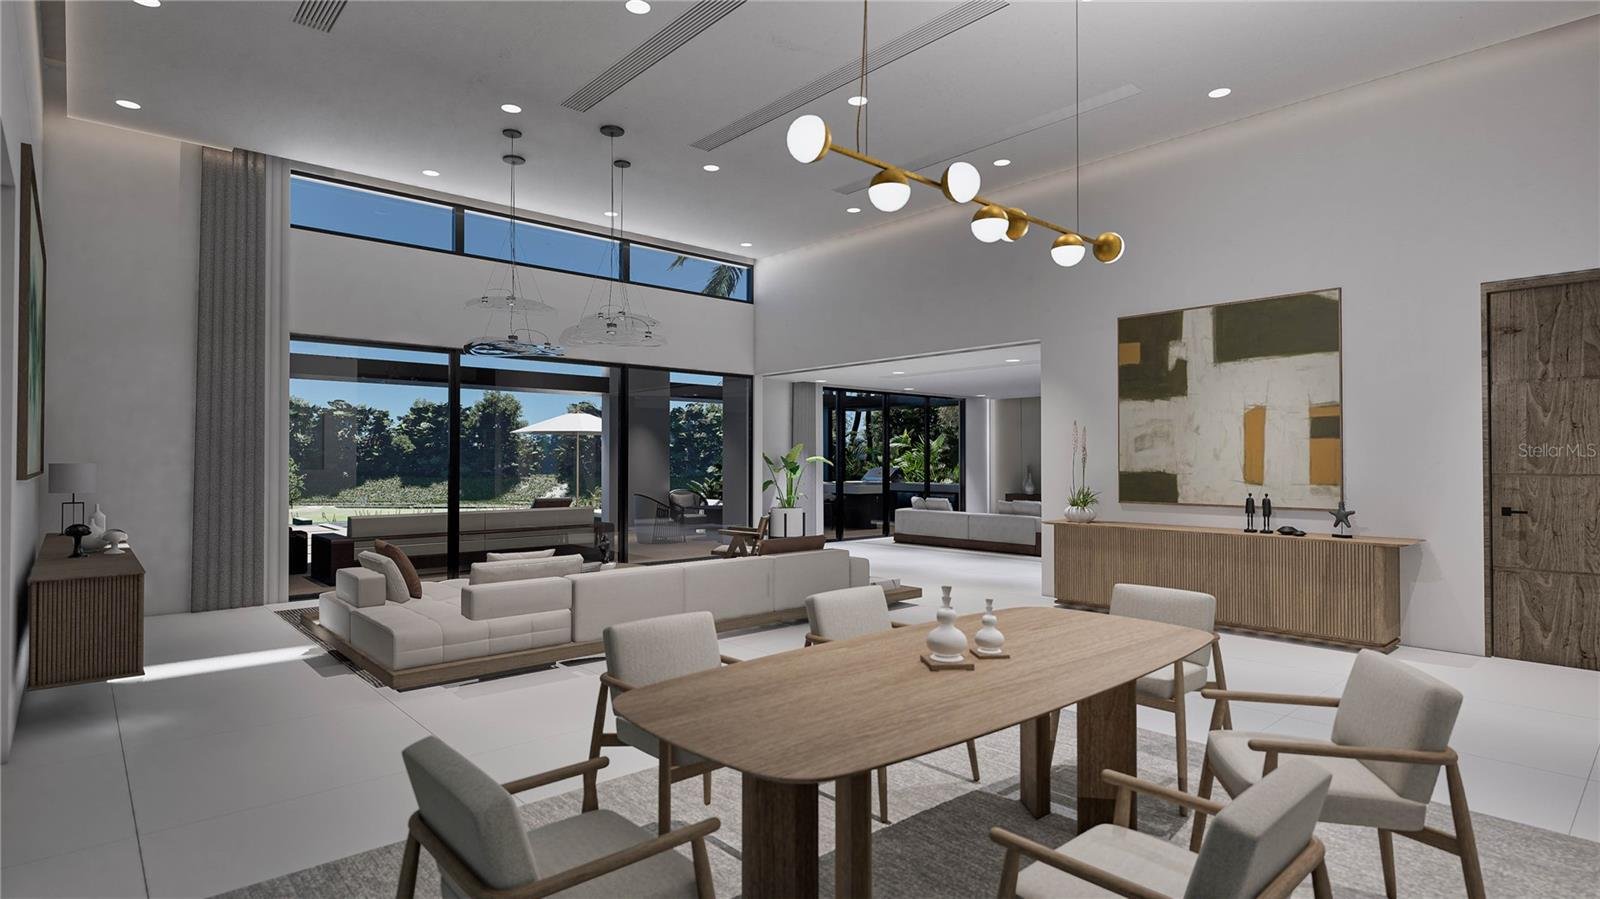
This Guaynabo pre-construction property is marked pending and under contract, so it should not be treated as an available purchase option without a status update. Its listing describes a planned five-bedroom home with six full bathrooms and one half bathroom, and identifies the images as renderings rather than completed construction.
Compare locations through the Puerto Rico neighborhood guides and confirm listing details directly before relying on them.
Conclusion
An appraisal contingency is useful only when its wording, deadlines and remedies match the transaction. Buyers should understand the cash implications of a low valuation, while sellers should distinguish negotiating an offer from honoring conditions already accepted. Before signing or waiving a clause, coordinate the purchase agreement with Puerto Rico legal advice and the lender’s requirements.
If you want to rent, buy or sell Puerto Rico luxury properties, Christie’s International Real Estate Puerto Rico is here to guide you. Contact our team to discuss suitable properties and coordinate the next steps with your lender and legal advisers.
FAQs
These answers clarify common terms, but the signed agreement controls the transaction’s specific conditions. Have counsel review any uncertainty before a notice or waiver deadline.
What is a contingency in a real estate transaction?
It is a contract condition addressing an event or requirement that affects the parties’ obligations. It does not automatically provide an unrestricted right to cancel or an immediate deposit refund; those consequences depend on the clause and the applicable procedures.
What are common contingencies in real estate?
Financing, appraisal, inspection and title-related conditions address different purchase risks. The appropriate combination depends on the property, funding and negotiated agreement, so no single condition should be presented as universally sufficient.
What is a financing contingency?
It is a provision tying specified purchase obligations to obtaining the financing described in the contract. Review the loan terms, required application efforts, deadlines and deposit provisions rather than assuming that any loan refusal permits cancellation.
Does waiving an appraisal contingency remove the lender’s appraisal requirement?
No: a buyer’s contractual waiver and the lender’s valuation requirements are separate matters. Ask the lender whether an appraisal or another permitted valuation process is required, even if the purchase agreement contains no appraisal condition.
Related Articles
Use these related guides to prepare for financing, insurance and property due diligence in Puerto Rico.