Insurance for a Puerto Rico waterfront home should begin with the property's location, construction, replacement cost, flood zone, and lender requirements—not with a generic homeowners quote. Coastal homes can face wind, flood, salt exposure, erosion, and higher rebuilding costs, while individual policies may exclude or limit some of those risks. This guide explains the principal questions buyers and owners should raise with a licensed Puerto Rico insurance producer before binding coverage.
Key Takeaways
- Property policies generally exclude flood damage, so owners may need separate NFIP or private flood insurance.
- Federal flood-insurance requirements generally apply when a building is in a Special Flood Hazard Area and secures a federally backed mortgage; a lender may impose additional requirements.
- Wind and hurricane coverage, deductibles, limits, and exclusions vary by policy and should be reviewed before closing or renewal.
- Insured value should reflect current reconstruction or replacement cost, which can differ from a property's market value.
- Obtain quotes early, document mitigation features, and review coverage with a licensed Puerto Rico insurance producer.
Key Home Insurance Coverage for Puerto Rico Waterfront Properties
Investing in high-value homes, such as beachfront luxury properties, is a statement of both sophistication and an affinity for the serene beauty of coastal life. Yet, the idyllic setting comes with unique challenges, particularly from the insurance perspective. Coastal properties face distinct risks that are less prevalent or absent in inland locations. Recognizing and mitigating these risks through appropriate insurance coverage is paramount in safeguarding such a significant investment.
1. Flood Insurance
Puerto Rico flood insurance deserves separate attention because property policies generally exclude direct flood damage. Owners can explore coverage through the National Flood Insurance Program (NFIP), when the community participates, or through private insurers. Availability, limits, exclusions, and pricing depend on the property and policy.
Eligibility for Flood Insurance
- NFIP participation: An NFIP policy is available only in a community that participates in the program and follows its floodplain-management requirements.
- Property location: The building's exact location and flood-zone information affect the risk review and may affect lender requirements and pricing.
- Building details: Construction, elevation, occupancy, foundation type, and floodproofing or mitigation features may be relevant to underwriting.
Special Flood Hazard Areas (SFHAs)
FEMA identifies Special Flood Hazard Areas on Flood Insurance Rate Maps. According to NFIP eligibility guidance, flood insurance is required when a home or business is in an SFHA and has a government-backed mortgage. Other lenders may require coverage under their own terms, even outside a mapped high-risk area.
Use the FEMA Flood Map Service Center to check official mapping for a specific property, then confirm the result and any insurance requirement with the lender and a licensed insurance producer.
2. Wind and Hurricane Coverage
Puerto Rico waterfront homes can have substantial exposure to hurricanes and tropical-storm winds. Review whether windstorm insurance is included in the property policy, added by endorsement, or written separately. Pay particular attention to named-storm or hurricane deductibles, coverage limits, roof provisions, exclusions, and loss-settlement terms.
Reviewing Wind and Hurricane Coverage
Underwriting and pricing may consider factors such as:
- Property location and exposure
- Construction type and year built
- Roof age, condition, and attachment
- Storm shutters, impact-rated openings, and other documented mitigation
- Current reconstruction or replacement cost
If you are financing the property, the lender may require property coverage that protects its collateral. Confirm the precise requirements before closing.
3. Named Perils, Exclusions, and Coastal Risks
There is no single policy label that guarantees every coastal risk is covered. Some policies cover only named perils, while others use broader forms subject to exclusions. When comparing peril insurance options, verify the actual contract language rather than relying on a product name.
Ask specifically about flood, wind, storm surge, water intrusion, earth movement, coastal erosion, mold, ordinance-or-law costs, debris removal, landscaping, pools, docks, seawalls, backup of sewer or drain, and additional living expense. Some of these exposures may be excluded, limited, or unavailable under a standard homeowners policy.
Questions to Ask Before Binding Coverage
- Covered causes of loss: Which perils are covered, excluded, or subject to a separate deductible?
- Replacement cost: Are the dwelling limit and loss-settlement terms appropriate for rebuilding with comparable materials?
- Condo responsibilities: For a condominium, what does the association master policy cover and where does the unit owner's responsibility begin?
- Mitigation documentation: Which inspections, permits, photographs, or certifications can support underwriting or possible discounts?
Understanding Home Insurance Policy Types in Puerto Rico
Understanding the different types of homeowner insurance policies can help you choose the right protection based on your property type and usage. When comparing homeowners insurance in Puerto Rico, here are the most common policy types you’ll encounter:
Policy Type | Best For | What It Covers |
|---|---|---|
HO2 – Broad Form | Traditional single-family homeowners | Covers specific named perils like fire, theft, and windstorms for both structure and belongings. |
HO3 – Special Form | Owner-occupied homes; availability varies | Offers broader protection for the home structure (open perils) and personal property (named perils). |
HO4 – Tenant’s Form | Renters | Covers personal belongings and liability but not the building structure. |
HO6 – Condo Form | Condominium owners | Covers interior walls, fixtures, and personal property, often required by HOAs. |
These labels describe common policy forms, but availability and wording can vary by insurer. Confirm the declarations, endorsements, exclusions, and the responsibilities of any condominium association master policy. The Puerto Rico Office of the Commissioner of Insurance lists insurers operating in Puerto Rico.
How to Apply for These Insurances
A meticulous and informed approach is essential as you prepare to secure insurance for your luxury beachfront properties. The following outline delineates the comprehensive steps necessary to navigate the application process for these specialized insurances effectively:
How to Apply | Insurance Type | Description |
Assess Your Coverage Needs | All | Evaluate risks specific to your property and decide whether you need coverage as an addition to your high-value homeowners' insurance or as a separate policy. This decision is influenced by the property's location and potential exposure to natural disasters. |
Shopping for Insurance | All | Options may include endorsements to a property policy, separate wind or flood coverage, an NFIP policy where eligible, or private coverage. Availability depends on the property and insurer. |
Contacting Insurance Providers | All | Ask a licensed Puerto Rico insurance producer whether wind and hurricane coverage is included, added by endorsement, or written separately, and verify the insurer through the Puerto Rico Office of the Commissioner of Insurance. |
Application Process | All | Likely involves providing detailed property information, including construction, age, and mitigation measures like storm shutters or reinforced roofing. |
Consider a Wind Mitigation Inspection | Windstorm Insurance | This inspection assesses your home's features and improvements against wind damage, potentially leading to premium discounts. |
Check Your Community's Participation | Flood Insurance | Verify if your community participates in the NFIP by visiting FEMA's website or contacting local government offices. |
Assess Your Risk | Flood Insurance | Use tools like FEMA's Flood Map Service Center to understand your property's flood zone and insurance requirements. |
Consider Private Insurers | Flood and High Hazard Homeowners/Peril | For coverage beyond what the NFIP offers (Flood Insurance) or for specialized high-hazard coverage, contact private insurers offering higher limits or benefits not available through standard policies. |
Prepare Necessary Documentation | High Hazard Homeowners/Peril Insurance | Provide details on construction, existing mitigation measures, compliance with building codes, and property valuation. |
Review Quotes and Policies | All | Review the coverage details, exclusions, and premiums in quotes received. Ensure the policy addresses the specific perils your property is at risk for. |
Finalize the Application | All | Complete the application process by submitting all required documentation and making the initial premium payment. |
Note:
For Flood Insurance: NFIP coverage generally begins after a 30-day waiting period, but exceptions can apply—for example, when coverage is purchased in connection with making, increasing, extending, or renewing a mortgage. Review the current NFIP policy terms and confirm the effective date before relying on coverage.
Puerto Rico Insurance Guidance for 2026
The Puerto Rico Office of the Commissioner of Insurance advises property owners to review policies before hurricane threats arise, keep insured values aligned with current reconstruction or replacement cost, understand hurricane and wind deductibles, and examine exclusions, limits, and coinsurance provisions with an insurance producer.
Puerto Rico property policies generally exclude flood damage, so flood protection requires separate review. Financial institutions commonly require property insurance as a condition of a mortgage, but coverage needs and lender requirements are property- and loan-specific. The article's prior blanket claims that every homeowner must carry a policy covering fire, hurricanes, floods, and earthquakes, that deductibles are universally capped at 5%, and that mitigation discounts are always mandatory have been removed because they could not be supported as general current rules.
Factors that Affect Insurance Costs
The cost of beachfront property insurance is influenced by various factors, mainly due to the unique challenges associated with coastal properties. The proximity to the ocean increases exposure to specific risks such as strong winds, salt water, and the potential for floods, all of which can significantly impact the price of insurance coverage. High-value home insurance in Puerto Rico, therefore, becomes a vital consideration for beachfront property owners, offering comprehensive protection that extends beyond the physical structure to include belongings and potential liabilities.
Key factors that affect the cost of beachfront property insurance include:
- Proximity to the Ocean: The closer your property is to the ocean, the higher the risk of damage from coastal threats, leading to higher insurance costs.
- Past Weather Conditions: The history of weather conditions and natural disasters in your area can also affect insurance pricing, with areas prone to hurricanes and floods often facing higher premiums.
- Unique Property Characteristics: Specific features of your property, such as its construction materials, age, and any implemented mitigation measures against coastal risks, play a role in determining your insurance costs and the possible replacement cost coverage.
Tips for Beachfront Property Investors
To effectively manage and reduce insurance costs for beachfront properties, consider these strategies:
- Opting for Higher Deductibles: Increasing your deductible can indeed lower your premium costs. Insurance experts recommend this strategy, as a higher deductible lowers premiums because you'll cover a larger share of any loss. However, make sure you can afford the higher out-of-pocket costs if you file a claim.
- Consolidating Policies: Bundling different types of insurance policies can often result in discounts. Insurers may offer price reductions to customers who hold multiple policies, such as homeowners, auto, and flood insurance, through the same insurance company.
- Implementing Risk Mitigation Measures: Taking steps to reduce your property's vulnerability to coastal risks can lead to premium discounts. Measures such as installing storm shutters, reinforced roofing, and other storm-proofing modifications can make your property more resilient to damage from coastal storms, and insurers may reward you with lower premiums.
- Regularly Review and Compare Insurance Options: Periodically review your insurance coverage to ensure it meets your current needs at competitive rates. Markets and available coverages can evolve, so stay informed and consider adjusting your coverage or shopping around for better rates.
Puerto Rico Luxury Properties for Sale
After reviewing flood zones, wind exposure, replacement costs, and policy exclusions, buyers can apply the same due diligence questions to current coastal opportunities. The following luxury properties for sale represent different waterfront settings across Puerto Rico, from beachfront condominiums and a resort residence to coastal land. Listing availability can change, so confirm the current status and property-specific insurance requirements before deciding.
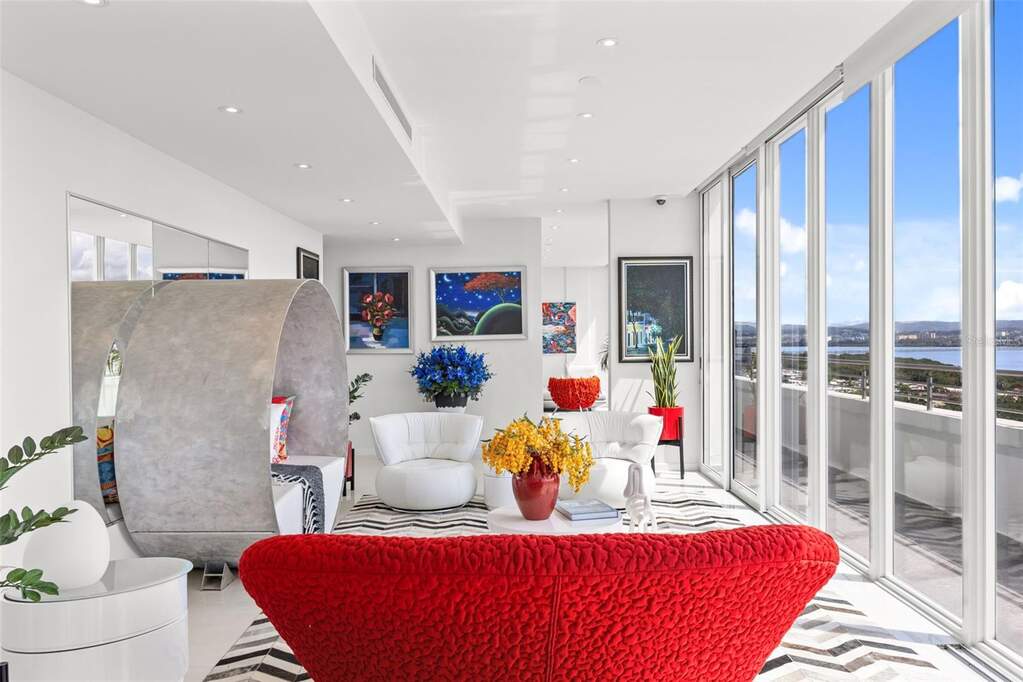
3307 AVE ISLA VERDE #PH, CAROLINA, PR
This beachfront Isla Verde penthouse offers 6,149 square feet, five bedrooms, six bathrooms, broad terraces, and direct beach frontage. Its ocean exposure and high-value finishes make it especially important to review replacement-cost assumptions, wind and flood coverage, deductibles, and policy limits.
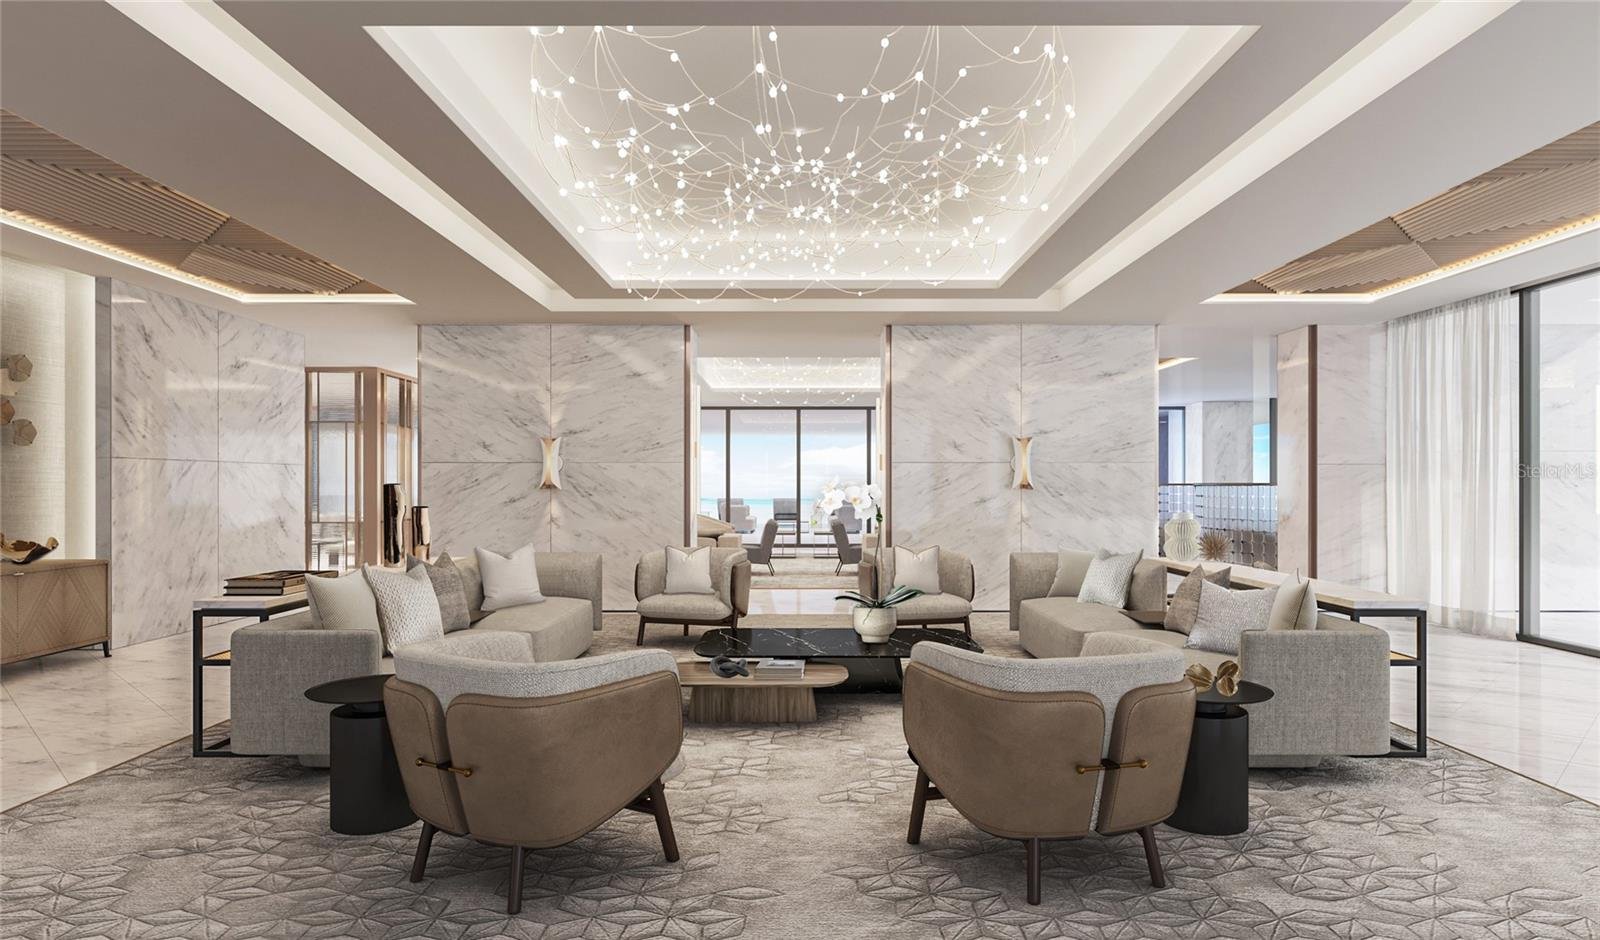
1149 ASHFORD AVENUE VANDERBILT RESIDENCES #1602, SAN JUAN, PR
This four-bedroom oceanfront condominium at Vanderbilt Residences offers 3,965 square feet and expansive Atlantic Ocean views in Condado. Its condominium format makes the association master policy, unit-owner coverage, wind deductibles, and building replacement provisions especially important to review.
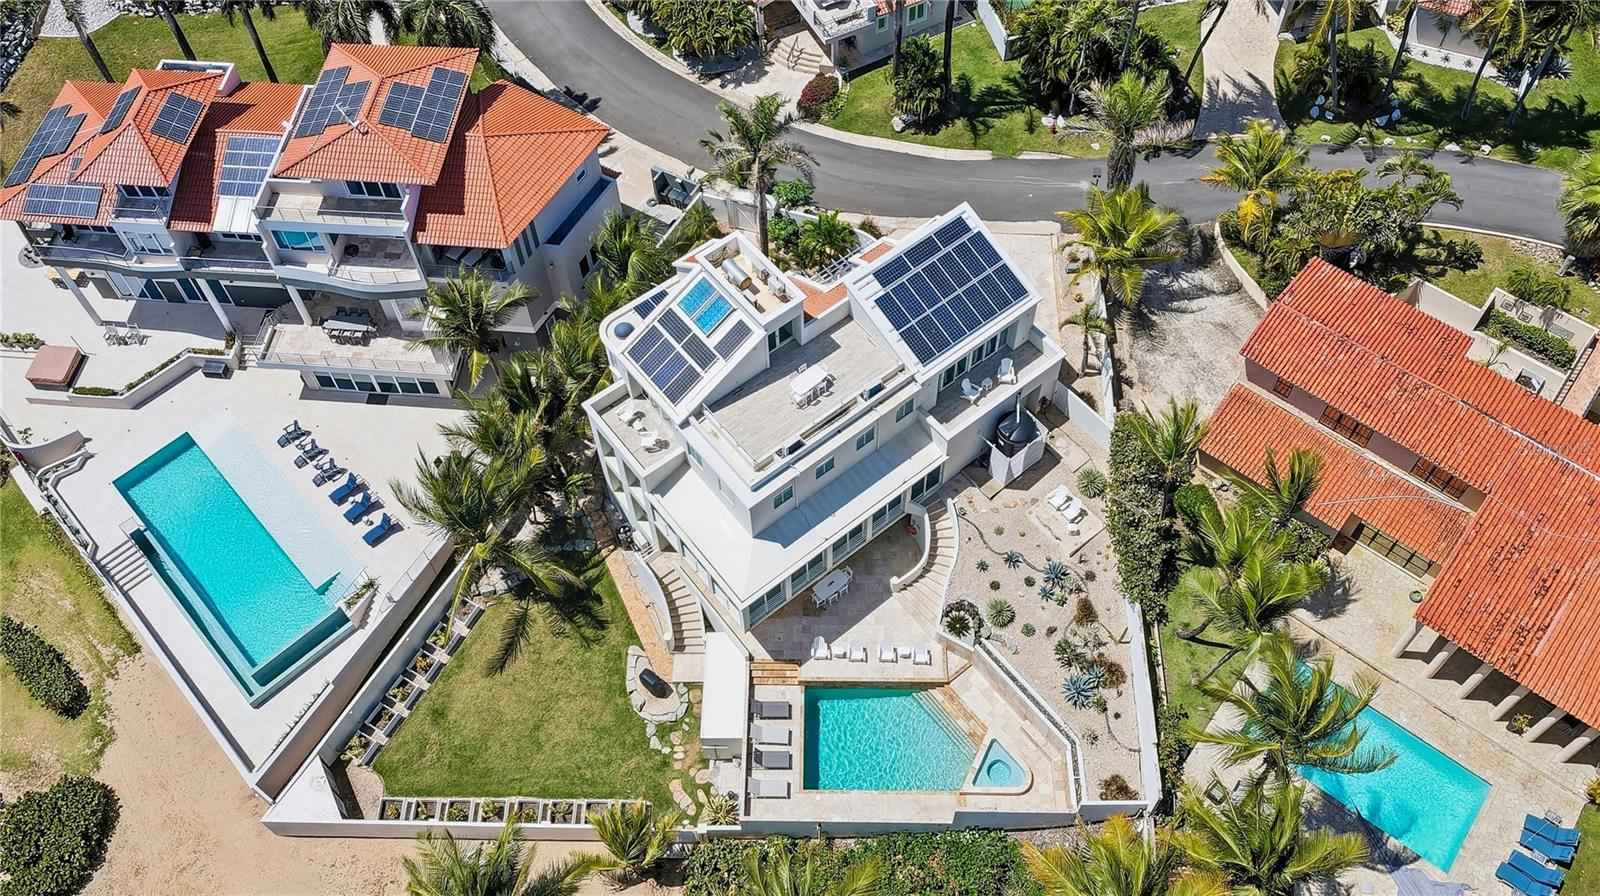
32 SHELL CASTLE, HUMACAO, PR
32 Shell Castle is a five-bedroom oceanfront retreat in Palmas del Mar featuring approximately 5,500 square feet of contemporary living space, panoramic ocean views, a pool terrace, and solar power with dual Tesla Powerwalls, offered at $5,250,000 through December 31, 2026.
372 CALLE FULLADOZA, CULEBRA, PR
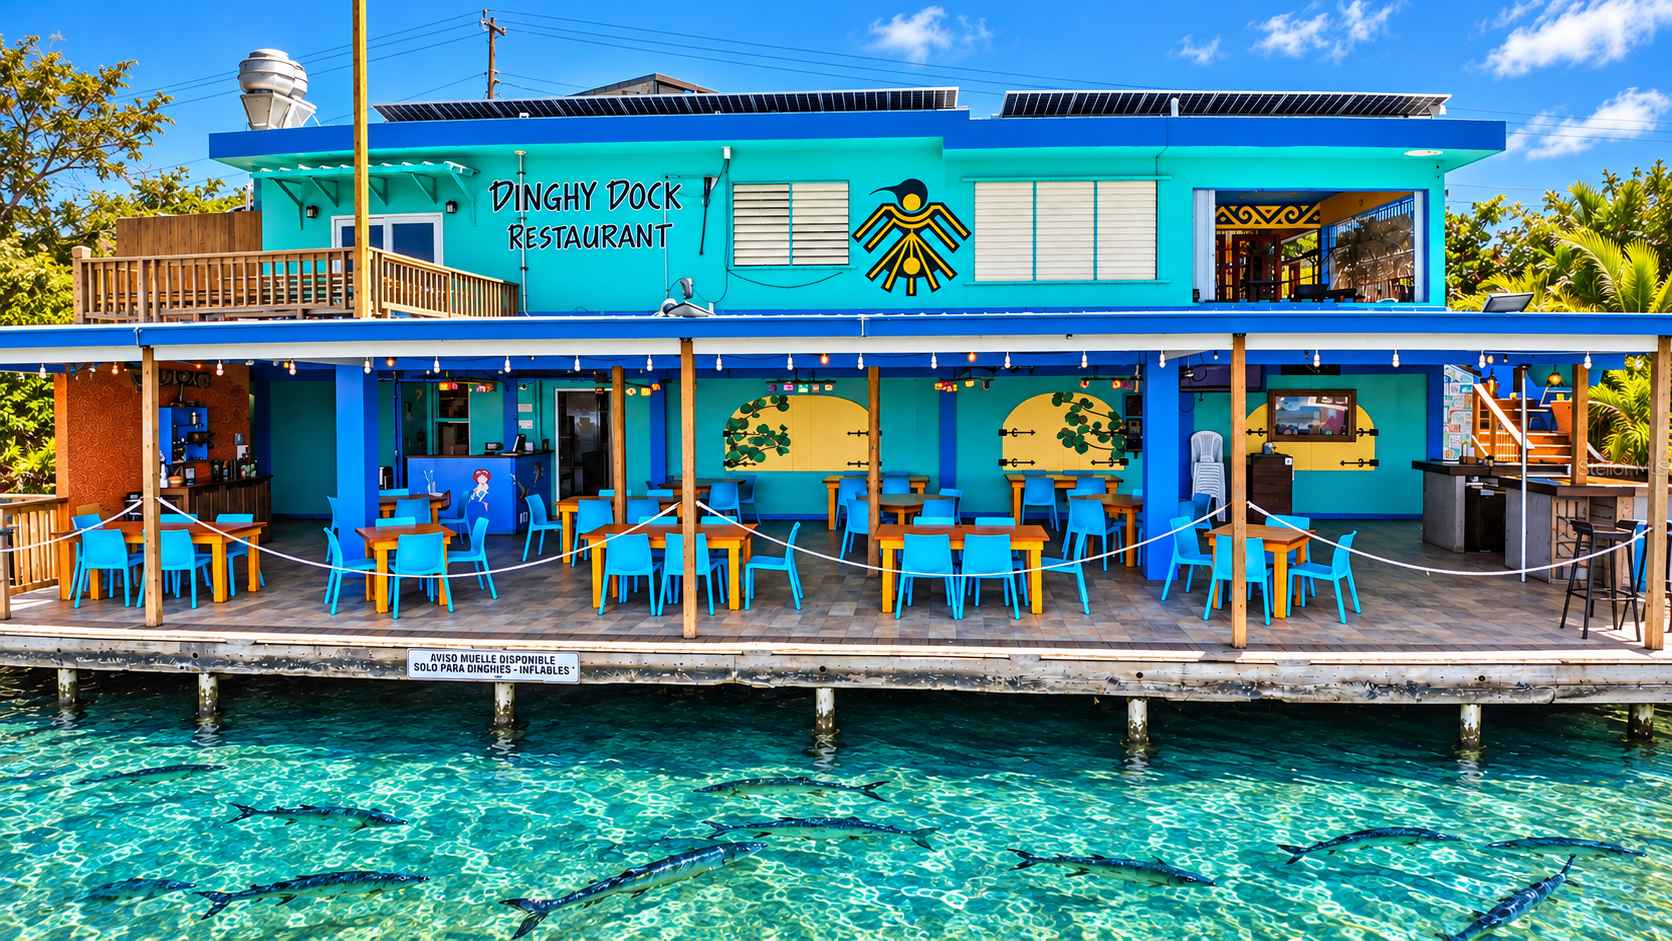
Dinghy Dock in Culebra is a turnkey waterfront restaurant property on Ensenada Honda, offering seating for up to 100 diners, commercial kitchen equipment, a transferable liquor license, retail and vacation rental income, and solar power with backup utilities.
Conclusion
For a Puerto Rico waterfront home, treat property insurance as a due-diligence item well before closing. Confirm flood-zone information, get property-specific quotes, compare wind and hurricane deductibles, review exclusions, and keep reconstruction-cost estimates up to date. These steps support informed decisions when safeguarding assets and evaluating ownership costs.
Christie's International Real Estate Puerto Rico can help buyers identify Puerto Rico waterfront homes for sale and coordinate the real estate due diligence process. A licensed insurance professional should provide insurance advice and bind coverage. Contact us to discuss your property search.
FAQs
Is flood insurance required for a Puerto Rico waterfront home?
Not solely because a home is waterfront. The federal mandatory-purchase rule generally applies when the building is in a Special Flood Hazard Area and secures a government-backed mortgage. A lender may impose additional requirements, and owners without a mortgage may still choose flood coverage based on risk.
Can beachfront property insurance cover loss of rental income?
It can, when the policy includes applicable business-income or loss-of-rents coverage for a covered cause of loss. Beachfront property insurance does not automatically include loss of rental income. This is especially important for owners who lease their properties as vacation homes. This coverage can compensate for lost income when the property is uninhabitable because of covered damage, such as from a natural disaster. Discussing this with your insurance provider to ensure your policy includes this protection and understand the terms is crucial.
How does climate change impact insurance rates and coverage for beachfront properties?
Climate change significantly impacts insurance rates and coverage limits for beachfront properties. As the frequency and severity of weather events like hurricanes, floods, and sea-level rise increase, insurers may adjust rates to reflect the higher risk. Insurance companies may also limit or withdraw coverage in high-risk areas.
Property owners should stay informed about climate trends and insurance market responses and consider additional measures, such as climate resilience upgrades, to reduce risk and costs.
Are there any insurance incentives for eco-friendly and sustainable beachfront properties?
Some insurance companies offer incentives or discounts for eco-friendly and sustainable beachfront properties. These incentives are based on the premise that sustainable features can reduce the risk of damage from environmental factors. For example, properties with energy-efficient construction, solar panels, and natural disaster-resistant features may qualify for lower insurance premiums.
It's worth asking your insurance provider about green incentives, which can support long-term savings and environmental sustainability.