
Real estate can generate cash flow when rent collected exceeds vacancy losses, operating expenses, debt payments, and a reserve for future repairs. Appreciation is a separate potential return: it does not pay a monthly bill unless an owner sells or borrows against the property. This guide shows how to test a Puerto Rico investment property using property-specific income, costs, and rental rules.
Start with the use you intend—long-term lease, short-term stay, or another arrangement—and confirm that the property permits it. Then compare conservative rental assumptions with your financing and ownership costs before treating any projected amount as spendable income.
Key Takeaways
- Rental revenue becomes cash flow only after vacancy, costs, debt service, and reserves.
- Appreciation and a refinance are not the same as recurring rental income.
- Puerto Rico short-term rentals require property-level permission checks and may trigger room-tax duties.
- Act 60 benefits depend on an applicable incentive and do not automatically exempt rental income.
- Compare verified listings and realistic local rental evidence before projecting returns.
Can Real Estate Generate Reliable Cash Flow?

A rental property can produce recurring income, but the amount is variable. Vacancy, repairs, insurance, taxes, association fees, utilities, management, and loan payments can change the result. A property that looks profitable at full occupancy may run at a loss after a major repair or a slow season.
Risk and Reward of Using Leverage in Real Estate
Borrowing reduces the cash needed at purchase, but it creates a payment obligation even when a unit is vacant. Compare loan offers, closing costs, and payment terms using the CFPB loan estimate guide. Test whether cash flow still covers debt service if rent falls or insurance and maintenance costs rise.
Cash Flow and Appreciation Are Different
Net operating income is rental income after vacancy and operating expenses, before financing. Cash flow is what remains after debt service and a realistic reserve for future capital work. Appreciation may increase equity, but a higher estimated value is not cash in hand. A cash-out refinance adds debt and may increase monthly payments.
What Should Investors Check in Puerto Rico?

Image Source: Christie's International Real Estate Puerto Rico
Puerto Rico rental potential depends on the specific property, permitted use, local demand, and total ownership costs. A desirable address alone does not establish occupancy or profit. Review the following before projecting income:
- Tax treatment: Act 60 offers different incentives for different eligible activities and applicants. It is not an automatic reduction of tax on a property's rent. Confirm the applicable decree and treatment of the proposed rental income with a qualified Puerto Rico tax adviser; see Invest Puerto Rico's incentive overview.
- Short-term stays: Confirm municipal rules, deed restrictions, condominium or HOA rules, and insurance coverage for the intended use. The Puerto Rico Tourism Company says rentals of fewer than 90 consecutive days are subject to a 7% room occupancy tax and require innkeeper registration. Do not assume an attractive home may legally be used as a vacation rental.
- Demand and costs: Compare recent, genuinely comparable rentals, expected vacancy, management and turnover costs, property taxes, insurance, utilities, and repair reserves. The tradeoffs between long- and short-term rentals depend on these property-level figures.
How to Estimate Real Estate Cash Flow
Use a monthly model based on documented rent and expenses. Begin with expected gross rent, subtract vacancy and collection loss, then subtract operating expenses to reach net operating income. Subtract loan payments and a reserve for future major repairs to estimate cash available before income taxes. Keep sale proceeds or appreciation outside this monthly calculation.
Understanding the Real Estate Cash Flow Model
For a Puerto Rico property, operating expenses may include property tax, insurance, maintenance, utilities, HOA dues, management, and—where relevant—platform and turnover costs. Ask for actual expense records when available and use comparable quotes where they are not. Model a less favorable occupancy or cost scenario as well as the expected case.
Illustrative Monthly Cash Flow
Line item | Example amount |
|---|---|
Gross rent | $6,000 |
Vacancy and collection loss | −$300 |
Operating expenses | −$2,000 |
Net operating income | $3,700 |
Debt service | −$2,500 |
Capital reserve | −$400 |
Illustrative cash available before income tax | $800 |
These numbers are an arithmetic example, not a Puerto Rico market average or a forecast for any listing. The vacancy rate and reserve must be set for the actual property; a different assumption can change the result materially.
How to Evaluate a Rental Investment

Before purchasing, test the business case with documents rather than a headline yield. Review the intended rental use, comparable rents, lease terms, financing, condition, insurance, taxes, and expected management workload.
Set Clear Financial Goals
Decide whether the priority is current income, long-term equity, personal use, or a mix. A property suited to occasional owner stays may have a different cash-flow profile from a fully leased building. Compare the expected return with the cash required at closing and the risk of a period without rent.
Screen Tenants Consistently
For long-term rentals, use lawful, consistent screening criteria and verify income and rental history where appropriate. A credit score alone does not establish whether an applicant will pay rent, and a fixed score cutoff is not suitable advice for every property. The CFPB's tenant screening guidance explains what reports may contain and applicants' rights when a report affects a rental decision.
Conduct Local Market Research
Compare recent rentals with the same location, property type, size, condition, and permitted use. Ask how long comparable units stayed vacant and whether advertised rates turned into actual bookings or signed leases. Check competing supply and seasonal demand instead of assuming that all of San Juan, Dorado, or another municipality performs alike.
Secure Financing and Plan for Repairs
Request loan terms for the specific borrower and property type, then include the full payment and closing costs in the model. Inspect the property and budget for near-term work and future replacement of roofs, air-conditioning equipment, appliances, and other major components. Revisit the numbers whenever financing, taxes, insurance, or the intended rental use changes.
Puerto Rico Luxury Properties for Sale
These current listings show different property types and locations to investigate, including a building with existing rental use. None has a verified projected yield here, and rental permission or future income should be confirmed independently. Explore luxury properties for sale and compare each candidate with the same cash-flow model.

2073 Cacique St, San Juan, PR 00911
The active listing describes a 3,221-square-foot residence with six bedrooms, eight bathrooms, and a pool near the beach. Verify permitted rental use and property-specific expenses before modeling income.
934 Isla Norte, Dorado, PR 00646
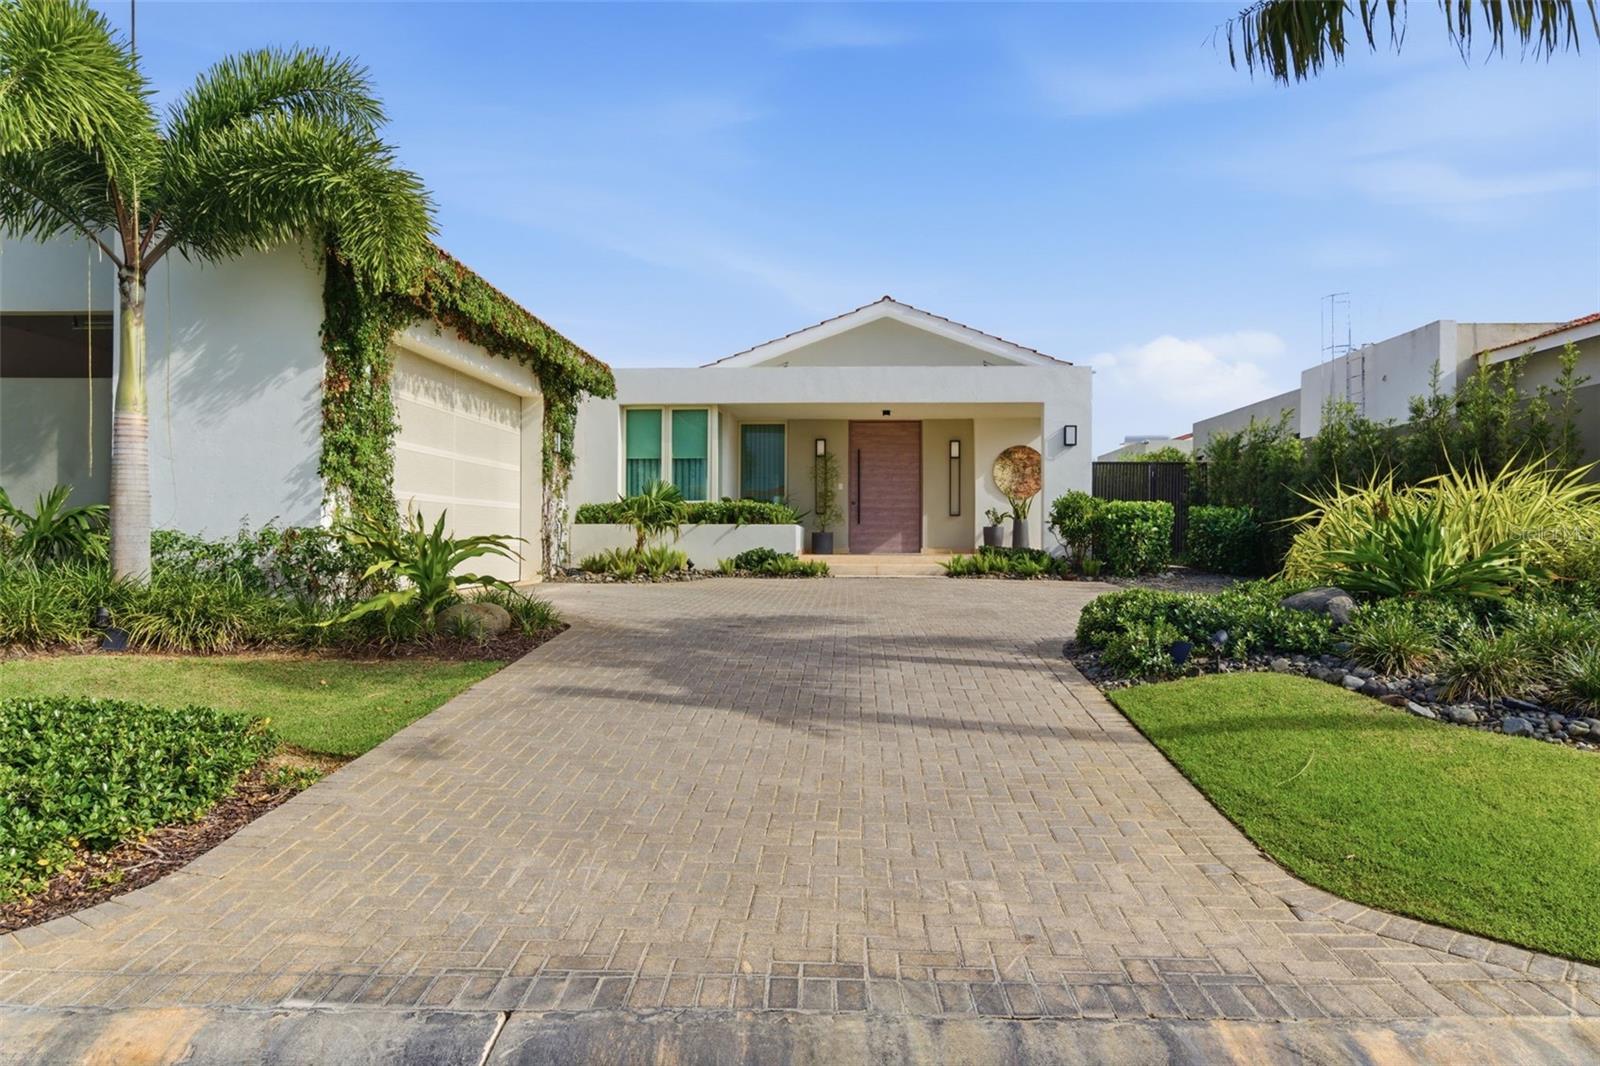
This active Sabanera Dorado listing offers four bedrooms, approximately 5,100 square feet of interior space, and a private pool. Confirm community rental rules, carrying costs, and comparable rents before assessing cash flow.

266 Calle de San Francisco, Old San Juan
The for-sale listing describes five full-floor lofts above a ground-level commercial space and reports a history of long-term rental income. Obtain leases, expense records, and use approvals before relying on that history or considering any change of use.
513 Tintillo Hill Estates, Guaynabo, PR 00966
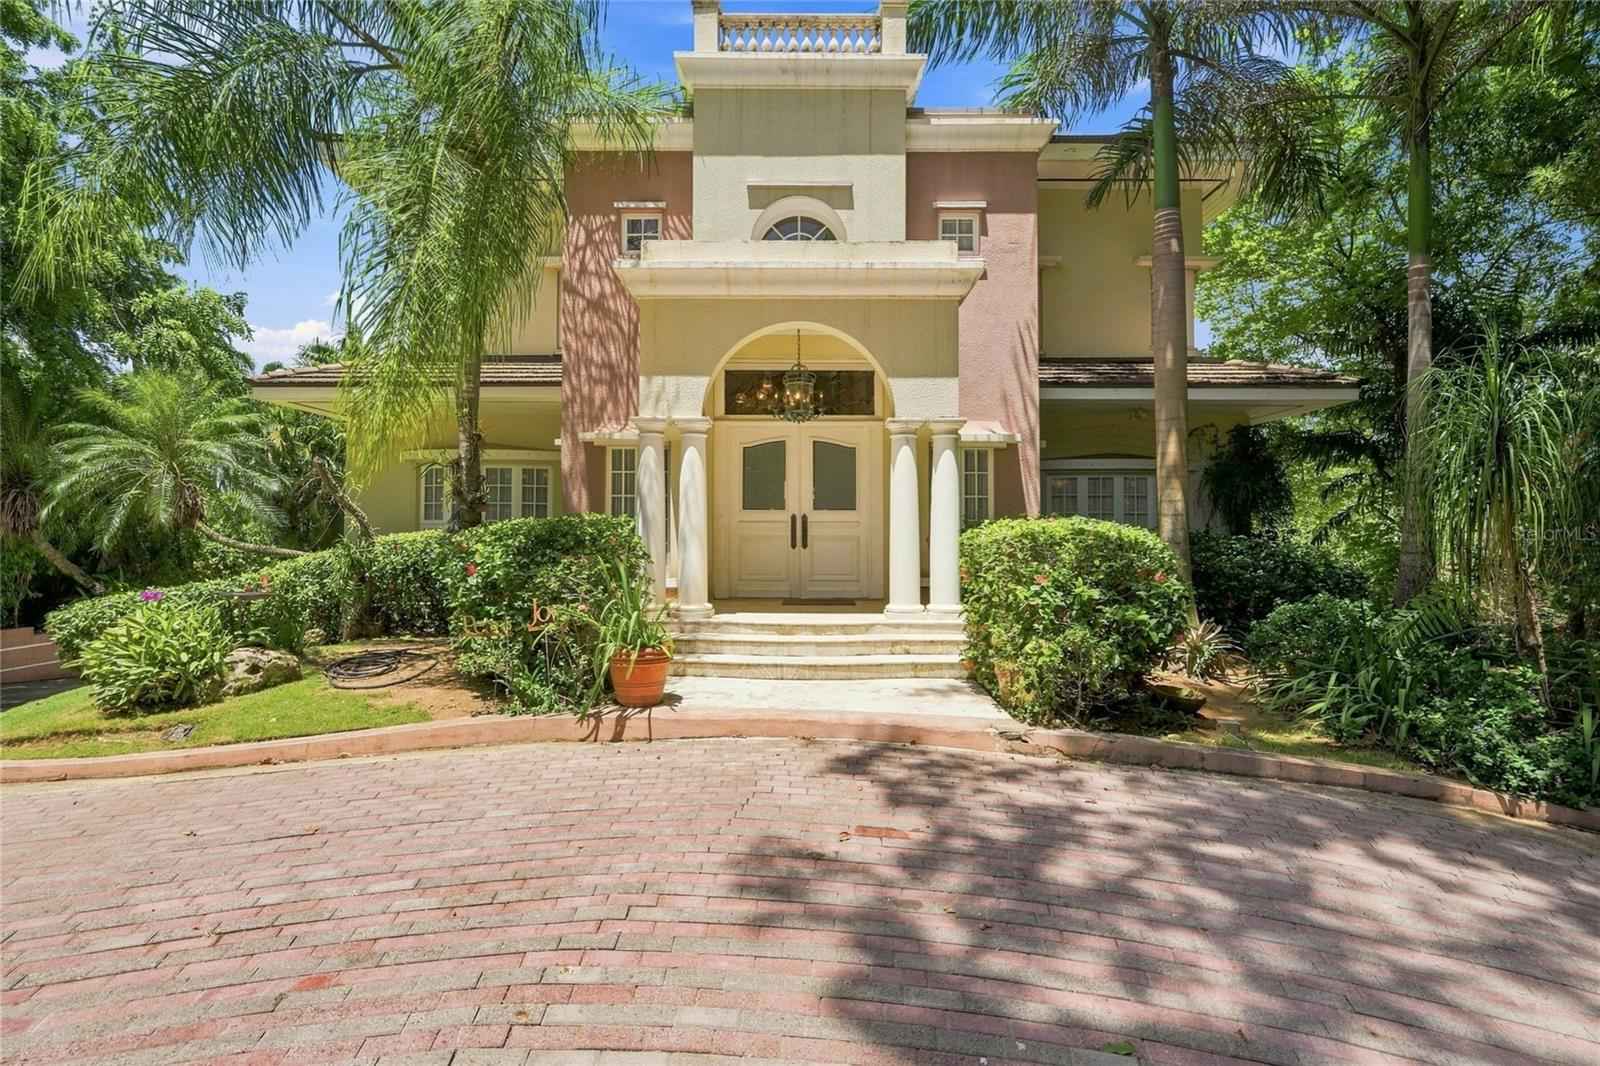
This active listing describes a five-bedroom residence with a pool, tennis court, and views toward San Juan Bay. Verify the lot area and all rental restrictions directly, since the listing's narrative and structured lot-size field differ.
Conclusion
Real estate can generate cash flow when the actual rent exceeds vacancy, operating costs, financing, and a prudent reserve. In Puerto Rico, tax treatment and rental permission must be checked for the particular property and intended use. Conservative assumptions and verified documents make an investment decision more useful than promises of seamless income.
Christie's International Real Estate Puerto Rico is here to guide readers who want to rent, buy, or sell luxury property in Puerto Rico. Explore Puerto Rico luxury properties and contact the team to discuss properties that fit your goals.
FAQs
What type of real estate produces the most cash flow?
No property type consistently wins. Compare net income after vacancy and operating costs, debt service, required improvements, and reserves. A building with several tenants can spread vacancy risk, but it can also have higher maintenance and management costs.
What is cash-on-cash return?
Cash-on-cash return compares annual cash flow before income taxes with the cash invested, such as down payment, closing costs, and initial work. For example, $12,000 annual cash flow on $300,000 cash invested equals 4%; this is an illustration, not a forecast. Define cash flow consistently and include a reserve rather than treating all receipts as profit.
How can a cash-flow forecast improve?
Use actual leases and expenses where possible, compare recent local rentals, and price financing and insurance for the specific property. Test lower occupancy, slower collections, and larger repairs. Update the forecast when the property, permitted use, loan terms, or market evidence changes.
Related Articles
These guides cover the rental, tax, and ownership choices behind a Puerto Rico cash-flow estimate.


