Can you move to Puerto Rico and benefit from Act 60? Relocating, qualifying for an Individual Resident Investor decree, and establishing federal tax residency are separate questions. Your income sources, application timing, housing plans, and ongoing costs determine whether the program fits your circumstances.
This guide explains the enacted 2026 changes and the real estate decisions involved. A property purchase alone does not establish tax residency or guarantee an exemption.
Key Takeaways
- Separate Puerto Rico incentives from U.S. federal tax treatment.
- Check the application-date rules before comparing the two investor regimes.
- Plan for a principal residence, annual compliance costs, and documented residency.
- Evaluate the move around your family and business needs as well as potential tax savings.
Who Act 60 Helps After the 2026 Changes
The Individual Resident Investor program concerns qualifying investment income. Its value depends on what you earn and where that income is sourced, rather than simply your wealth or the price of your home.
2026 and 2027 Application Rules
Law 38-2026, as enacted distinguishes applications filed on or before December 31, 2026 from those filed beginning January 1, 2027:
Application timing | Qualifying Puerto Rico tax treatment | Statutory benefit horizon |
|---|---|---|
On or before December 31, 2026 | 0% on qualifying interest, dividends, and post-residency appreciation | Before January 1, 2036 |
January 1, 2027 onward | 4% on those qualifying categories, subject to more favorable statutory exceptions | Before January 1, 2056 |
These are Puerto Rico rates, not a promise of zero or 4% total U.S. tax. Pre-residency appreciation has separate rules. Post-2026 applicants must demonstrate at least six years of nonresidency before moving; this is an eligibility test, not an asset-gain look-back rule.
Existing Decree Holders
Existing rights and obligations are preserved. The law does not automatically extend existing 0% treatment through 2055. Eligible holders may request a modification into the amended regime; review the resulting terms before making that election.
Tax Outcomes by Investor Profile

Compare your expected tax position with the full cost of relocating, maintaining a home, and complying with the decree. A lower headline rate does not establish that a move will save money.
High-Value Investment Managers
Separate investment returns, carried interest, management fees, and compensation in your analysis. They should not be treated as interchangeable income categories. Obtain a review of each stream before assuming it receives individual investor treatment.
Active Traders and Crypto Investors
Record acquisition dates, cost basis, and asset values at the move. A sale after relocation does not make all earlier appreciation eligible for favorable treatment. Trading frequency alone does not establish eligibility, and there is no reliable basis for promising that tax savings will cover relocation costs in the first year.
Service Business Owners
The export-services provisions are a separate part of Act 60. Invest Puerto Rico’s overview of business incentives describes a 4% rate on eligible income. Serving customers outside Puerto Rico does not by itself establish eligibility; review the activity, operations, income sourcing, and applicable business decree separately from your personal investor application.
Traditional Employees and Location-Dependent Businesses
An Individual Resident Investor decree does not turn ordinary salary into exempt investment income. If your work requires a mainland presence, map your travel and work arrangements before relying on Puerto Rico residency. A business or employment schedule can affect the practical feasibility of the move without automatically resolving your tax status.
Practical Relocation Requirements and Constraints
Federal Residency: More Than Counting 183 Days
Under IRS Publication 570’s bona fide residency rules, 183 days in Puerto Rico is one way to satisfy the presence test; alternatives exist. You must also satisfy the tax-home and closer-connection tests. Special rules can apply in the year of a move. A decree or a home purchase does not replace these federal tests.
- Keep a travel calendar supported by tickets and other records.
- Review where your principal work activity occurs and where your personal and economic connections lie.
- Plan your move-year tax filings before assuming a full year of favorable treatment.
Principal Residence Purchase and Registry Requirements
Under Act 60’s principal-residence and reporting provisions, covered investors must purchase a Puerto Rico principal residence from an unrelated seller within two years after obtaining the decree and maintain qualifying ownership during its term. This is not an accelerated deadline tied to December 31, 2026. For applications from 2027, evidence may show title registered or pending registration in the investor’s name, jointly with a spouse, or in a qualifying statutory trust.
Do not assume a vacation home, rental-only property, or company-owned purchase satisfies this requirement. Confirm the ownership structure with Puerto Rico counsel before signing. The cited purchase provision does not impose a $500,000 or $1 million minimum price.
- Choose a location that works for your daily routine, family, and travel plans.
- Review title, permitted use, financing, insurance, and any condominium or HOA restrictions before committing.
- Coordinate closing and Registry documentation with your notary and retain evidence for the annual report.
- For a multi-unit home, have the intended personal and rental uses assessed before treating it as your qualifying residence.
Annual Costs and Family Considerations
Act 60 requires a minimum $10,000 annual donation beginning with the second taxable year after the decree is issued. A separate $5,000 annual report fee is not a charitable contribution. Check recipient and allocation rules, reporting instructions, and your decree; older Act 22 terms may differ.
Budget beyond these obligations: moving expenses, housing, utilities, insurance, professional fees, and any business compliance costs. Compare actual quotes with a tax projection instead of relying on a generic luxury-home price range. Spouses and children need their own assessment of tax status, education, healthcare, and work arrangements.
For a practical neighborhood starting point, see the guide to family life in Santurce. Visit prospective neighborhoods and confirm the services that matter to your household.
Risk Factors and Compliance Challenges
The main planning risk is assuming that a Puerto Rico decree settles every tax question. Keep local decree compliance and federal residency and sourcing analysis in separate, coordinated records.
Income Sourcing and Reporting
IRS rules determine whether income is Puerto Rico-sourced for federal purposes. Investment and service income require different sourcing analyses, and assets held before relocation can raise special issues. Review transactions before executing them, rather than assuming a Puerto Rico address changes their treatment.
Ongoing Decree Compliance
Maintain a calendar for reporting, contributions, and property obligations, with supporting receipts and records. If circumstances change, review the decree before moving away, selling the qualifying residence, or changing ownership. The outcome of a compliance failure depends on the applicable law, decree, and facts; it should not be described as automatic retroactive loss of every benefit.
Planning question | Records to review |
|---|---|
Residency | Travel records, home use, work location, and personal connections |
Investment income | Acquisition dates, basis, valuations, and transaction records |
Property compliance | Deed, ownership structure, Registry evidence, and principal-residence use |
Annual obligations | Reports, payment confirmations, and qualifying donation receipts |
Luxury Properties and Houses for Sale
Christie’s International Real Estate Puerto Rico can help you explore homes for sale in Puerto Rico as part of your relocation planning. The following property examples offer different locations and living arrangements. Listing details and availability can change; none is represented here as automatically qualifying for Act 60.
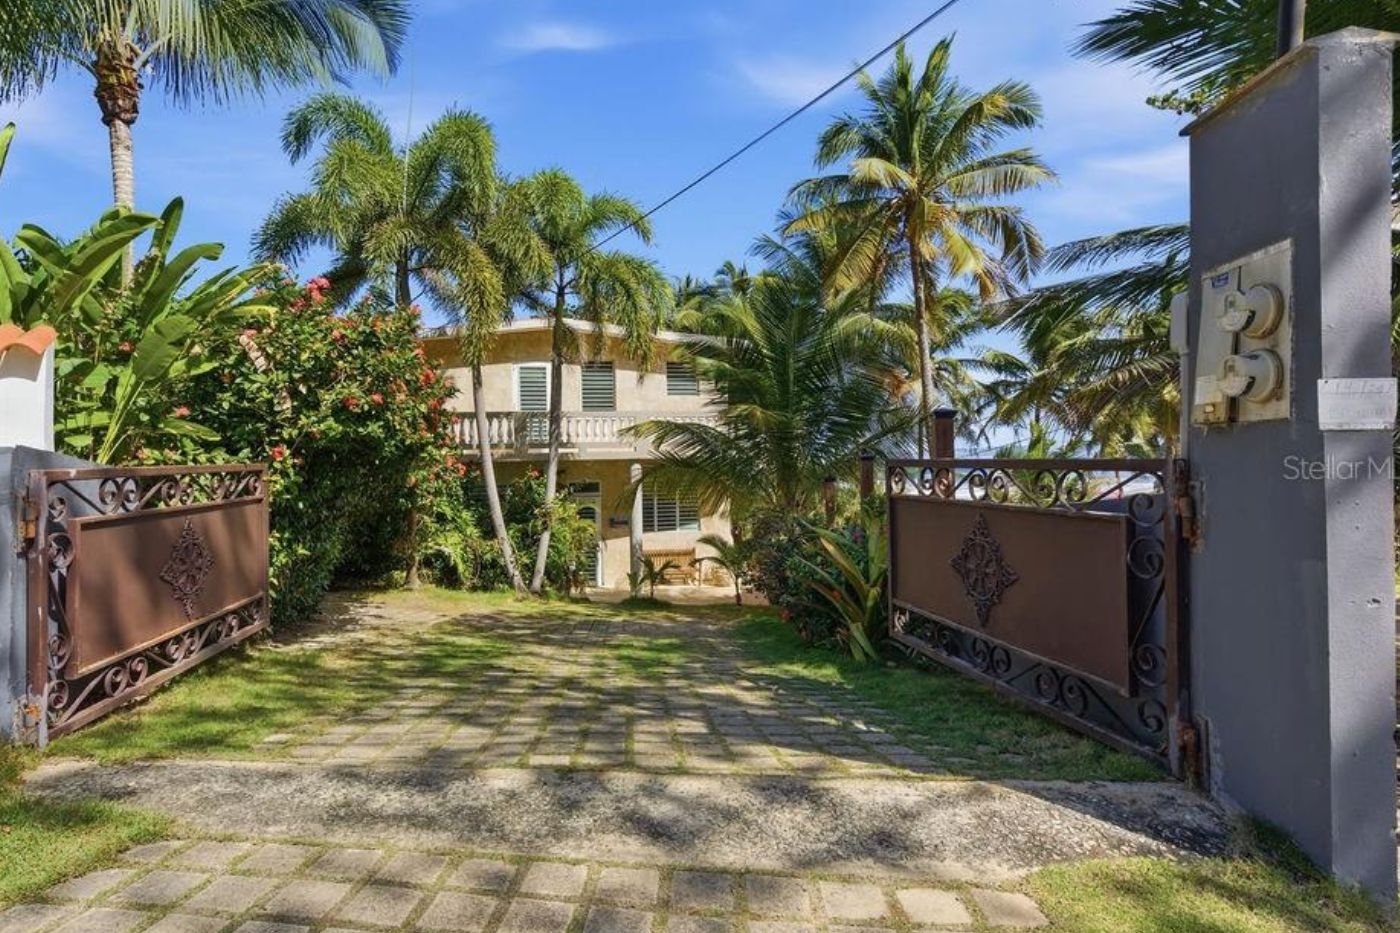
26 BARRIO PUNTAS SANDY BEACH, RINCÓN PR, 00677
This Sandy Beach multi-unit residence in Rincón is listed with direct beach access, ocean views, and solar features. Its separate units make the intended principal-residence and rental arrangements a useful point for legal and tax review.
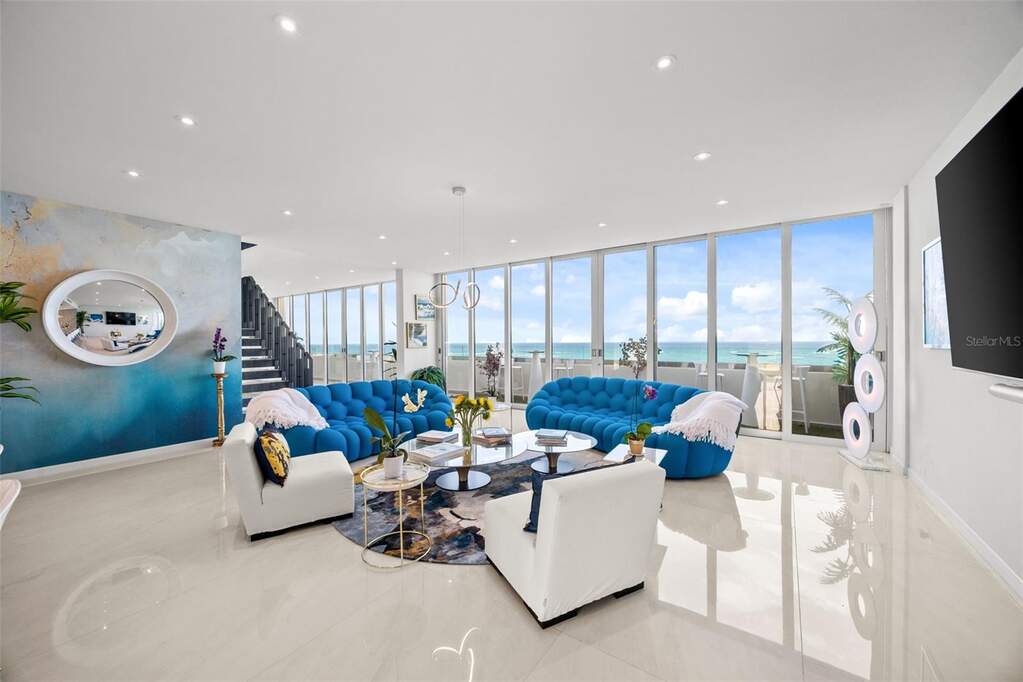
3307 Ave Isla Verde Unit: PH, Carolina, PR 00979, Puerto Rico
This furnished Isla Verde penthouse is listed with expansive terraces and ocean, lagoon, city, and mountain views. Review the condominium documents and ongoing ownership costs alongside its suitability for everyday living.
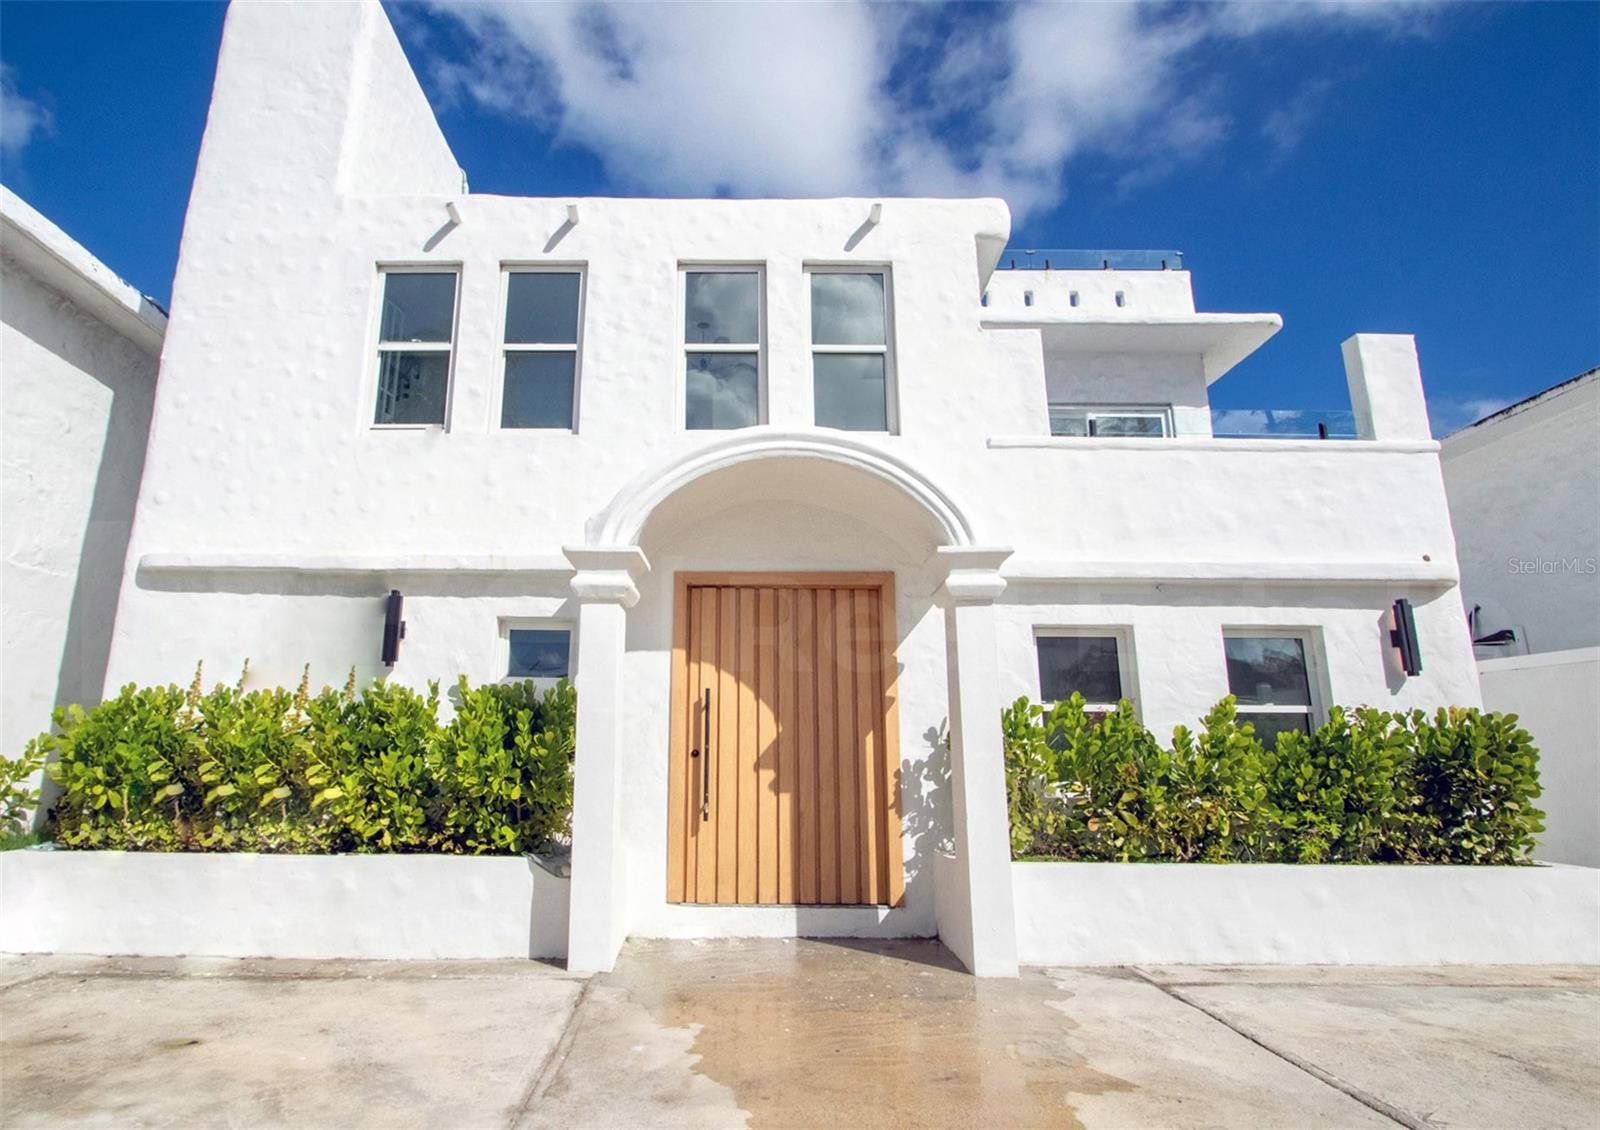
2071 CACIQUE ST SAN JUAN PR, 00911
This remodeled San Juan residence is listed with six bedrooms, six bathrooms, a guest suite, and a poolside patio. Consider how its layout and location fit your household’s daily needs.

Guavate 184 Bo, Cayey, PR 00736
Guavate 184 Bo is presented as a furnished two-bedroom lakefront retreat in Cayey with mountain views and outdoor living space. Any rental, tourism, or development plans require separate due diligence; they are not assured by the listing or by an investor decree.
Conclusion
Act 60 is worth evaluating when the income rules, ongoing costs, and practical demands of residency align with your plans. Compare the applicable regime with your current tax position, and choose a home for how you intend to live in Puerto Rico. This guide provides general information, not an individual eligibility determination.
Explore Christie’s Puerto Rico property listings and contact the team to discuss locations, home requirements, and a realistic purchase timeline. Coordinate the tax and ownership decisions with your own Puerto Rico and U.S. advisers.
FAQs
Can you move to Puerto Rico without Act 60?
Yes. U.S. citizens can relocate without an Act 60 decree. Act 60 is a tax-incentive program, not a visa or immigration status. Non-U.S. citizens must meet applicable U.S. immigration requirements; the Puerto Rico Department of State explains the federal immigration framework.
Must the decree be approved by December 31, 2026?
The statutory distinction is based on application submission, not decree approval by that date. Keep evidence of filing and confirm the current submission requirements with DDEC. Filing alone does not guarantee approval or tax eligibility.
How do federal U.S. taxes interact with Act 60 benefits?
Puerto Rico exemptions do not automatically remove federal obligations. IRS Topic 901 explains the treatment of Puerto Rico-source income and when a federal return may still be required. U.S.-source income generally remains subject to federal taxation even for a bona fide Puerto Rico resident.
What documentation should I maintain?
Keep travel records, evidence of actual home use, business contracts and invoices, investment records, the decree and any amendments, property closing and Registry documents, annual reports, and donation receipts. Retaining documents supports an assessment; no single utility bill or travel log establishes eligibility by itself.
Is Act 22 the same as Act 60?
Act 22 was the earlier individual-investor incentive law. Act 60 incorporated the investor program into the broader Incentives Code. Older decrees retain their applicable terms, so use your actual decree and amendments rather than assuming every participant has identical obligations.
Is the export-services benefit automatic for entrepreneurs?
No. It is a separate incentive requiring qualifying activity and compliance. Do not apply an export-business rate or property-tax exemption to all personal income or to a residence simply because its owner holds an individual-investor decree.