Property owners in Puerto Rico must report all rental income to Hacienda, the island's treasury department, regardless of property type or rental duration. Reporting requirements vary significantly between short-term rentals (STRs) and long-term rentals (LTRs). Each category faces different tax rates, deductions, and compliance obligations.
Understanding these distinctions helps property owners avoid costly penalties and maximize their investment returns.
Key Takeaways
- Rental income from Puerto Rico property generally must be reported to Hacienda using the return and schedules that apply to the owner’s residency and ownership structure.
- Short-term rentals of less than 90 consecutive days require Puerto Rico Tourism Company innkeeper registration and collection of the 7% room occupancy tax.
- Meticulous digital record-keeping of expenses is the best defense against Hacienda audits and compliance errors.
- Eligible expenses and depreciation may reduce taxable rental income, but the treatment depends on the taxpayer, property use, and applicable Puerto Rico and federal rules.
Essential Reporting Requirements for All Rental Properties
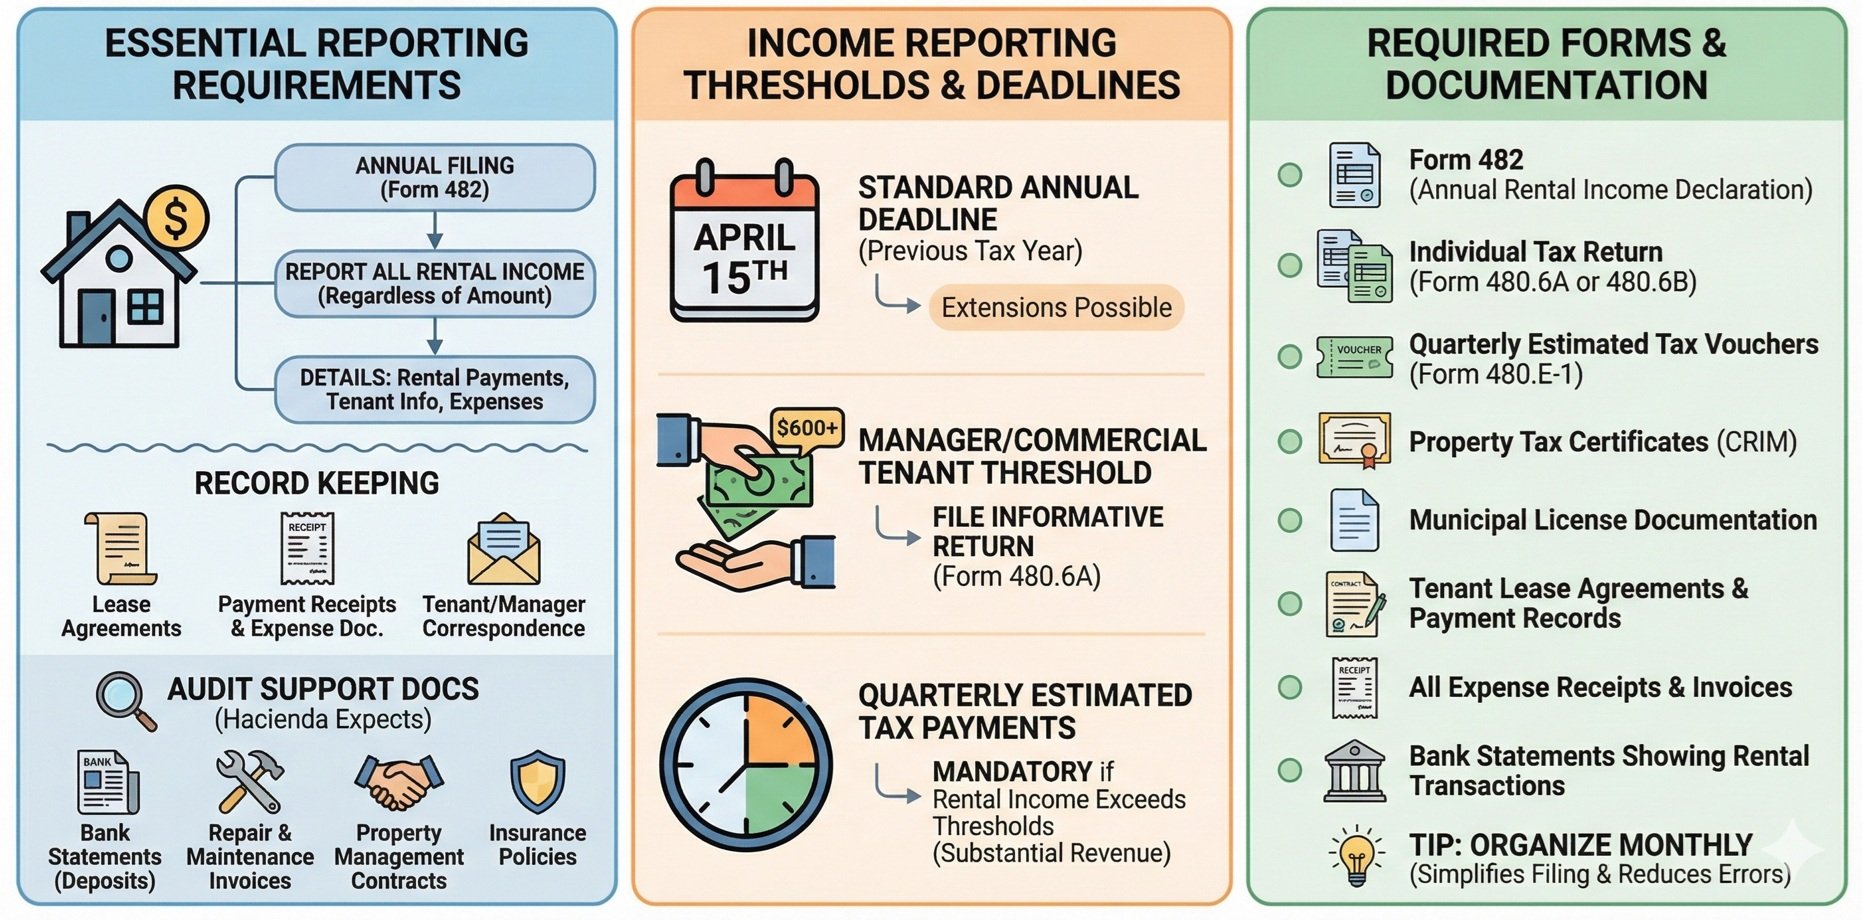
Individual owners generally report Puerto Rico rental activity through Form 482 and Schedule N. The precise return, schedules, withholding rules, and filing obligations depend on residency, ownership structure, and the facts of the rental activity.
You also need to maintain complete records including lease agreements, payment receipts, expense documentation, and any correspondence with tenants or property managers.
The required documentation includes bank statements showing rental deposits, invoices for repairs and maintenance, property management contracts, and insurance policies. Hacienda expects these documents to support all income and deduction claims during potential audits.
Income Reporting Thresholds and Deadlines
Property owners must report all rental income on their individual tax returns, regardless of the total amount earned.
- A person engaged in a trade or business may need to issue Form 480.6A when rent or other reportable payments not subject to withholding total $500 or more. This is an informative return issued by the payer, not the property owner’s individual income tax return.
- Individual income tax returns are generally due on April 15 following the close of a calendar tax year, subject to current Hacienda guidance and available extensions.
Estimated income-tax payments may be required depending on expected liability and the owner’s broader tax situation; a Puerto Rico tax professional should confirm the applicable schedule.
Required Forms and Documentation
- Form 482 and Schedule N for an individual owner, when applicable
- Forms 480.6A or 480.6B received from business payers, when applicable
- Estimated-tax payment records, when required
- Property tax certificates (CRIM)
- Municipal license documentation
- Tenant lease agreements and payment records
- All expense receipts and invoices
- Bank statements showing rental transactions
Organizing these documents monthly rather than waiting until tax season simplifies filing and helps the owner support income and expense records.
Short-Term Rental Tax Treatment and Compliance
Short-term rentals of less than 90 consecutive days must register with the Puerto Rico Tourism Company as an innkeeper and obtain an innkeeper identification number. Rental income-tax treatment remains separate and depends on the owner’s residency, entity structure, deductions, and other facts.
Under Puerto Rico’s Room Occupancy Tax rules, covered short-term rentals must collect a 7% tax on the room rate and submit a monthly declaration to the Puerto Rico Tourism Company by the 10th day of the following month.
Licensing and Registration Requirements
Owners should complete Puerto Rico Tourism Company innkeeper registration and verify any municipal, condominium, zoning, insurance, or use restrictions that apply to the specific property before accepting bookings.
Booking platforms such as Airbnb may collect or remit certain taxes, but the owner should keep platform statements and confirm that registration and filing records are complete.
Monthly Room Tax and Income-Tax Obligations
- File the Room Occupancy Tax monthly declaration by the 10th day of the following month
- Remit the 7% room occupancy tax collected from guests
- Track gross receipts, platform collections, refunds, and taxable room charges
- Make estimated income-tax payments when required for the owner’s situation
- Maintain detailed booking, payment, and filing records
Long-Term Rental Income Strategies
Long-term rentals generally do not fall under the Tourism Company’s room occupancy tax when the stay is 90 consecutive days or more. Owners still need to report rental income, keep supporting records, and verify any municipal, condominium, insurance, or business requirements that apply to the property.
A later sale is a separate tax event. Capital-gain, depreciation-recapture, residency, and sourcing rules should be reviewed for the owner’s specific circumstances before a transaction.
Deductible Expenses for Long-Term Rentals
- Mortgage interest payments
- Property management fees
- Routine maintenance and repairs
- Property insurance premiums
- Municipal property taxes and other eligible taxes
- Utilities paid by the owner
- Professional services (legal, accounting, real estate)
- Advertising and marketing costs
- Travel expenses for property management
Depreciation Benefits
Depreciation may be available for eligible rental buildings and capital improvements, but the recovery period and method can differ between Puerto Rico and federal reporting. Land is not depreciable, and personal use, entity ownership, and prior depreciation can affect the calculation.
Ask a Puerto Rico tax professional to prepare or review the depreciation schedule rather than applying a federal recovery period automatically.
Rental Tax and Licensing Requirements by Property Type
Understanding these distinctions helps property owners choose the most tax-efficient rental strategy for their specific situation and investment goals.
Rental Type | Tourism Company Rule | Filing Frequency | Room Tax |
|---|---|---|---|
Short-Term (less than 90 days) | Register as an innkeeper | Monthly room-tax declaration | 7% of the room rate |
Long-Term (90 days or more) | Generally outside the room-tax program | Income-tax reporting as applicable | No Tourism Company room tax |
Maximizing Deductions and Tax Benefits
Puerto Rico property owners can significantly reduce their tax burden through strategic expense planning and proper documentation. The key lies in understanding which expenses qualify for immediate deductions and which require capitalization and depreciation over time. Professional property management, routine maintenance, and operational costs generally qualify for immediate deduction, while major improvements and renovations must be depreciated.
Owners can lose otherwise supportable deductions when they do not maintain invoices, receipts, proof of payment, and a clear allocation between rental and personal use.
Immediate vs. Capital Improvements
Repairs that maintain the property's current condition qualify as immediate deductions, while improvements that add value or extend useful life must be capitalized. Replacing a broken air conditioning unit represents a deductible repair, but installing central air conditioning in a property that previously lacked it constitutes a capital improvement.
The distinction significantly affects cash flow, as immediate deductions reduce current-year taxes while capital improvements provide benefits over many years through depreciation.
Professional Service Deductions
- Property management company fees
- Real estate attorney consultations
- Accounting and tax preparation services
- Property inspection and appraisal costs
- Insurance agent commissions
- Cleaning and maintenance services
- Landscaping and pool maintenance
Avoiding Common Compliance Mistakes

Property owners frequently face penalties for preventable errors in rental income reporting and tax compliance. The most common mistakes involve inadequate record-keeping, missed filing deadlines, and incorrect classification of expenses or rental types. Failure to register, file required returns, remit collected room tax, or support deductions can lead to tax, interest, and penalty exposure.
Simple organizational systems prevent most compliance issues and significantly reduce audit risk.
Critical Mistake Prevention Checklist
- License Verification: Confirm all required licenses remain current and properly displayed
- Tax Collection: Collect and remit all applicable guest taxes for short-term rentals
- Income Reporting: Report all rental income, including cash payments and barter arrangements
- Expense Documentation: Maintain receipts and invoices for all claimed deductions
- Filing Deadlines: Track monthly room-tax and applicable income-tax deadlines
- Bank Account Separation: Use dedicated accounts for rental income and expenses
- Professional Guidance: Consult tax professionals for complex situations or significant income levels
- Municipal Compliance: Stay current with local rental regulations and permit requirements
- Guest Registration: Maintain accurate guest records for tourism reporting requirements
- Insurance Coverage: Ensure adequate coverage for rental activities and liability exposure
Record-Keeping Best Practices
Digital record-keeping systems provide the most reliable approach to tax compliance, allowing easy retrieval during audits and simplified annual filing preparation. Cloud-based accounting software can automatically categorize expenses and generate required reports for Hacienda submissions.
Physical backup copies of critical documents should be maintained separately from digital files to ensure continuity during system failures or data corruption events.
Working with Tax Professionals and Hacienda
Complex rental income situations benefit significantly from professional tax guidance, particularly when properties generate substantial income or involve multiple rental types. Qualified Puerto Rico tax professionals understand local regulations, recent law changes, and audit procedures that general practitioners might miss. Professional advice can help owners classify income and expenses correctly and avoid preventable filing errors.
Professional representation can be valuable when Hacienda requests records or when ownership, residency, withholding, or mixed-use questions are complex.
When to Seek Professional Help
Property owners should consider professional assistance when operating both short- and long-term rentals, renting through an entity, allocating mixed personal and rental use, dealing with nonresident withholding, or responding to a Hacienda inquiry.
Do not assume an Act 60 decree exempts ordinary rental income. The decree’s text, the nature of the income, and the owner’s residency and entity structure must be reviewed individually.
Audit Preparation and Response
- Organize all requested documents promptly and completely
- Provide only information specifically requested by auditors
- Maintain professional communication throughout the process
- Consider professional representation for complex cases
- Document all interactions and correspondence with Hacienda
- Understand appeal rights and procedures if disagreements arise
Luxury Properties and Houses for Sale in Puerto Rico
Luxury properties and houses for sale in Puerto Rico can serve different ownership goals, including personal use, long-term leasing, or short-term rental where permitted. Christie's International Real Estate Puerto Rico represents properties in several markets that may be relevant to buyers evaluating rental potential; availability, rules, expenses, and projected income should be verified for each listing.
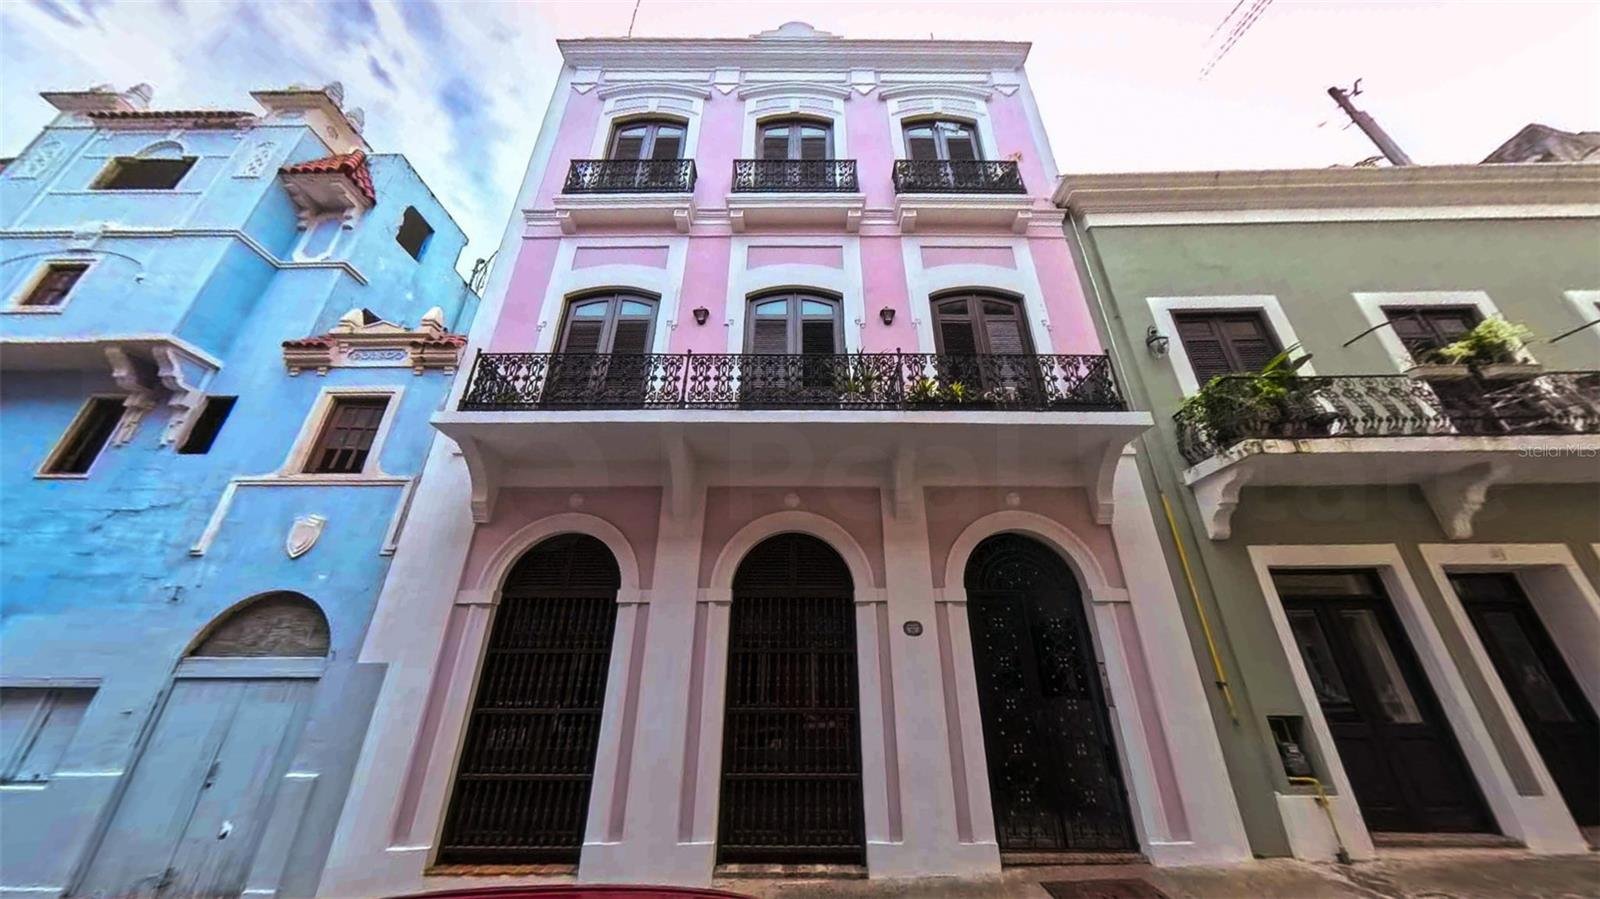
152 SAN JUSTO ST SAN JUAN PR, 00901
This 10-unit residential building in Old San Juan offers approximately 10,800 square feet. Its multi-unit configuration may be relevant to buyers evaluating rental operations, subject to current availability and due diligence.
425 SOL ST #Penthouse SAN JUAN PR, 00901
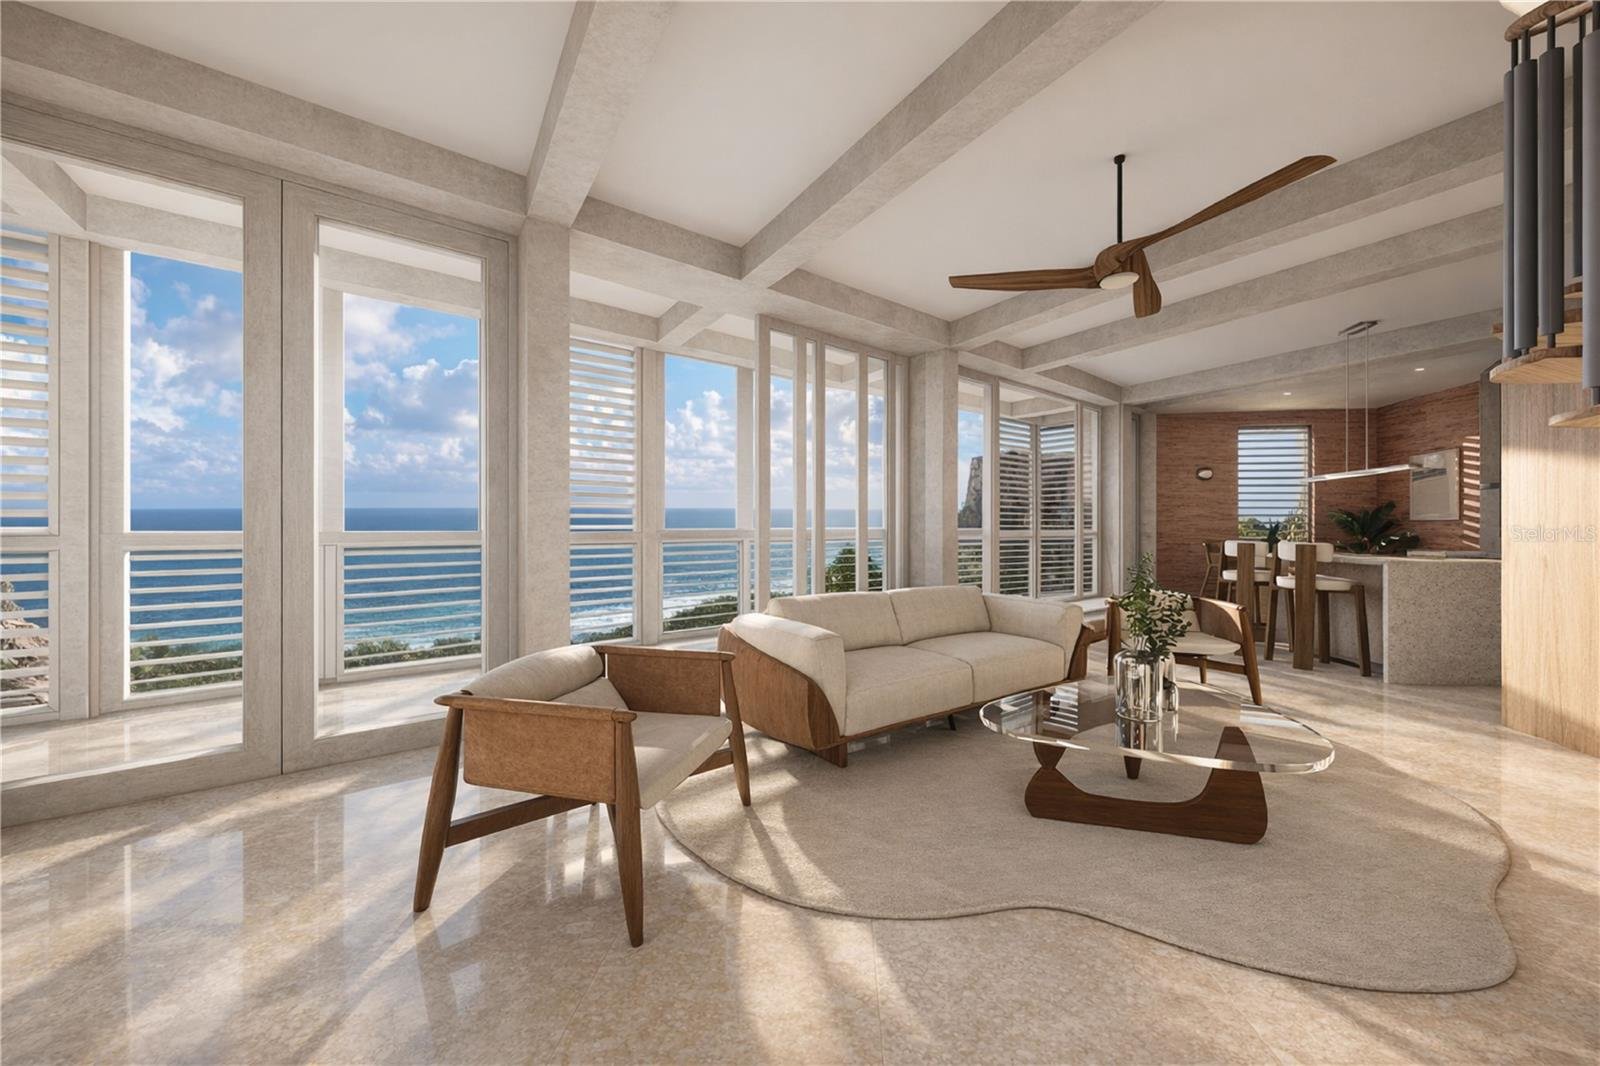
La Victoria is presented as a two-level penthouse in Old San Juan with three bedrooms, ocean and city views, and access to a rooftop pool. Buyers should confirm construction status, availability, and any rental restrictions directly from the listing team.
SHELL CASTLE CLUB #46 HUMACAO PR, 00791
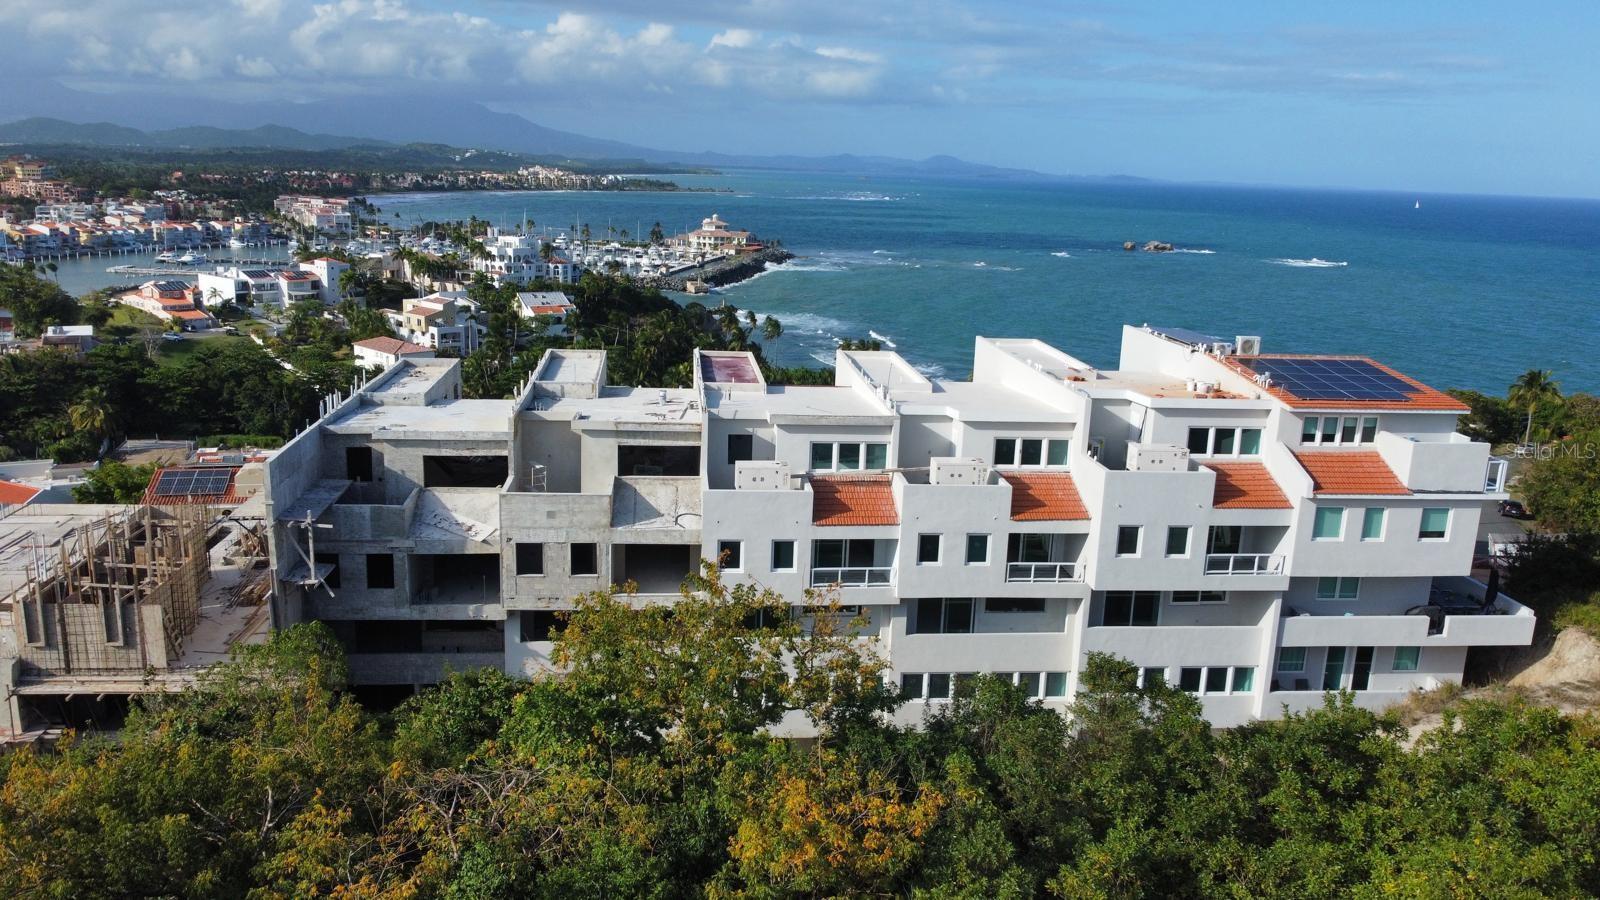
Breeze Point 46 is a five-level residence in Palmas del Mar with flexible living spaces, a private apartment, rooftop terrace, pool, and solar power. Its layout may suit mixed personal and rental use where community rules allow it.
5R MOUNT RESACA BARRIO FLAMENCO CULEBRA PR, 00775
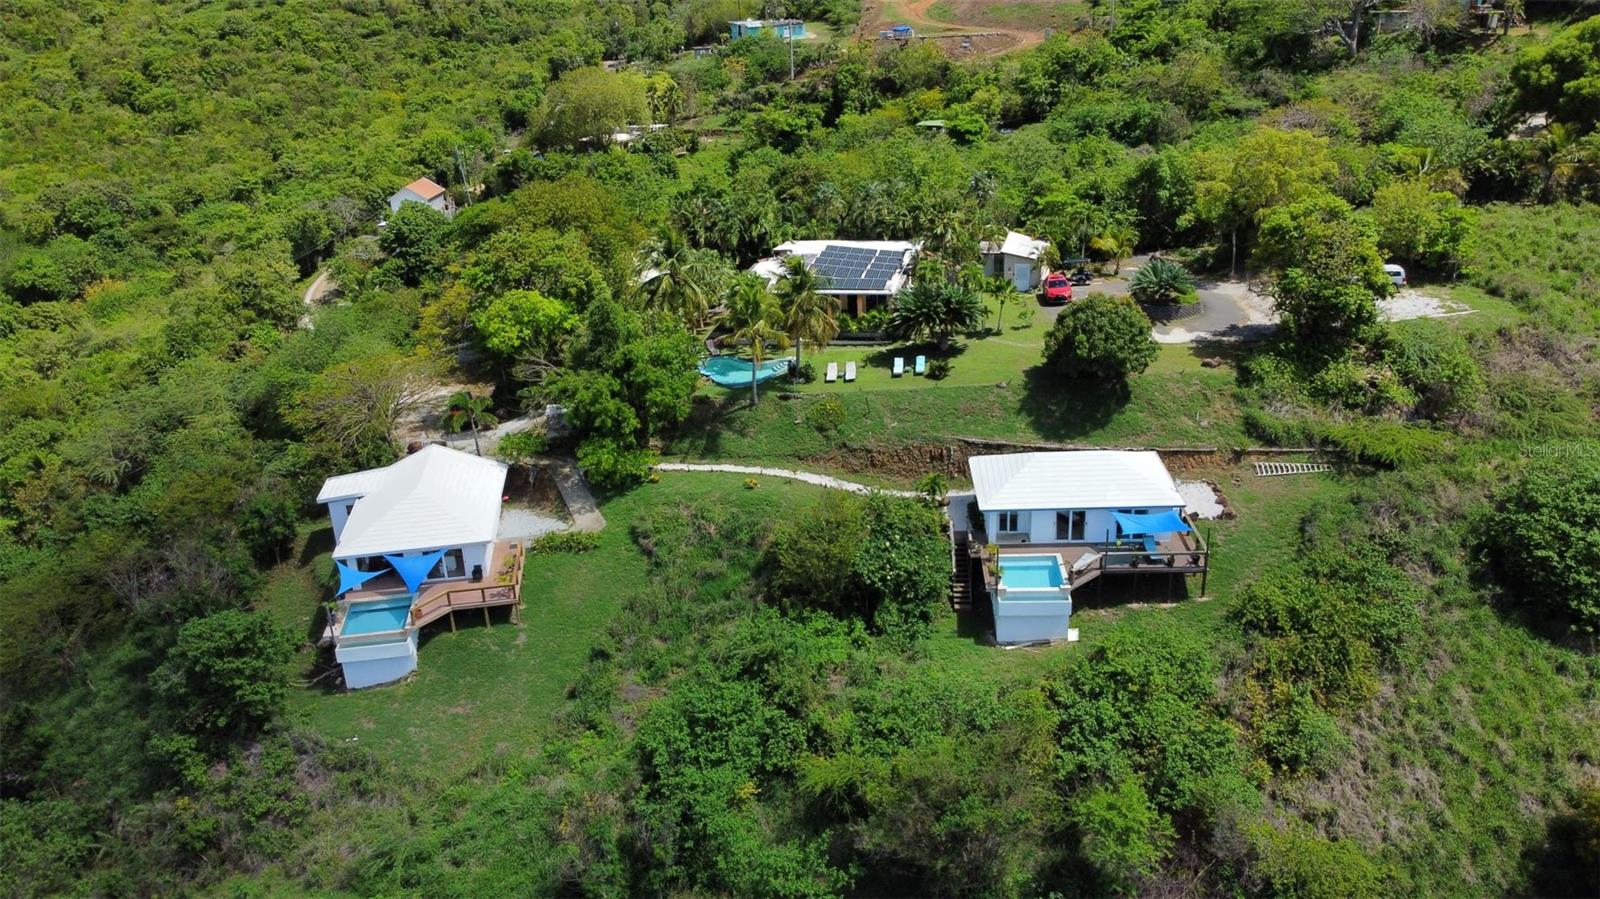
Hilltop Vacation Rental Homes is a five-building hospitality property on Mount Resaca in Culebra with solar and water infrastructure and access to beaches, town, the airport, and the ferry. Buyers should verify operating history, permits, financials, and current listing status before relying on projected rental income.
Conclusion
Puerto Rico rental income reporting requires the correct return and schedules, complete records, and separate attention to the Tourism Company’s monthly room-tax rules for stays under 90 days. Owners should confirm current requirements with Hacienda, the Puerto Rico Tourism Company, and a qualified Puerto Rico tax professional before filing.
At Christie's International Real Estate Puerto Rico, we're here to guide you in buying, selling, or renting luxury properties in Puerto Rico. Our team's real estate agents and realtors have the expertise to ensure seamless transactions, maximize your investment potential, and support your unique real estate goals. Connect with us today!
FAQs
How do I report income from Puerto Rico?
Puerto Rico rental income is generally reported to Hacienda on the return and schedules applicable to the owner; individual owners commonly use Form 482 with Schedule N. Entity type, residency, withholding, and mixed-use facts can change the filing method, so confirm the current forms with a Puerto Rico tax professional.
Is rental income taxable in Puerto Rico?
Generally, yes. Puerto Rico–source rental income is subject to Puerto Rico reporting and tax rules, with taxable income depending on allowed expenses, depreciation, residency, ownership structure, and other facts. An Act 60 decree should not be assumed to exempt ordinary rental income.
What qualifies as Puerto Rico source income?
Rent from real property located in Puerto Rico is generally Puerto Rico–source income. Whether it must also appear on a U.S. federal return depends on factors including bona fide Puerto Rico residency, citizenship or immigration status, and other income; IRS Publication 570 explains the federal sourcing and filing framework.
Is any income earned in Puerto Rico exempt from U.S. taxes?
Not automatically. A bona fide Puerto Rico resident whose only income is from Puerto Rico sources generally is not required to file a U.S. federal income tax return, but exceptions apply, including certain self-employment income, U.S. government wages, and income from outside Puerto Rico.
Do I need to file both Puerto Rico and U.S. tax returns if I am a resident of Puerto Rico?
It depends on bona fide residency and the sources and types of income. Bona fide Puerto Rico residents generally report worldwide income to Puerto Rico and may have a U.S. filing obligation for income outside Puerto Rico or for special categories such as self-employment income; non-bona-fide residents may need both returns.
Do I need to report rental income if I’m a nonresident or only rent the property occasionally?
Yes. Puerto Rico–source rental income is generally reportable to Hacienda even if you live off-island or rent only part of the year; your filing method and any withholding rules can vary based on residency and how the property is held.
What happens if a booking platform collects the accommodation tax—am I still responsible?
The owner should verify what the platform collected and remitted, retain the platform statements, and confirm whether any monthly declarations or payments remain due under the owner’s innkeeper account. Platform collection does not replace the need to keep accurate registration and filing records.
How should I handle mixed use (personal use plus rentals) for deductions?
Track rental days vs. personal-use days and allocate shared expenses (e.g., utilities, insurance, repairs) accordingly; only the rental portion is generally deductible, and good logs help support the allocation if questioned.