Real estate can help preserve and build wealth, but no property purchase is automatically safe. A Puerto Rico real estate investment can gain or lose value, produce uneven income, require substantial maintenance, and take time to sell. Its suitability depends on the buyer’s goals, time horizon, liquidity needs, financing, insurance, location, and willingness to manage property-specific risks.
This 2026 update explains where real estate may add stability, where it differs from insured cash and marketable securities, and which Puerto Rico due-diligence questions matter before a buyer commits capital. It is general information rather than individualized legal, tax, or investment advice.
Is Real Estate the Safest Investment?
No single asset is the safest choice for every purpose. An owner-occupied home, an income property, a publicly traded REIT, a diversified securities portfolio, and an FDIC-insured savings account have different risk, return, liquidity, and management characteristics. Investors should compare those characteristics instead of treating “real estate” as one uniform investment.
Direct property ownership offers a tangible asset and potential rental income, but it also concentrates capital in one location. Market conditions, financing costs, insurance availability, taxes, vacancies, repairs, title issues, condominium rules, and natural hazards can all affect the result.
Why Real Estate Can Add Stability
- Tangible use: A property may serve as a residence, second home, long-term rental, or other legally permitted use.
- Potential income: Rent may offset some ownership costs when demand, pricing, occupancy, and management support a viable operation.
- Long holding period: Property is commonly evaluated over years rather than by daily price changes, although its market value still fluctuates.
- Financing: Mortgage debt can expand purchasing power, but leverage also magnifies losses and creates fixed payment obligations.
- Inflation sensitivity: Values and rents may rise during some inflationary periods, while insurance, taxes, utilities, construction, and maintenance costs may rise as well.
Is Real Estate Safer Than Other Investments?
The answer depends on what “safe” means. Capital preservation, access to cash, income consistency, price stability, and long-term growth are separate goals.
Asset Type | Potential Strength | Important Risk | Liquidity |
|---|---|---|---|
Direct real estate | Use value, potential rent, and long-term appreciation | Concentration, leverage, vacancies, repairs, insurance, and transaction costs | Low; marketing and closing can take time |
Diversified stocks and bonds | Broad diversification and transparent market pricing | Market volatility, issuer risk, interest-rate risk, and possible loss of principal | Generally high for publicly traded securities |
Insured bank deposits | Principal protection within applicable insurance limits and ready access to funds | Returns may not keep pace with inflation; coverage depends on bank and account structure | High, subject to the account’s terms |
REITs | Real-estate exposure without directly operating a property | Market, sector, leverage, fee, management, and liquidity risks vary by REIT type | High for publicly traded REITs; potentially low for non-traded REITs |
The SEC’s Investor.gov investment guide emphasizes risk, fees, diversification, and liquidity when comparing products. The FDIC states that qualifying deposits are generally insured up to $250,000 per depositor, per FDIC-insured bank, for each ownership category. Direct real estate has no comparable federal guarantee against a decline in value.
Historical Resilience Does Not Eliminate Risk
Property markets have recovered after many recessions and disruptions, but recovery has not been uniform across locations, property types, or owners. The 2008 financial crisis also demonstrates that housing can be central to a severe downturn, particularly when leverage, weak underwriting, or forced selling are involved.
Puerto Rico adds location-specific considerations. Hurricane exposure, flood zones, insurance deductibles, utility resilience, construction condition, title review, municipal requirements, and condominium or homeowners’ association restrictions can materially affect value and operating costs.
Why Choose Real Estate Over Stocks or Bank Deposits?

Real estate may suit capital intended for a long holding period when the buyer values personal use, control over improvements, or the possibility of rental income. Stocks and bonds may offer easier diversification and liquidity, while insured bank deposits can be more appropriate for emergency reserves and near-term obligations.
That distinction matters because money needed soon should not be locked into a property that may require months to sell. A purchase also creates transaction and carrying costs, including due diligence, closing expenses, financing, property taxes, insurance, association dues, utilities, repairs, and eventual selling costs.
Decision Factor | Direct Puerto Rico Real Estate | Stocks and Bonds | Insured Bank Deposits |
|---|---|---|---|
Control | Owner can improve, occupy, lease, or sell subject to law and community rules | Investor does not control the underlying company or issuer | Account holder selects the institution and account type |
Income | Possible rent, reduced by vacancies and operating costs | Possible dividends or interest; amounts can change | Contractual interest subject to account terms |
Valuation | Comparable sales, condition, location, and buyer demand | Continuous market pricing for traded securities | Deposit balance does not fluctuate with market prices |
Management | Requires maintenance, administration, and compliance | Varies by product; funds may offer professional management | Minimal ongoing management |
Diversification remains important. Investor.gov notes that spreading capital across and within asset classes can reduce risk, although it cannot prevent every loss. Concentrating most available capital in one house can leave an investor exposed to a single location, borrower, property condition, and resale market.
The Resilience of Real Estate During Crises

Image Source: Britannica
Real estate has endured economic shocks, wars, interest-rate cycles, and natural disasters, but the phrase “real estate always goes up” is not a dependable investment rule. Britannica’s history of the Great Depression provides context for one major economic contraction; property performance during any crisis still depends on leverage, location, use, supply, and the owner’s ability to hold through disruption.
What Historical Events Actually Show
- Economic contractions can reduce demand: Employment losses, credit tightening, and higher financing costs can pressure prices and rents.
- Property sectors behave differently: Residential, hospitality, retail, office, industrial, and land markets may respond differently to the same event.
- Leverage changes the outcome: A sound property can still become financially difficult when debt service, vacancies, or repair costs exceed available cash.
- Recovery is location-specific: Past rebounds do not establish the timing or magnitude of a future recovery.
- Resilience requires preparation: Insurance, reserves, backup utilities, durable construction, and a realistic exit strategy can matter as much as projected appreciation.
In Puerto Rico, a buyer should review the property’s physical condition and insurability rather than relying on a general claim about the luxury market. The FEMA Flood Map Service Center can support an initial flood-zone review, but survey, elevation, insurance, engineering, and legal questions should be confirmed with qualified local professionals.
How Puerto Rico Real Estate Can Support Wealth Planning
Puerto Rico real estate may support long-term wealth planning when a property is purchased at a defensible price, matches the buyer’s intended use, and remains affordable under conservative assumptions. The analysis should begin with downside scenarios rather than guaranteed appreciation or rental income.
Tangible Asset and Practical Use
Direct ownership gives the buyer control over occupancy, improvements, and permitted rental use. That control is valuable, but title conditions, zoning or permitted use, condominium documents, easements, deferred maintenance, and resale limitations should be reviewed before closing.
Appreciation Is Possible, Not Guaranteed
Puerto Rico property values can rise or fall as interest rates, supply, demand, neighborhood conditions, insurance costs, and economic activity change. Buyers should test comparable sales, current competition, replacement cost, and a realistic holding period instead of assuming that a past increase will continue.
Rental Income Requires Net-Income Analysis
Gross rent is not the same as investment return. A rental projection should deduct vacancies, concessions, platform charges where applicable, management, cleaning, utilities, repairs, insurance, association dues, property taxes, licensing, reserves, and financing costs.
Short-term and long-term strategies also have different operating and compliance requirements. Investors comparing them can review this guide to Puerto Rico long-term and short-term rentals.
Inflation Protection Has Limits
Property values and rents may increase during inflationary periods, but expenses may rise at the same time. Insurance premiums, repairs, labor, materials, utilities, taxes, and borrowing costs can reduce or eliminate the benefit, particularly when leases or market demand do not support higher rent.
Real Estate and Savings Serve Different Purposes
A savings account can provide liquidity and federal deposit insurance within applicable limits. Real estate offers potential use, income, and appreciation, but it is illiquid and exposed to market and property-specific losses. Describing a house as being as safe as insured cash overlooks these differences.
Safety and Value Comparison
Question | What to Review for a Property |
|---|---|
Can the buyer hold through a downturn? | Cash reserves, debt service, expected repairs, insurance deductibles, and income stability |
Is income reasonably supported? | Current comparables, permitted use, building rules, realistic occupancy, and complete expenses |
Is the property insurable and resilient? | Flood and wind exposure, construction, roof and systems, backup power and water, and available coverage |
Is the exit strategy realistic? | Likely buyer pool, market time, selling costs, financing conditions, and alternative uses |
Wealth Preservation and Act 60
Puerto Rico’s Act 60 contains incentives for defined eligible activities and taxpayers with approved decrees, but a property purchase does not automatically qualify. Income sourcing, residency, pre-move appreciation, rental activity, entity structure, and decree terms can produce different tax outcomes.
Investors should obtain advice from qualified Puerto Rico tax and legal professionals and review current official guidance before making a decision. This overview of Act 60 and Puerto Rico real estate provides additional context without replacing professional advice.
Properties and Houses for Sale in Puerto Rico
The safety of a real estate investment begins with the specific asset, not a general market label. Christie’s International Real Estate Puerto Rico represents luxury properties for sale across urban, suburban, historic, and resort communities. The following active listings illustrate different locations and ownership profiles that should be evaluated through property-specific due diligence.

934 ISLA NORTE DORADO PR, 00646
This active 2023 Dorado residence offers four bedrooms, six bathrooms, approximately 5,100 square feet, furnished interiors, and a private pool. Buyers can evaluate its modern construction, community setting, carrying costs, and intended use against their investment and lifestyle priorities.
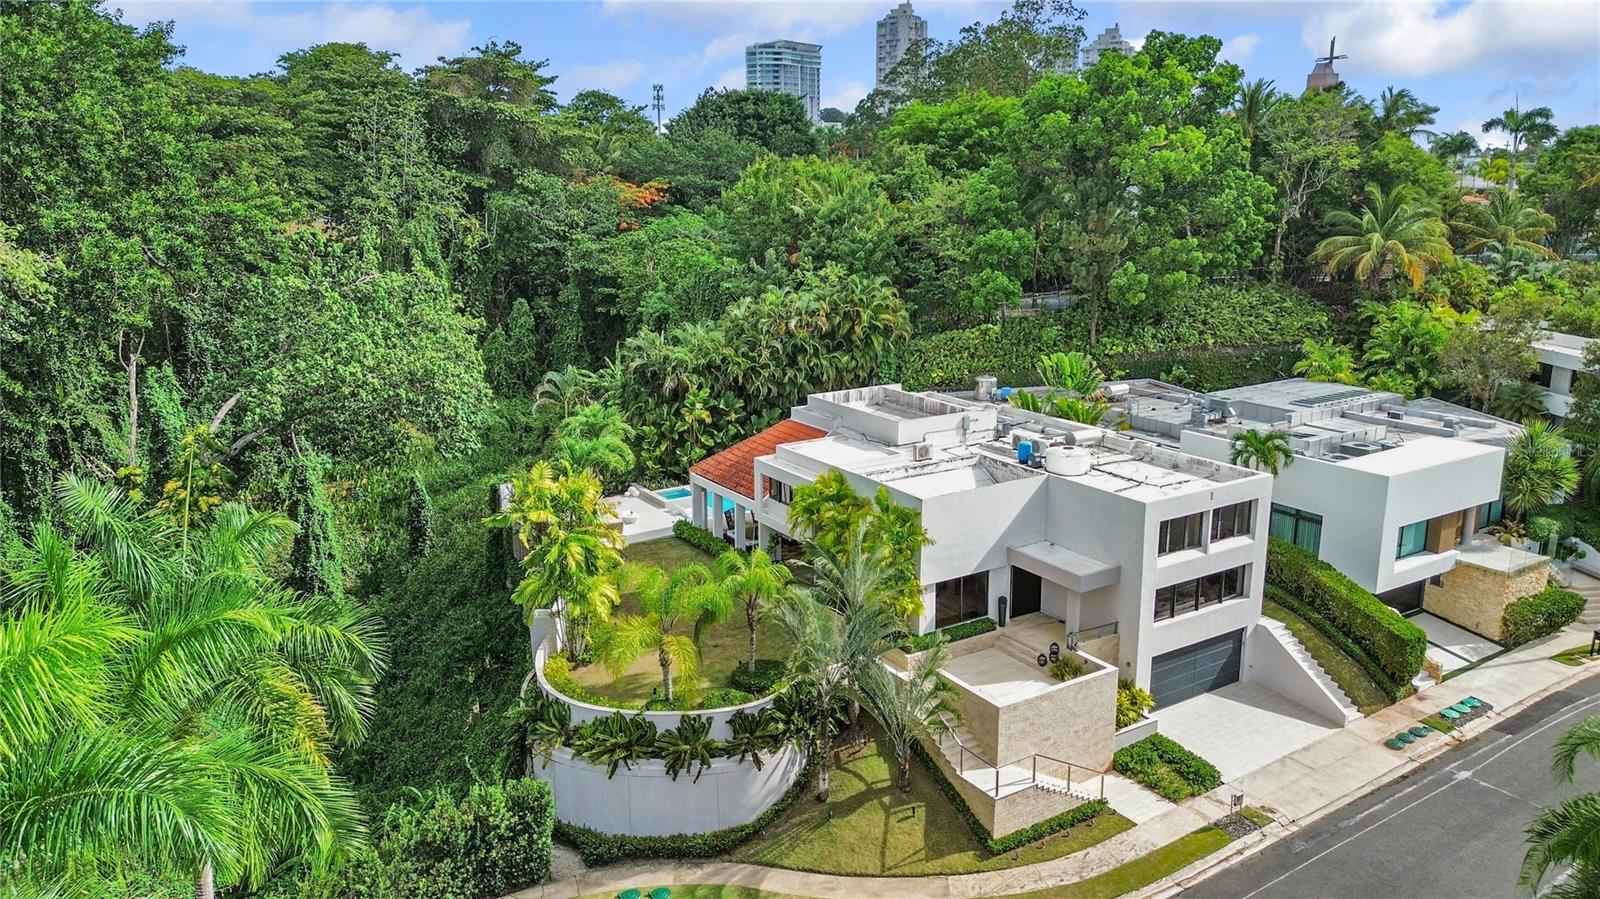
#9 Palma Real ESTANCIAS DE TORRIMAR, GUAYNABO PR, 00966
This active Estancias de Torrimar property has five bedrooms, six bathrooms, approximately 5,012 square feet, a resort-style pool and hot tub, a generator, and a water cistern. Its gated Guaynabo setting and community amenities may suit buyers prioritizing residential use, privacy, and access to the metropolitan area.

2301 SOLDADO CRUZ SAN JUAN PR, 00913
This active San Juan residence near Ocean Park Beach has six bedrooms, five bathrooms, approximately 2,843 square feet, a heated pool, and a full generator. Any rental-income plan should be independently underwritten and checked against applicable permits, community rules, insurance, and operating costs.

9 CALLE DEL MERCADO SAN JUAN PR, 00901
This active 1920 Old San Juan property offers six bedrooms, five bathrooms, approximately 3,420 square feet, and a private rooftop with views toward the historic district. Buyers should verify its present layout, permitted use, historic-building considerations, operating history, and renovation needs before relying on an income projection.
Conclusion
Puerto Rico real estate can support long-term wealth planning, but safety depends on the property, purchase terms, financing, insurance, reserves, management, and exit strategy. Direct ownership is not equivalent to an insured savings account, and neither appreciation nor rental income is guaranteed. A disciplined buyer should compare assets, preserve adequate liquidity, and complete legal, tax, physical, market, and insurance due diligence.
Christie’s International Real Estate Puerto Rico can help buyers, sellers, and owners evaluate Puerto Rico luxury properties based on location, condition, intended use, and current market context. Contact the team to compare available opportunities and coordinate property-specific guidance with the appropriate professional advisers.
FAQs
Are property funds risky?
Yes. Property funds can be affected by real estate values, interest rates, leverage, sector concentration, fees, management decisions, and redemption limits. Investors should review the fund’s holdings, structure, liquidity terms, costs, and disclosures before investing.
Are REITs safer than stocks?
A REIT is a type of equity investment, so it should not automatically be described as safer than stocks. Publicly traded REITs can fluctuate with markets and interest rates, while non-traded REITs can present additional liquidity, valuation, fee, and conflict-of-interest risks described by Investor.
Should you invest all your money in a house?
Concentrating all available capital in one property can reduce liquidity and diversification while increasing exposure to one location and one asset. Buyers should retain appropriate reserves and obtain individualized financial advice before committing a large share of their net worth.
What should a Puerto Rico property investor review before buying?
Key areas include title and survey documents, permitted use, condominium or HOA rules, physical inspections, flood and wind exposure, insurance availability, financing, comparable sales and rents, complete operating costs, taxes, management, and an exit strategy. Additional review may be required for historic properties, short-term rentals, new construction, or properties with income claims.