
Puerto Rico residency can mean several different things: living on the island, maintaining lawful U.S. immigration status, becoming a bona fide Puerto Rico resident for federal tax purposes, or qualifying for a Puerto Rico incentive decree. The most expensive mistakes begin when these separate concepts are treated as one application or when a move is planned around a single day count.
Key Takeaways
- U.S. citizens can relocate to Puerto Rico without a visa, while non-U.S. citizens remain subject to U.S. federal immigration law.
- Bona fide Puerto Rico tax residency generally requires the presence, tax-home, and closer-connection tests.
- Spending 183 days in Puerto Rico is one way to meet the presence test, but it does not establish residency by itself.
- Buying a home or receiving an Act 60 decree does not replace the federal residency tests.
- Travel records, filings, housing documents, and consistent personal and business ties should support the facts of the move.
Mistake #1: Treating Residency as One Application

There is no single Puerto Rico residency application that covers immigration, taxes, domicile, and incentive eligibility. Start by identifying which legal question applies to the person moving and which agency or adviser handles it.
For U.S. Citizens
Puerto Rico is a U.S. territory, so a U.S. citizen does not apply for a visa or Green Card to move there. Housing, address changes, employment, insurance, banking, and local registrations may help document a genuine relocation, but federal tax residency is determined under separate rules.
For Non-U.S. Citizens
Puerto Rico does not operate a separate immigration system. A non-U.S. citizen must maintain or obtain an appropriate status under U.S. federal immigration law and should use current USCIS eligibility guidance or qualified immigration counsel rather than a Puerto Rico-specific visa checklist.
A property purchase does not create U.S. immigration status. Visa, employment authorization, adjustment of status, and permanent-residence questions depend on the person’s federal immigration category.
Mistake #2: Relying Only on the 183-Day Rule
The familiar 183-day rule is important, but it is not the complete federal test. IRS guidance generally requires an individual to meet the presence test, have no tax home outside Puerto Rico, and have no closer connection to the United States or a foreign country than to Puerto Rico.
Spending at least 183 days in Puerto Rico is one way to satisfy the presence test, and other statutory methods may apply in particular circumstances. Review the current IRS Publication 570 rules, including how days are counted and the special provisions that can apply during a move year.
Use a Defensible Travel Calendar
Maintain contemporaneous travel records rather than reconstructing them after the tax year. Tickets, itineraries, card activity, phone records, and other evidence may help substantiate where days were spent, but the appropriate record set depends on the person’s facts.
Mistake #3: Ignoring the Tax-Home Test
A person can spend substantial time in Puerto Rico and still have a tax home outside the island. The tax-home analysis generally focuses on the regular or principal place of business, employment, or post of duty rather than simply the location of a house.
Remote work, mainland business operations, frequent work travel, and the location where services are performed all deserve review before the move. Do not assume that changing a mailing address or working occasionally from Puerto Rico automatically resolves the test.
Questions to Review Before Moving
- Where will the person regularly perform services?
- Where are the principal business operations and management activities?
- Does an employer or client arrangement require substantial work outside Puerto Rico?
- Do move-year exceptions or special rules apply?
Mistake #4: Keeping Stronger Connections Elsewhere

The closer-connection test looks at the overall facts and circumstances, not one document. The location of a permanent home, family, personal belongings, banking, business activity, professional and community relationships, licenses, voting registration, and addresses used on official records can all be relevant.
Keeping a larger home, daily routines, and most personal or economic ties on the mainland while making only formal address changes can undermine the intended position. Consistency across real life, government records, financial accounts, and tax filings is more useful than collecting documents that do not reflect how the person actually lives.
Avoid Checklist Thinking
A Puerto Rico driver’s license, lease, deed, or voter registration may support the analysis, but no single item controls it. The complete pattern of connections should show why Puerto Rico—not another jurisdiction—is the person’s principal home.
Mistake #5: Assuming a Home Purchase Creates Residency
Owning real estate can support a relocation plan, but a deed does not grant immigration status or automatically establish bona fide tax residence. The property must also fit the buyer’s intended use, ownership structure, daily life, budget, and any incentive-decree requirements.
Before purchasing, review title, permits, insurance, taxes, condominium or community rules, access, utilities, and the timing of the move. The Puerto Rico residency guide explains how housing documents can support—but do not independently determine—the broader analysis.
Match the Property to the Relocation Plan
A principal residence, part-time home, and rental investment serve different purposes. Buyers considering Act 60 should confirm the decree’s current residence and ownership provisions with qualified Puerto Rico counsel before choosing the buyer, vesting, or closing timeline.
Mistake #6: Mixing Act 60 with Federal Residency
An Act 60 application, an approved decree, and federal bona fide residence are related but separate matters. A decree describes Puerto Rico tax treatment and compliance obligations; it does not by itself satisfy the federal presence, tax-home, or closer-connection tests.
Act 60 also contains multiple incentive programs, so a headline rate cannot be applied to every person or every type of income. Invest Puerto Rico’s Act 60 overview describes the program at a high level, but an applicant should review the enacted law, application timing, decree terms, income sourcing, and annual obligations with qualified advisers.
Separate the Decisions
- Determine whether the move works for the household and business.
- Evaluate federal and Puerto Rico residency and filing rules.
- Assess eligibility for the specific incentive program.
- Review whether the property and ownership structure meet applicable requirements.
Mistake #7: Keeping Inconsistent Records
Residency positions become harder to support when travel records, tax filings, employment documents, banking information, and government addresses conflict. Create a recordkeeping plan before the move and update each item only when it accurately reflects the new circumstances.
Records Worth Organizing
- Travel calendars and supporting transportation records
- Housing agreements, deeds, utility accounts, and insurance records
- Employment, business, payroll, and service-location documentation
- Federal and Puerto Rico tax filings and payment confirmations
- Driver’s license, vehicle, voter, banking, and mailing records when applicable
- Act 60 decree, annual reports, and compliance evidence when applicable
Records should document actual conduct rather than manufacture an appearance of residency. If facts change during the year, advisers should review the effect before inconsistent filings are submitted.
Mistake #8: Missing Filing and Advisory Steps
Moving can create obligations with both the IRS and the Puerto Rico Department of Treasury. IRS Form 8898 may be required when a person begins or ends bona fide residence in a U.S. territory and meets the applicable worldwide-income threshold.
The current Form 8898 instructions explain who must file, the timing, and the information required. Filing obligations, income sourcing, self-employment tax, move-year rules, and incentive compliance are fact-specific, so coordinated U.S. and Puerto Rico tax advice should be obtained before relying on an exclusion or rate.
Build the Advisory Team Early
Real estate, immigration, tax, and incentive questions fall within different professional roles. A real estate brokerage can help with neighborhoods and properties, while attorneys, CPAs, and other qualified advisers should address legal status, tax positions, filings, and decree compliance.
Puerto Rico Luxury Properties for Sale
A well-chosen residence can help turn a relocation plan into a practical daily life in Puerto Rico. These current luxury properties for sale illustrate different urban, beachfront, historic, and nature-oriented options for buyers comparing where to establish a home. Availability and details can change, and each property should be reviewed alongside the buyer’s legal, tax, budget, and lifestyle requirements.
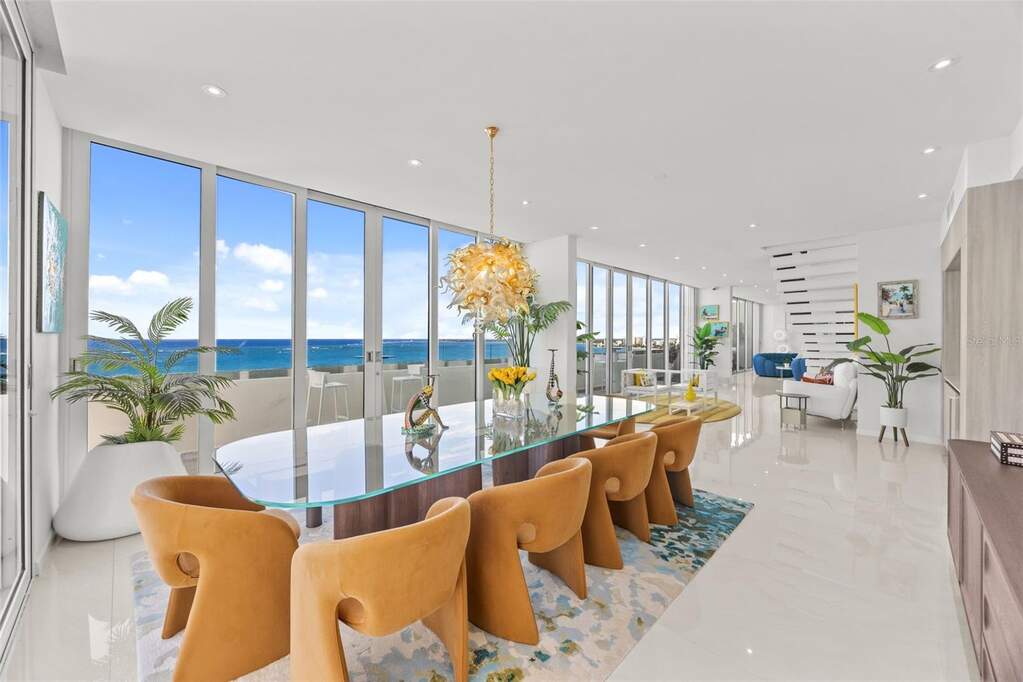
3307 Ave Isla Verde Unit PH, Carolina, PR 00979
This listed five-bedroom penthouse is presented with extensive terraces and ocean, lagoon, city, and mountain views in Isla Verde. Its location near the airport and San Juan can suit buyers prioritizing beachfront living with metropolitan access.
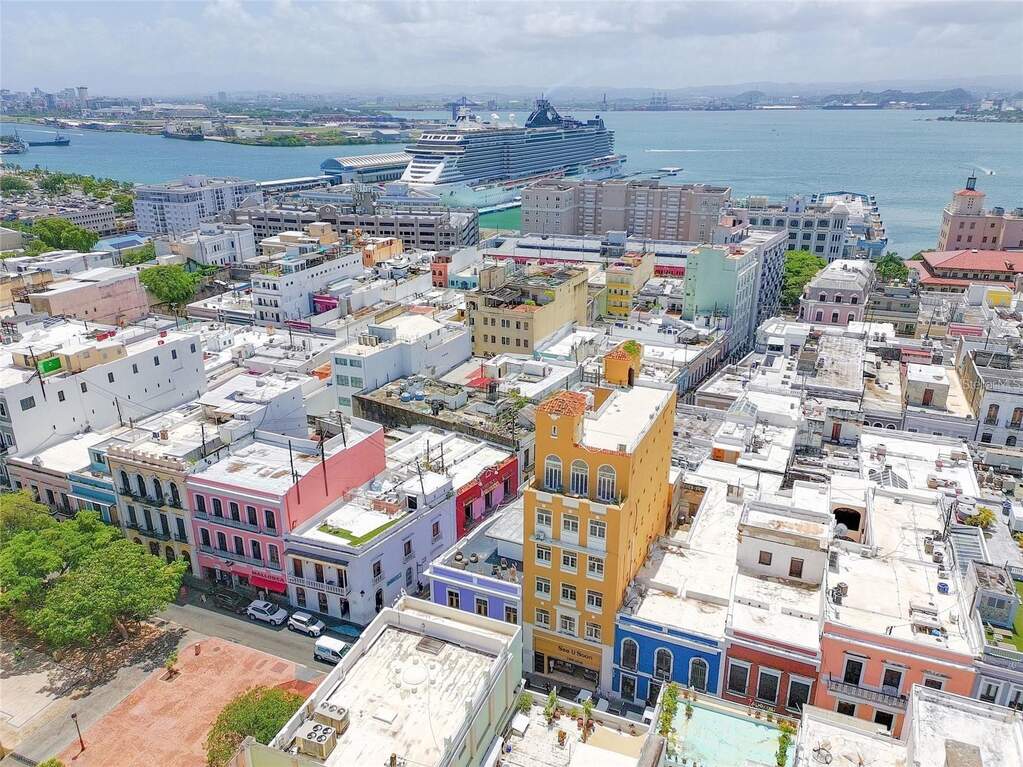
266 San Francisco Unit 266, San Juan, PR 00901
This listed six-story Old San Juan building dates to 1925 and is presented with five residential lofts and a ground-floor commercial space. Buyers should review its mixed-use configuration, historic-building obligations, permits, and intended occupancy before deciding whether it fits a relocation plan.
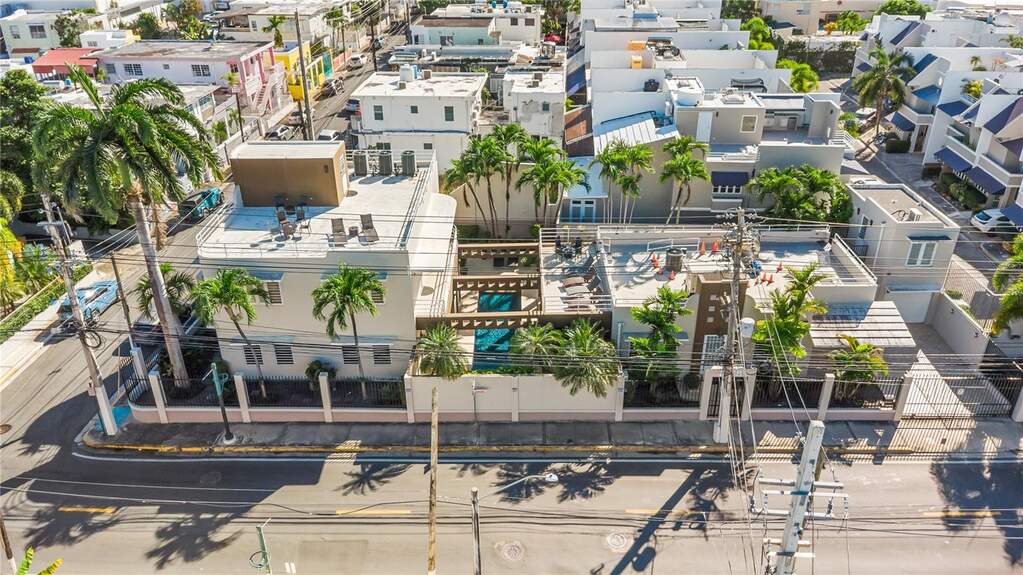
1858 McLeary, San Juan, PR 00911
This listed five-bedroom Ocean Park property is presented with three residential units, a pool, garages, rooftop areas, backup power, and water storage. Its flexible configuration may interest multigenerational households or buyers evaluating a primary residence with separate living space, subject to permits and use requirements.
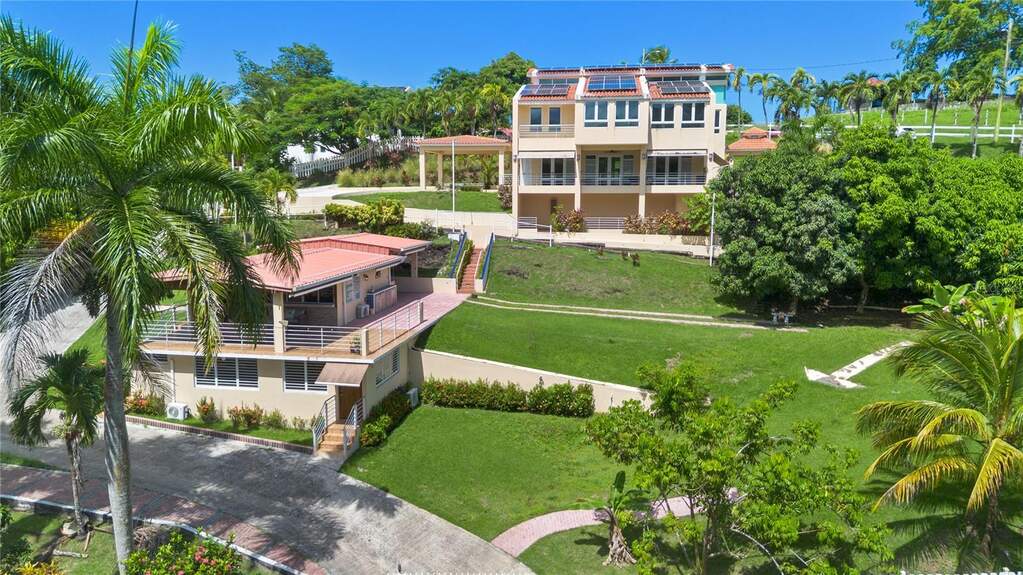
23 & 24 Hacienda Carabalí, Luquillo, PR 00773
This listed gated equestrian property includes a main residence, separate casita, stables, paddocks, solar energy, and backup batteries near El Yunque and Luquillo. It offers a contrasting relocation option for buyers seeking more land and privacy than a metropolitan condominium.
Conclusion
A successful Puerto Rico move begins by separating immigration status, everyday relocation, federal tax residency, and Act 60 eligibility. The strongest plan reflects where the person actually lives and works and is supported by consistent records and timely filings. Property decisions should complement that plan rather than be treated as proof of residency by themselves.
If you want to rent, buy, or sell Puerto Rico luxury properties, you can rely on Christie’s International Real Estate Puerto Rico for informed local real estate guidance. Contact the team to discuss the location, property type, and housing timeline that support your relocation goals.
FAQs
Do U.S. Citizens Need a Visa to Move to Puerto Rico?
No. U.S. citizens may relocate to Puerto Rico without applying for a visa or Green Card, although tax residency and incentive eligibility have separate requirements.
Is Spending 183 Days in Puerto Rico Enough for Tax Residency?
Not by itself. The IRS generally requires the presence test, no tax home outside Puerto Rico, and no closer connection to the United States or a foreign country than to Puerto Rico.
Does Buying a Puerto Rico Home Establish Residency?
No. A home may support the facts of a genuine move and may be relevant to an incentive decree, but ownership alone does not establish immigration status or bona fide federal tax residence.
Who May Need to File IRS Form 8898?
Individuals who begin or end bona fide residence in a U.S. territory and exceed the applicable worldwide-gross-income threshold may need to file it. Review the current instructions and obtain advice for the specific tax year and circumstances.
Related Articles
These guides provide additional context for residency rules, Act 60 planning, and housing decisions in Puerto Rico.


