Financing a home or investment property in Puerto Rico begins with the same core questions lenders ask elsewhere in the United States: how the property will be used, how income and assets will be documented, how much equity the borrower will contribute, and whether the property meets the loan program’s requirements. Puerto Rico also has local appraisal, title, notarial, insurance, and Property Registry considerations that should be reviewed before closing.
This 2026 guide compares common mortgage options in Puerto Rico and explains what buyers with limited or no traditional credit history should discuss with a lender. Program availability, rates, credit standards, down payments, fees, and approval decisions vary by lender and borrower; this article is general information, not personalized financial, legal, or tax advice.
Key Takeaways
- Conventional, FHA, VA, USDA, and non-QM financing may be available in Puerto Rico, but each program has different borrower, occupancy, property, and documentation rules.
- A borrower without a traditional credit score is not automatically approved or denied; some programs permit verified nontraditional payment history, while individual lenders may impose additional standards.
- FHA, VA, and USDA programs generally focus on eligible owner-occupied homes rather than vacation homes or pure investment properties.
- Compare the annual percentage rate, points, lender fees, mortgage insurance, cash required at closing, insurance, HOA obligations, and total monthly payment—not only the advertised interest rate.
- For Puerto Rico property, confirm title, appraisal, insurance, permits, condominium documents, and the mortgage’s presentation and registration requirements with qualified local professionals.
Types of Loans Available in Puerto Rico
Available financing depends on the borrower, lender, property type, purchase price, location, and intended use. Buyers should obtain written loan estimates and confirm that a lender is authorized and willing to finance the specific Puerto Rico property before relying on a prequalification.
1. Conventional Loans
Conventional mortgages are made by private lenders and are not insured by FHA, guaranteed by VA, or offered through USDA. Credit, income, assets, debt-to-income ratio, appraisal, reserves, property type, and occupancy all affect approval and pricing.
There is no universal Puerto Rico conventional-loan credit score or down-payment requirement. A lender may offer different terms for a primary residence, second home, condominium, multi-unit property, or investment property, and mortgage insurance may apply when the loan-to-value ratio exceeds the lender’s threshold.
Questions to ask a conventional lender
- Does the lender finance property in the municipality and condominium or community being considered?
- What documentation is required for salary, self-employment, rental income, foreign income, or assets?
- Are reserves, mortgage insurance, condominium approval, or a larger down payment required?
- How will wind, flood, hazard, and title insurance affect approval and the monthly payment?
2. FHA Loans
FHA-insured mortgages are issued by approved lenders and may allow a minimum required investment of 3.5% in many cases. Eligibility is not determined by down payment alone: the borrower, property, occupancy, appraisal, mortgage insurance, and underwriting must meet current HUD requirements.
FHA financing is generally for a principal residence, not a vacation home or a property purchased solely for rental income. FHA mortgage limits are updated annually and vary by area and number of units, so buyers should use HUD’s current mortgage-limit resources rather than relying on an old figure.
FHA credit and property review
HUD guidance permits lenders to evaluate certain borrowers who do not have a traditional credit score using documented nontraditional credit references. That does not guarantee approval, and the lender must still assess the complete file under the current FHA handbook. The property must also satisfy FHA eligibility and appraisal requirements, and FHA mortgage insurance affects upfront and ongoing costs.
3. VA Loans
Eligible veterans, service members, and certain surviving spouses may use a VA-backed purchase loan for a home they intend to occupy. A valid Certificate of Eligibility is necessary, but the borrower must also satisfy the lender’s income, credit, underwriting, appraisal, and occupancy requirements.
VA states that it does not impose a minimum credit score, although individual lenders may. In many cases the guaranty permits an eligible borrower with sufficient entitlement to buy without a down payment, but lender approval, entitlement, appraisal, purchase price, and other circumstances still control. Review current eligibility and occupancy guidance through the VA Home Loan program.
4. USDA Rural Housing Loans
USDA Rural Development offers housing programs for eligible borrowers purchasing qualifying homes in eligible rural areas. Puerto Rico’s Section 502 Direct Loan Program is aimed at low- and very-low-income applicants who will occupy the property as their primary residence and meet repayment, location, citizenship or eligible-noncitizen, and other program requirements.
No down payment is typically required under the direct program, although applicants with assets above applicable limits may need to contribute funds. The property cannot be designed for income-producing activities, and buyers must confirm both household income and the exact property address through the USDA Rural Development Puerto Rico program.
5. Non-QM and Portfolio Loans
Non-qualified mortgage and portfolio products may use alternative documentation or underwriting approaches for some self-employed buyers, investors, or borrowers whose income does not fit a conventional template. Product names do not create a uniform standard: lenders set their own eligible property types, documentation, reserves, credit criteria, loan-to-value limits, rates, and fees.
Alternative documentation does not mean no verification. Buyers should compare the annual percentage rate, prepayment provisions, points, balloon features, adjustable-rate terms, appraisal rules, and total cash requirement with other available financing.
Can You Buy a House in Puerto Rico With No Credit?
It may be possible to qualify without an established traditional credit score, but “no credit” is different from poor credit and does not remove underwriting. Some FHA files may use a nontraditional mortgage credit report or independently verified payment history, and VA guidance allows alternative or nontraditional credit analysis when a borrower has no established history. Individual lenders can apply additional requirements.
Start by checking all three credit reports for errors, documenting recurring payments such as rent and utilities, organizing income and asset records, and speaking with lenders that actually originate Puerto Rico mortgages. Do not open new accounts solely to create a score immediately before applying without first discussing the effect with a qualified lender or housing counselor.
Understanding Underwriting Standards
Underwriting evaluates the borrower and the collateral together. Lenders commonly review credit history, verified income, employment or business stability, existing debts, liquid assets, reserves, intended occupancy, purchase contract, appraisal, title, insurance, and the property’s condition and marketability.
Approval standards differ across programs and lenders. A flexible-documentation product may still require substantial equity or reserves, and a strong borrower file does not cure a property that is ineligible for the selected program.
Mortgages and Security Interests
A Puerto Rico real-estate loan is commonly secured by a mortgage granted over the property. The mortgage deed, title review, presentation, taxes and fees, and registration should be handled by the closing professionals in accordance with Puerto Rico law and the lender’s requirements.
Puerto Rico’s Property Registry law governs the registration system. Because title and lien questions can be fact-specific—and registry processing can affect timing—buyers and lenders should obtain Puerto Rico legal and notarial guidance rather than relying on a general statement about enforceability or priority.
Using a Mainland U.S. Lender
Some mainland institutions finance Puerto Rico property, while others do not originate loans on the island or do not finance every property type. Confirm territorial coverage, licensing, appraisal arrangements, condominium or project review, flood and wind insurance requirements, title and closing procedures, and expected timelines before comparing an offer with a Puerto Rico-based lender.
A lender’s location alone does not determine whether its rates, closing costs, or processing will be better. Compare written estimates for the same loan amount, rate structure, lock period, occupancy, and closing date.
Costs Associated with Borrowing
Cash needed at closing can include the down payment, lender origination or underwriting charges, discount points, appraisal and inspection costs, legal and notarial charges, title work, recording and filing costs, prepaid interest, escrow deposits, mortgage insurance, hazard and wind coverage, flood insurance when applicable, and condominium or HOA items.
There is no reliable universal percentage that describes every Puerto Rico closing. Request an itemized Loan Estimate, review the Closing Disclosure before signing when applicable, and ask which charges can change. For a condominium or resort property, also review current HOA fees, special assessments, reserves, insurance responsibilities, rental restrictions, and any lender project-approval requirements.
Luxury Homes for Sale in Puerto Rico
Financing needs can differ substantially among a primary residence, resort home, mixed-use building, and newly built property. These current luxury homes for sale illustrate why buyers should confirm the eligible property type, appraisal approach, required equity, reserves, insurance, and permitted use with the lender before making an offer.
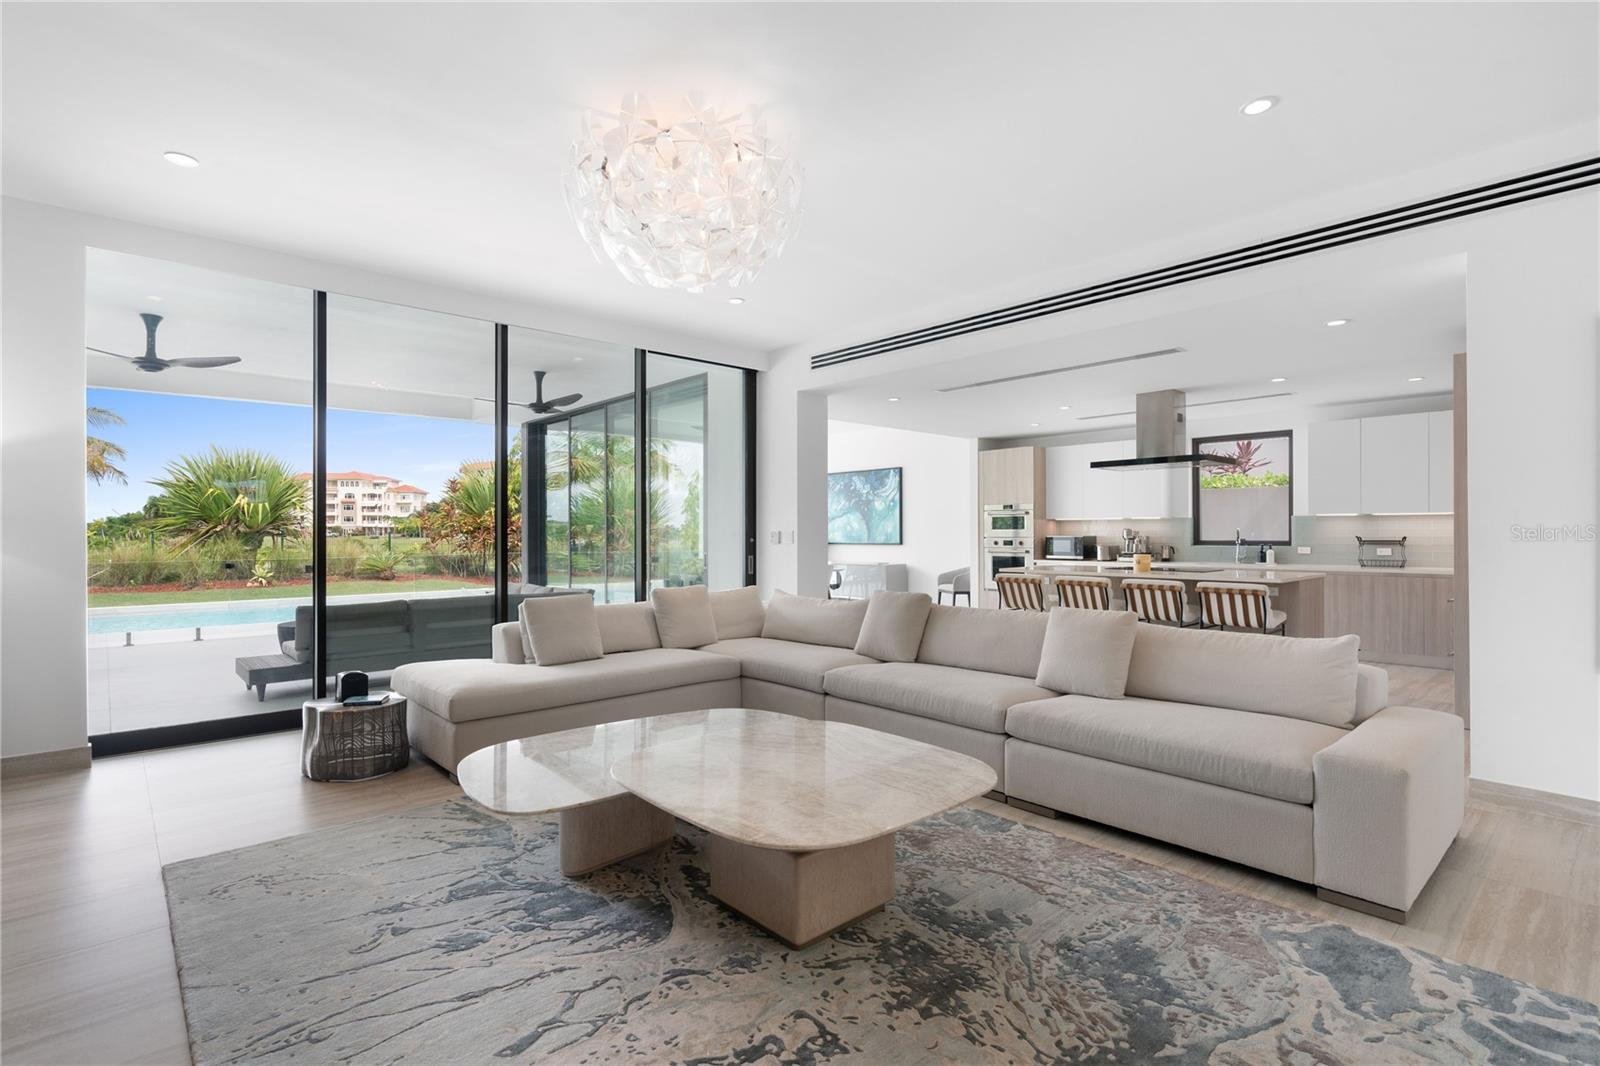
3 The Enclave, Dorado, PR 00646
This Dorado Beach residence is currently listed with five bedrooms, six bathrooms, and approximately 4,666 square feet. Buyers comparing financing should confirm second-home or primary-residence treatment, insurance, appraisal, reserves, and community obligations with their lender.
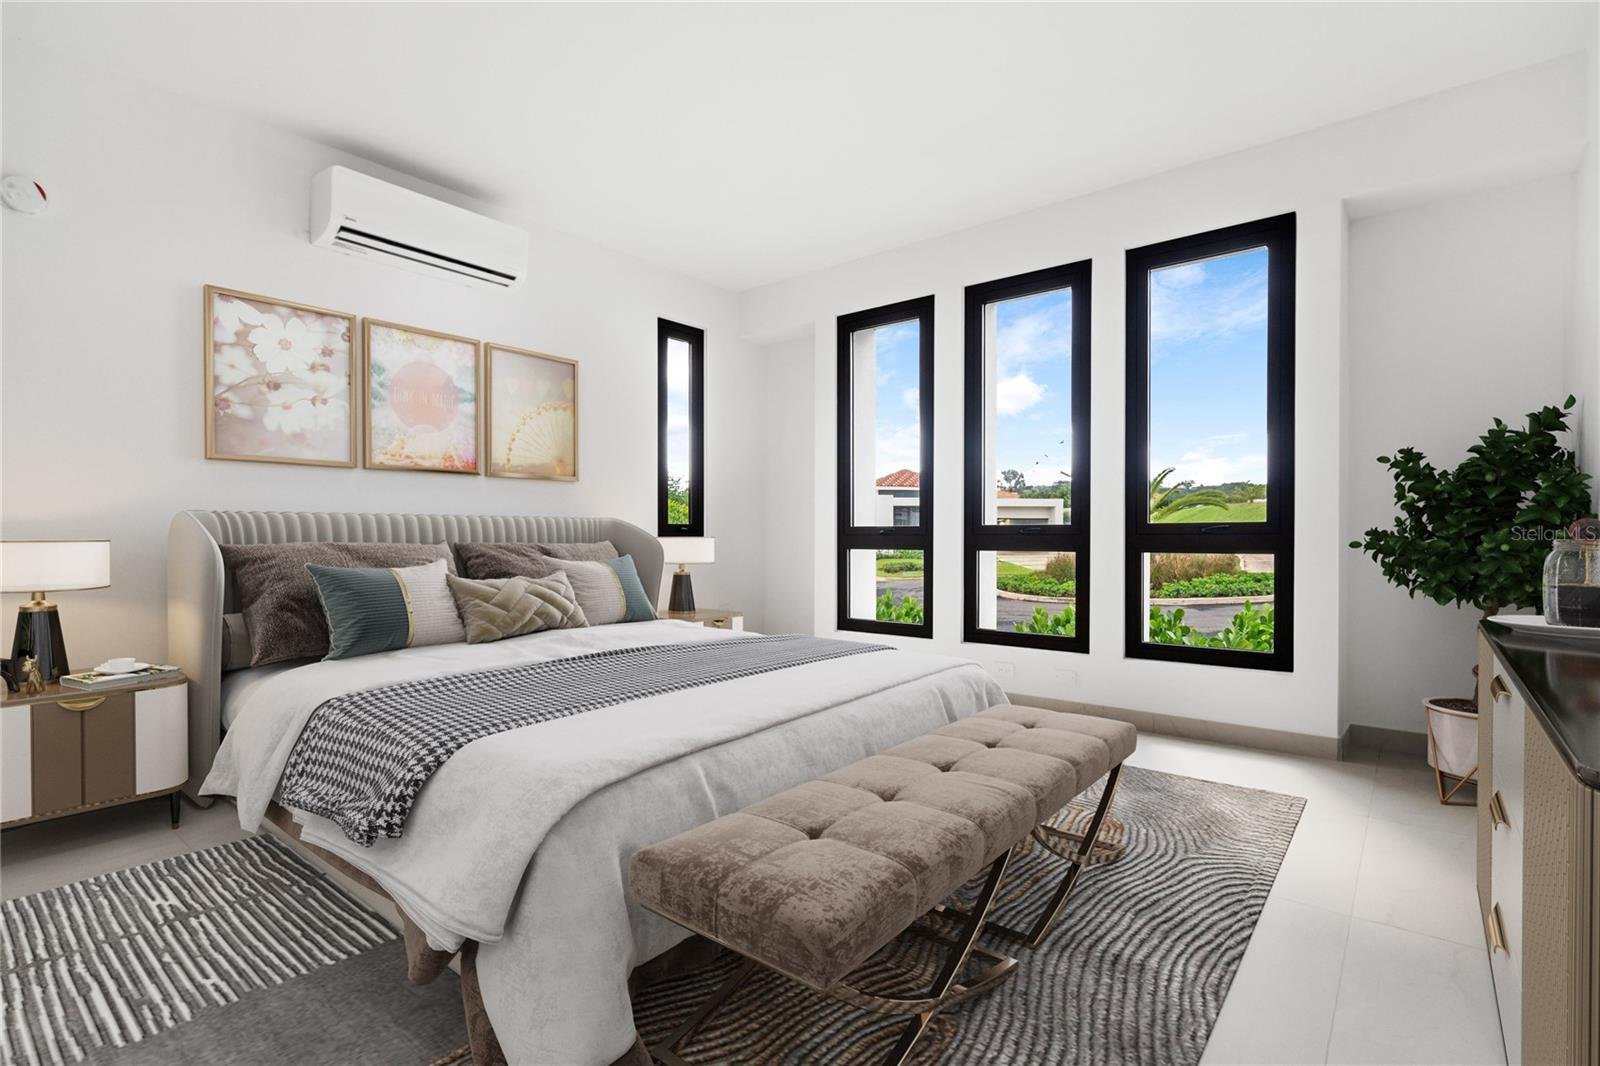
49 Los Lagos, Humacao, PR 00791
This 2026 residence in Palmas del Mar is currently marketed with four bedrooms, four bathrooms, and approximately 3,775 square feet. New-construction timing, completion, appraisal, insurance, and community requirements should be verified for the selected loan.
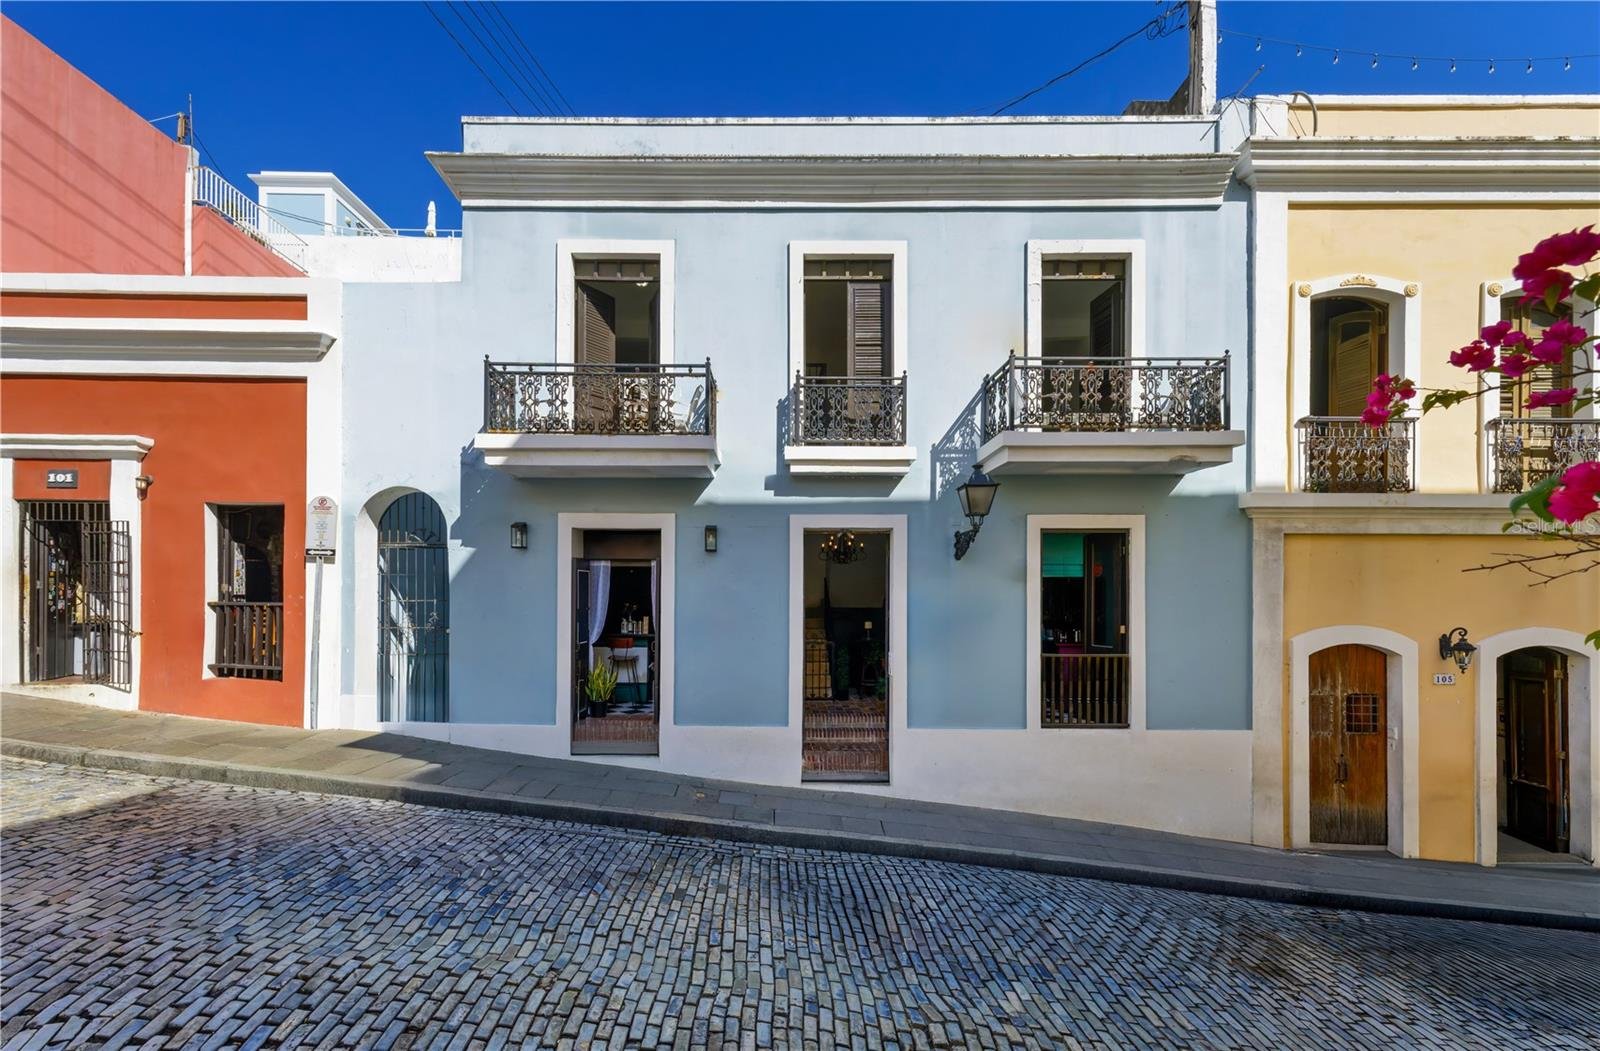
103 Cristo Street, San Juan, PR 00901
This Old San Juan property is currently marketed as a mixed-use, multi-family building of approximately 12,646 square feet. Mixed-use income, leases, permitted use, condition, title, and appraisal can require a different financing analysis from an owner-occupied home.
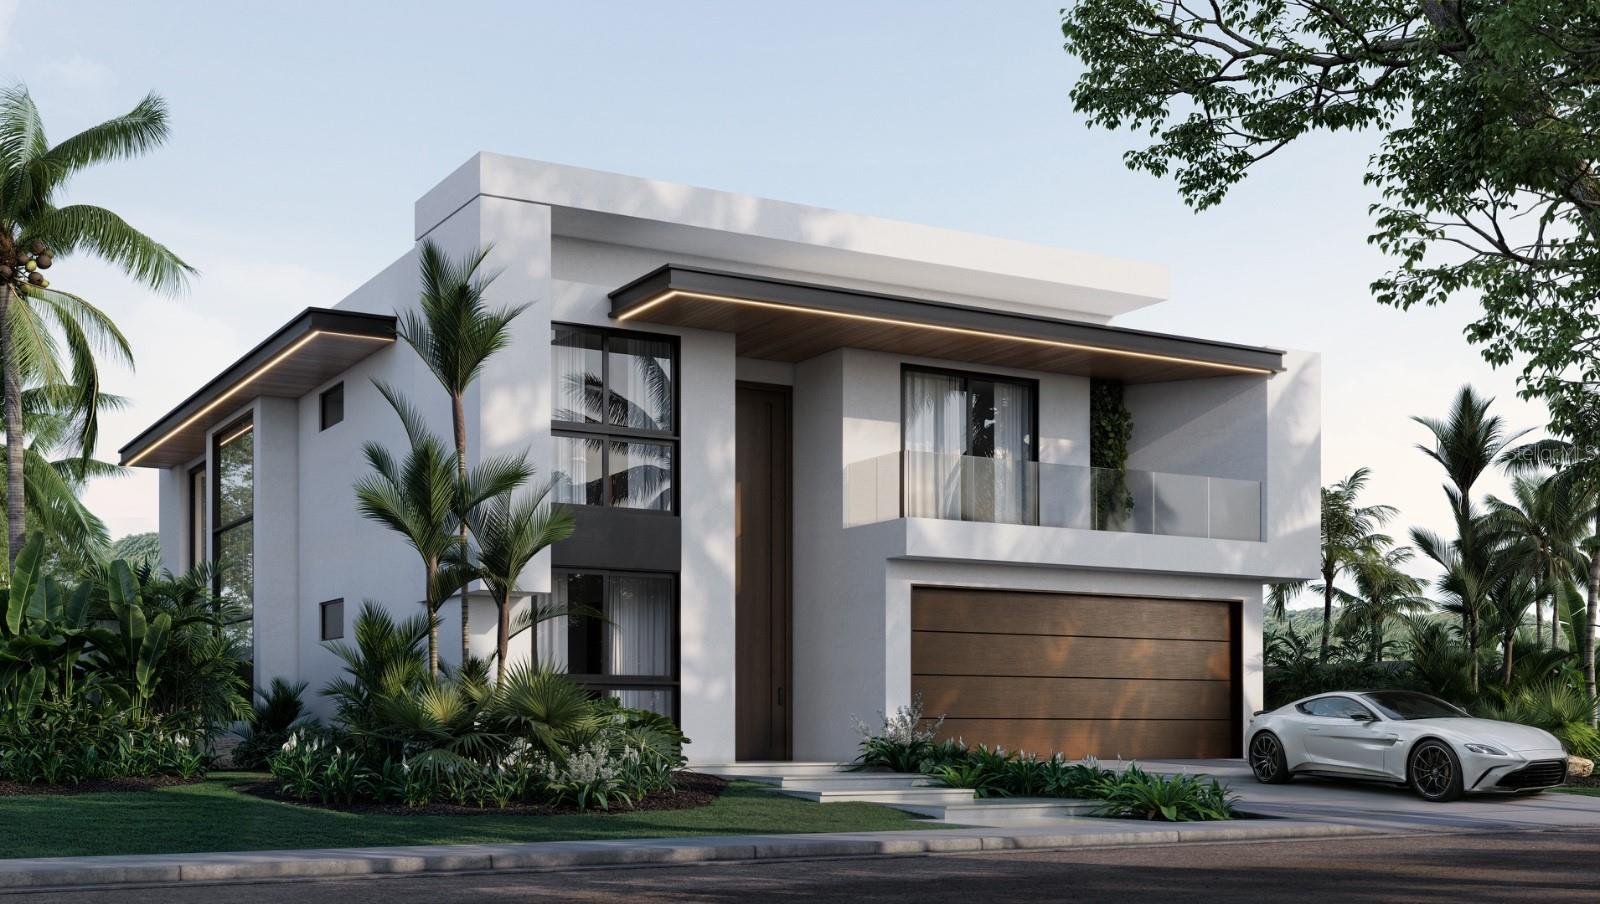
47 Sereno, Guaynabo, PR 00969
This Guaynabo residence is currently listed with four bedrooms, five bathrooms, and approximately 5,000 square feet. Buyers should confirm construction status, appraisal, insurance, HOA obligations, reserves, and loan-program eligibility before relying on projected financing.
Conclusion
Puerto Rico buyers can compare conventional, FHA, VA, USDA, non-QM, portfolio, and cash-plus-financing structures, but no single option is best for every borrower or property. Begin with intended use and complete financial documentation, then compare written terms and complete title, appraisal, insurance, permit, and property-specific due diligence.
Christie’s International Real Estate Puerto Rico can help buyers identify current properties for sale that fit their location and lifestyle goals. Financing approval and advice should come from qualified lenders, attorneys, tax professionals, and other advisers familiar with the buyer’s circumstances.
FAQs
Can I buy a house in Puerto Rico with no credit score?
Possibly, but approval is not guaranteed. Some FHA and VA underwriting pathways permit verified nontraditional credit or alternative payment histories when a borrower lacks a traditional score; the borrower must still meet the program and lender’s income, debt, asset, occupancy, and property requirements.
Can I use an FHA, VA, or USDA loan for a Puerto Rico investment property?
These programs generally require the financed home to be the borrower’s principal residence and impose program-specific eligibility rules. A multi-unit owner-occupied property may be treated differently from a vacation home or property purchased solely for rental income, so confirm the exact scenario with an approved lender.
Do all Puerto Rico mortgage lenders require the same credit score?
No. Government program rules and lender overlays are not the same, and conventional, portfolio, and non-QM lenders establish different underwriting standards. Compare lenders that originate the relevant Puerto Rico loan type and ask for requirements in writing.
Should an investor buy Puerto Rico real estate through an LLC?
An LLC may be appropriate in some transactions, but it can affect financing, liability, taxes, insurance, title, and lender eligibility. Review the ownership and loan structure with Puerto Rico legal and tax advisers before signing a purchase agreement or transferring property.