Puerto Rico's Act 60 Individual Resident Investor rules changed in 2026. The amended Incentives Code distinguishes applications filed by December 31, 2026, from those filed on or after January 1, 2027, for specified investment income. For a property buyer, the most immediate question is not whether a home itself earns a special tax rate, but whether the purchase satisfies the decree's primary-residence conditions.
This guide explains the current filing dates, home-purchase rules, residency tests, and planning questions. It is general information, not tax or legal advice; an eligible person's decree and circumstances control the outcome.
Key Takeaways
- The 2026 amendment makes the filing date—not the approval date—the key dividing line for the new investment-income rules.
- The law generally sets a 4% Puerto Rico rate for specified income of applicants filing from January 1, 2027.
- An individual investor must acquire a qualifying Puerto Rico primary residence within two years after the decree.
- U.S. bona fide residency involves presence, tax-home, and closer-connection tests; 183 days is not a universal shortcut.
- Act 60 does not automatically exempt gains from selling a Puerto Rico home or waive normal buying costs.
Key Act 60 Rule Changes for Property Investors
Act 38-2026 amended the Puerto Rico Incentives Code, extending parts of the individual-investor framework while changing the treatment of later applications. Buyers should separate the tax rules for qualifying investment income from the separate requirement to own and use a Puerto Rico primary residence.
Tax Rate Structure Changes
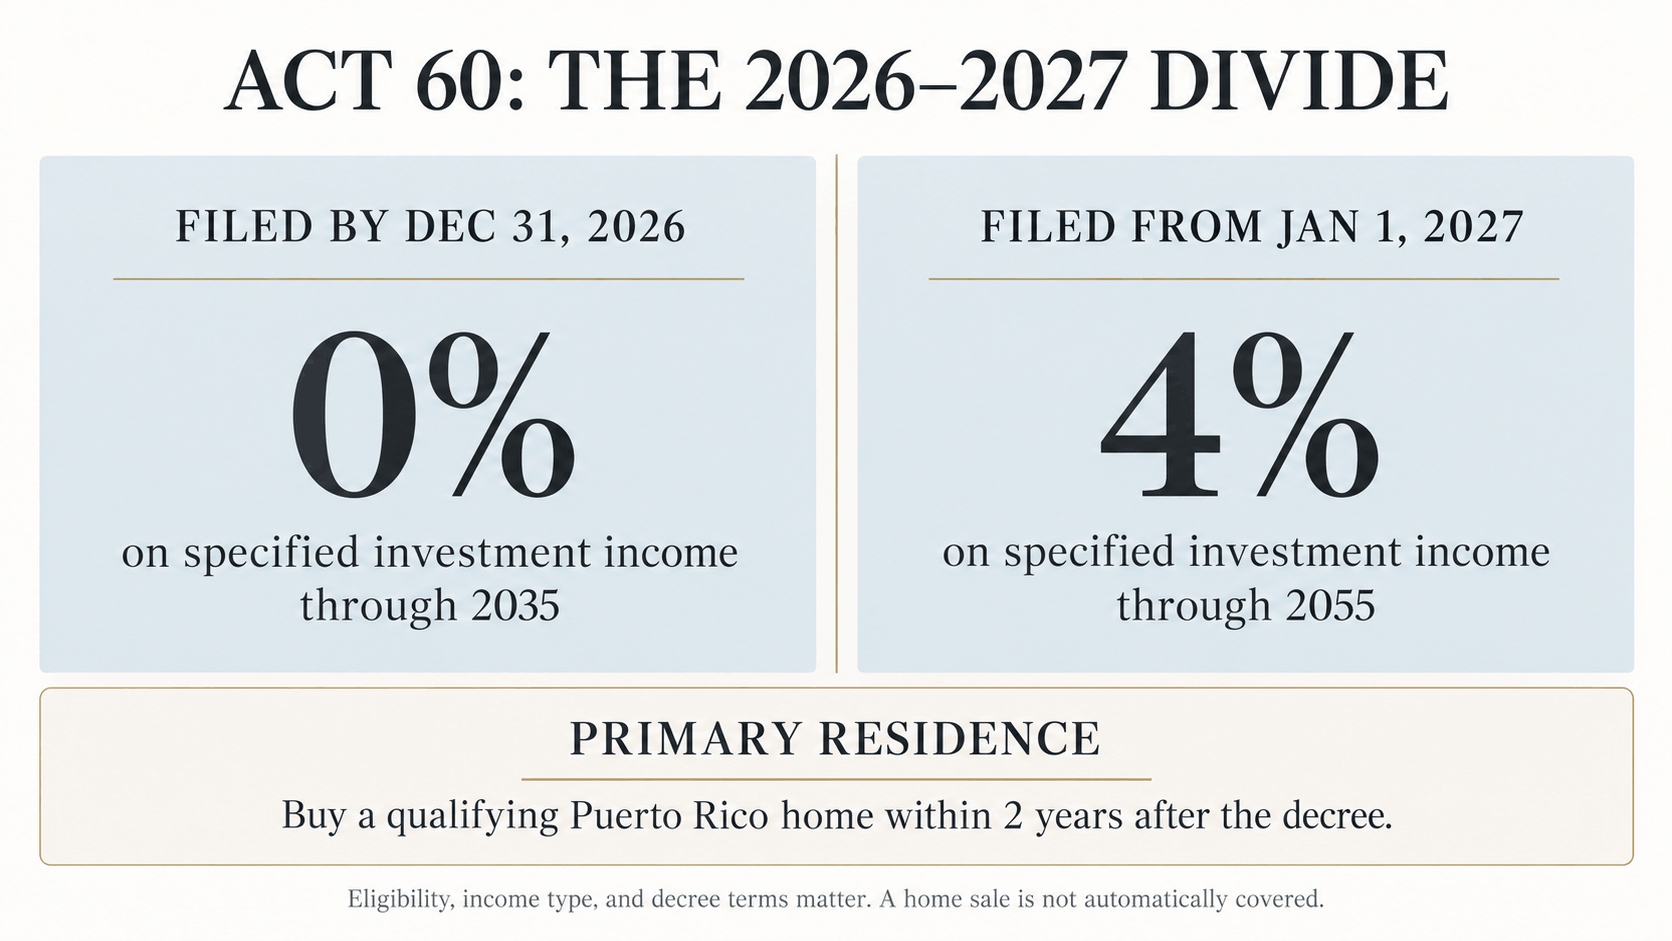
Under Sections 2022.01 and 2022.02, applications filed by December 31, 2026, generally retain the existing Puerto Rico treatment for specified interest, dividends, and covered post-residency appreciation through 2035, subject to the decree and statutory conditions. Applications filed from January 1, 2027, generally face a 4% Puerto Rico rate on the covered categories through 2055, unless a more favorable applicable rule applies. Appreciation accrued before Puerto Rico residency is treated separately; do not assume the headline rate applies to the entire gain.
These are individual-investor provisions. They are not a blanket 4% rate for every business, rental payment, or sale of Puerto Rico real estate.
Property Purchase Timeline Requirements
The Code requires an individual resident investor to buy a Puerto Rico primary residence from an unrelated seller within two years after the decree and maintain the required ownership during its term. For applications filed from 2027, the amended ownership language specifies the individual, the individual jointly with a spouse, or a qualifying trust; buyers should confirm title structure with Puerto Rico counsel before closing.
- Check the decree issue date against the two-year purchase deadline.
- Confirm that the home will actually serve as the principal residence.
- Review title, financing, insurance, flood exposure, and carrying costs independently of any tax incentive.
Tax Terms and Deadlines Under Updated Act 60
The 2026 change turns on when a qualifying application is filed. Approval, continued compliance, the source and timing of income, and the decree's own terms still matter, so a filed application is not a promise of a particular tax outcome.
- Filed by December 31, 2026: review the existing statutory treatment and the decree's duration; do not assume automatic benefits through 2055.
- Filed from January 1, 2027: assess the 4% rules for covered investment income and the updated six-year look-back.
- Existing decree: have an adviser read the actual decree before assuming its rate, expiration date, or renewal terms changed.
The official consolidated Code is the starting point for these comparisons. A Puerto Rico tax adviser can model the interaction with U.S. federal rules before a buyer commits to a home.
Residency, Look-Back, and Donation Requirements
Act 60 eligibility is tied to genuine Puerto Rico residence and continuing compliance, not merely ownership of local property. The amended Code also changes the prior-residency look-back for later applicants, while the IRS applies a separate bona fide-residence analysis for U.S. tax purposes.
Physical Presence Standards
The IRS territory-residency guidance explains that bona fide residence generally requires a presence test, a Puerto Rico tax home, and no closer connection to the United States or another country. Spending at least 183 days in Puerto Rico is one way to meet the presence test, not the sole test or a substitute for the other two. Keep travel and home-use records and obtain individual advice for transition years.
Updated Charitable Contribution Framework
For Individual Resident Investors, the Code calls for evidence of at least $10,000 in annual donations to qualifying Puerto Rico nonprofits beginning with the second tax year after receiving the decree. The allocation and eligible recipients require close attention to the governing provisions and the decree; do not assume a fixed split without checking the current requirements.
Grandfathered Decrees vs New Applicants
An existing decree and a new application are not interchangeable. The filing-date rules identify categories of applicants, but an investor must still check the text, effective dates, and remaining term of the particular decree.
Existing Decree Holder Advantages
Current decree holders should have counsel verify their covered income, expiration date, annual reporting, donation obligations, and property conditions. Do not infer that the program's 2055 endpoint automatically extends an earlier individual decree or its original tax treatment.
New Applicant Considerations
A prospective applicant should map the proposed move, income sources, and home acquisition against the current law. The six-year nonresidency look-back for applications filed from 2027 can affect eligibility even when a buyer is otherwise ready to relocate.
Application Timing Strategies
A December 2026 filing may fall under different statutory rules from a January 2027 filing, but timing alone does not establish eligibility. Confirm the submission requirements, decree terms, and genuine residency with qualified counsel; do not rush a property purchase solely to chase a rate.
Implications for Property Acquisition and Exit Strategies
The home purchase should be evaluated as a real-estate decision as well as a compliance requirement. Compare neighborhoods, title and condo documents, insurance, financing, carrying expenses, and likely resale demand without treating the Act 60 decree as a guarantee of appreciation.
Acquisition Strategy Adjustments
Build a purchase schedule around the decree's two-year window, but retain normal due diligence and contingencies. Buyers considering Puerto Rico new construction should verify delivery dates, deposits, ownership structure, and whether the finished home can meet their actual primary-residence needs.
Exit Planning Under Modified Terms
The rate on qualifying investment appreciation should not be applied automatically to a sale of Puerto Rico real property. Tax treatment can depend on the asset, sourcing, holding period, pre-residency appreciation, and decree language. Before listing, ask Puerto Rico and U.S. tax advisers to model the actual transaction rather than relying on a generic 0% or 4% property-sale table.
Market Outlook for Act 60 Property Investors
Act 60 may be one factor in a buyer's decision, but the 2026 amendment alone does not prove that luxury prices or demand will rise. Local inventory, financing, insurance, property condition, and neighborhood-specific supply are more useful inputs when judging a purchase.
- Compare current asking prices with recent comparable sales.
- Budget for insurance, maintenance, taxes, and association fees.
- Confirm practical fit for full-time residence, not just investment appeal.
Strategic Recommendations for Different Investor Profiles
The right sequence differs for an existing decree holder, a 2026 applicant, and a later applicant. In each case, legal and tax eligibility should be assessed separately from whether a particular home is a sound purchase.
Current Decree Holders
Review your own decree and annual reporting before assuming an amendment changes your benefit or term. If buying another property, check whether your current residence obligations remain satisfied.
Prospective Pre-2027 Applicants
Confirm that you can file a complete application before the statutory cutoff and independently satisfy residency and home-purchase conditions. A qualifying filing is not the same as an approved decree.
Future Post-2027 Applicants
Model the 4% treatment only for income actually covered by the amended statute. Check the six-year look-back and ownership structure with advisers before acquiring a residence.
Luxury New Construction Properties for Sale in Puerto Rico
Luxury new construction may suit buyers seeking a long-term Puerto Rico residence, but a development's presence here does not establish Act 60 eligibility. Verify current availability, completion status, and each home's suitability as a principal residence with the brokerage and your advisers.
The Icon
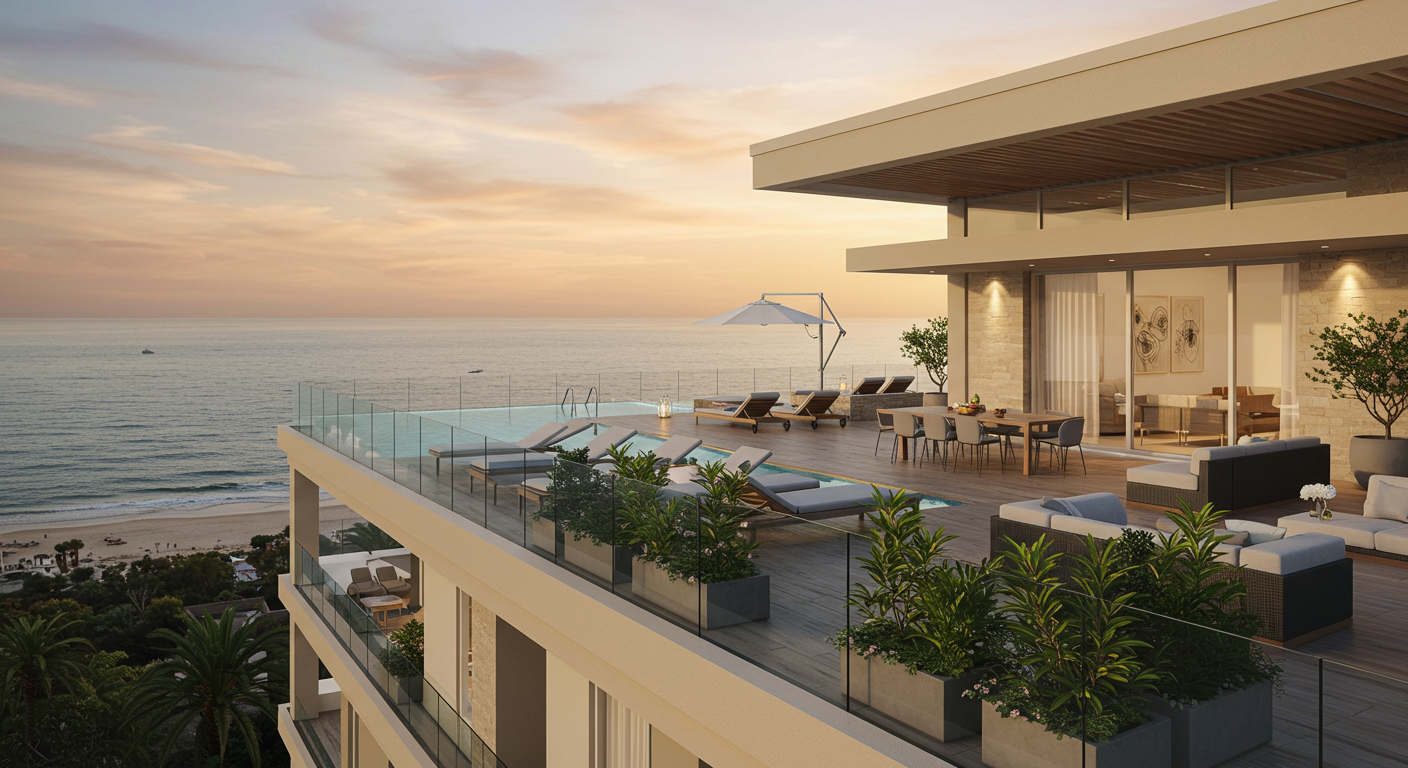
The Icon is a Condado condominium development one block from the beach, with views toward Condado Beach and Lagoon. Its official page currently shows residences for sale; confirm unit-specific availability and closing terms before making plans.
Vanderbilt Residences
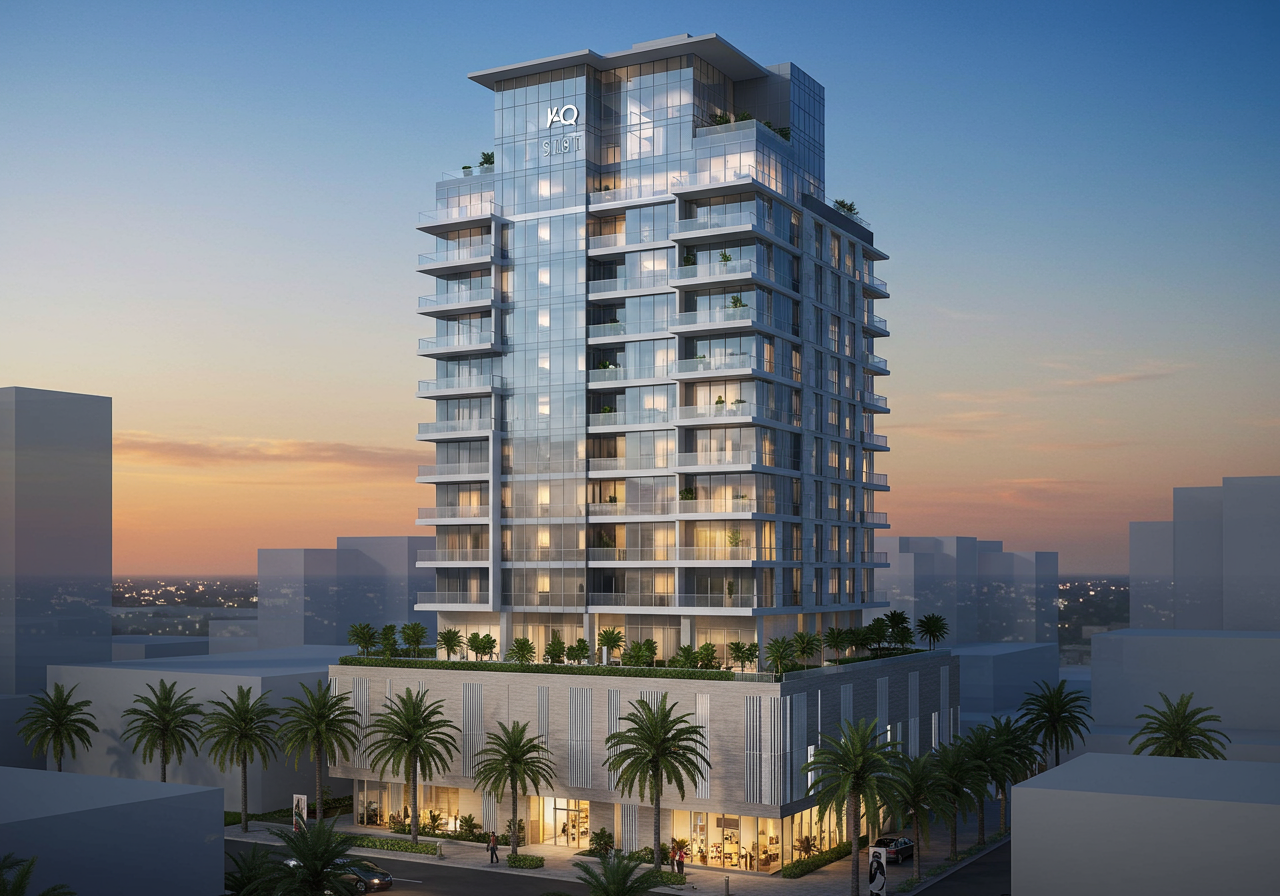
Vanderbilt Residences is an oceanfront Condado development with residences ranging from one to five bedrooms. Its official page currently displays units for sale; ask for current inventory and association details.
The Ritz-Carlton Reserve La Cala Residences
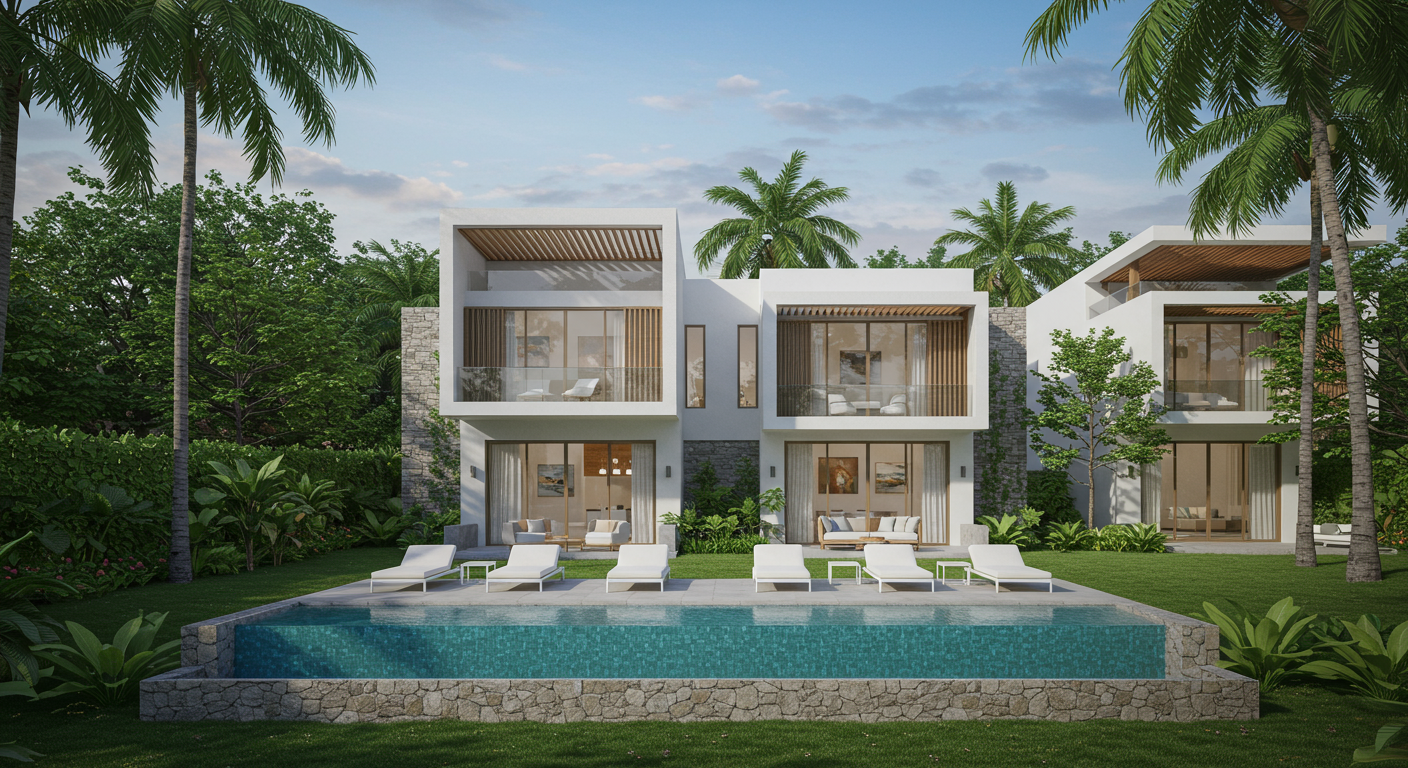
La Cala is a beachfront residential development at Dorado Beach, with 14 planned estates across five models. The official page says lots 1–5 are selling; confirm availability and project milestones directly.
Conclusion
The 2026 Act 60 amendments make the application filing date and covered income categories especially important. A Puerto Rico home is a distinct purchase and residency obligation, not an automatic tax-exempt investment. Buyers should coordinate property due diligence with individualized Puerto Rico and U.S. tax advice before relying on any projected benefit.
If you want to rent, buy, or sell luxury property in Puerto Rico, Christie's International Real Estate Puerto Rico is here to guide your search and transaction. Explore Puerto Rico luxury properties and speak with our team about homes that fit your goals.
FAQs
These answers address common planning questions, but a decree and the facts of a specific transaction determine tax treatment.
Does Act 60 waive Puerto Rico closing costs?
No automatic waiver follows from the Individual Resident Investor provisions. Obtain a transaction-specific estimate of notary, registry, financing, and other closing expenses.
Can an Act 60 primary residence be rented out?
Rental use can undermine a primary-residence position, depending on the facts and decree. Ask local counsel to review any proposed lease or short-term rental plan before offering the home.
Does the 4% rate apply to a Puerto Rico home sale?
Not automatically. The 4% provision concerns specified investment income and covered appreciation; a real-estate sale requires a separate tax analysis.
Is 183 days in Puerto Rico enough for bona fide residence?
Not by itself. The IRS also examines tax home and closer connection, and presence can be met through more than one route.
What changed for applications filed in 2027?
The amended Code generally applies a 4% Puerto Rico rate to specified investment income and a six-year prior-nonresidency look-back for applications filed from January 1, 2027, subject to the law and decree terms.
Related Articles
For more context on the tax amendment and property planning, see these Christie’s guides.