For Miami investors comparing Act 60 in Puerto Rico with Florida residency, the important question is how each option affects their actual income, housing costs, and ability to relocate. Florida does not impose personal income tax, while Puerto Rico's Individual Resident Investor program can provide preferential Puerto Rico treatment for qualifying income under an approved decree. Federal tax rules, income sourcing, and ongoing compliance must be evaluated separately before estimating savings.
For high-net-worth investors, a home purchase should support the proposed move rather than substitute for a tax analysis. The comparison below focuses on the 2026 rules and the practical decisions involved in buying Puerto Rico luxury real estate.
Key Takeaways
- Florida's absence of personal income tax does not remove federal tax obligations.
- Act 60 benefits depend on eligible income, residency, and decree terms.
- Application timing affects the available Puerto Rico tax framework.
- Property costs and rental income require separate, property-specific analysis.
- Coordinate the relocation, decree, and home-purchase timelines before committing.
Puerto Rico Act 60 vs Florida: How Taxes Differ
A useful Puerto Rico vs Florida tax comparison separates state or territory taxation from U.S. federal obligations. A preferential Puerto Rico rate is not a promise that every dollar of an investor's income becomes exempt from federal tax.
The Florida Department of Revenue confirms that Florida imposes no personal income tax. Act 60, by contrast, requires an eligibility and decree analysis rather than merely choosing a Puerto Rico address.
Capital Gains Tax Comparison
The IRS capital gains guidance distinguishes short-term and long-term gains, with most long-term gains subject to federal rates of 0%, 15%, or 20% depending on taxable income. Short-term gains generally use ordinary income rates; additional tax can apply depending on the asset and circumstances.
The amended Puerto Rico Incentives Code distinguishes Individual Resident Investor applications filed on or before December 31, 2026 from those filed beginning January 1, 2027. For qualifying interest, dividends, and post-residency appreciation, the earlier framework provides a Puerto Rico exemption through 2035, while the later framework generally applies a 4% Puerto Rico rate through 2055, subject to statutory conditions. Pre-residency appreciation has separate rules.
Federal tax treatment depends on bona fide residency, income source, and applicable exceptions. For example, a gain on U.S. real property does not become Puerto Rico-source income simply because its owner moves; have an adviser analyze the asset and ownership history before a sale.
DDEC's 2026 investor-program bulletin explains that eligible existing holders may request a modification for the longer framework. An approved extension entails the corresponding rate change; existing zero-rate treatment is not automatically extended through 2055.
Property Taxes and Ownership Costs
Do not assume an Individual Resident Investor decree makes a personal home property-tax exempt or cheaper to carry than a Miami property. Compare the actual assessment, applicable exemptions, insurance, association charges, maintenance, and financing for each candidate home.
Request current property-tax documentation and property-specific insurance quotes, and distinguish those amounts from a listing website's mortgage-calculator estimates. A lower purchase price or one favorable tax item can be offset by other ownership expenses.
Category | Florida resident | Puerto Rico investor-decree applicant |
|---|---|---|
Personal income tax | No Florida personal income tax | Assess eligible income and the applicable decree framework |
Federal income tax | Federal rules continue to apply | Evaluate residency, sourcing, and exceptions separately |
Property carrying costs | Use the specific home's documented expenses | Use the same property-level budgeting process |
Estate planning | Review ownership and succession arrangements | Review cross-jurisdiction ownership and succession with counsel |
Act 60 Residency and Compliance: What to Verify
Federal bona fide residency and Puerto Rico decree eligibility are related but distinct assessments. Establish a documented plan for both before relying on an expected tax outcome.
- Review the presence, tax-home, and closer-connection tests in IRS Publication 570. Spending 183 days on the island is a commonly discussed route through the presence test, not a substitute for the other tests; exceptions and alternative presence rules may apply.
- Check prior-residency eligibility for the correct application cohort: DDEC distinguishes the January 17, 2006–January 17, 2012 exclusion for pre-2027 applications from a six-year period before relocation for post-2026 applications.
- Confirm the principal-home acquisition deadline and evidence required by the decree. For post-2026 applications, DDEC specifies title in the individual's name, jointly with a spouse, or through a qualifying grantor trust; do not assume an LLC satisfies the requirement.
- Review annual donations, reporting, and evidence under the decree and DDEC compliance guidance. Do not assume one donation amount or recipient allocation applies to every legacy and current decree.
- Retain travel records and supporting household, business, and financial documentation. Have qualified advisers identify filing obligations and how each income source is treated.
A home purchase alone does not establish tax residency, approve a decree, or convert ordinary rental income into exempt investment income. These distinctions matter when a property is being purchased partly for personal use and partly for letting.
Real Estate Investment Opportunities Under Act 60
Puerto Rico offers different housing choices for a relocation, including urban condominiums, resort-community homes, and coastal residences. Assess the property on its own merits alongside the proposed tax plan, rather than assuming a luxury address guarantees program eligibility or investment returns.
Direct ownership also adds responsibilities that differ from securities or fund holdings. The comparison of portfolio diversification options can help frame those differences without treating either approach as universally better.
Market Evidence to Review
Replace broad claims about Puerto Rico outperforming Florida with current comparable sales and property-level evidence. Neighborhood, building condition, permitted use, insurance exposure, and the expected holding period can matter more than island-wide headlines.
- Separate asking prices from completed sales and compare similar homes.
- Review recent inspections, maintenance history, and association budgets or assessments.
- Model rental income after vacancy, management, repairs, utilities, insurance, and taxes.
- Confirm rental permissions and any restrictions on personal or investment use.
Buyers considering construction should also compare building versus buying, including permitting, infrastructure, and the risk of delays.
Financing and Acquisition Strategies
Obtain financing terms, a title review, insurance quotes, and an inspection before committing to a purchase budget. Confirm that the proposed ownership structure is compatible with the applicable residence requirement rather than selecting an entity solely for assumed tax savings.
The overview of Act 60 property considerations provides additional context for the real estate side of a move. Have tax and legal advisers assess the specific transaction, including any intended rental activity.
Wealth and Transition Plan
A workable relocation plan coordinates tax advice with the timing and practical demands of a household move. Build the comparison around documented costs and realistic personal commitments.
- Model Florida and Puerto Rico scenarios using the same assets, income categories, and time horizon.
- Confirm eligibility, application timing, and the consequences of any decree modification.
- Map work, travel, family, and recordkeeping arrangements against residency requirements.
- Set a home budget covering acquisition, insurance, maintenance, and contingency funds.
- Review title structure, intended occupancy, and purchase deadlines with counsel.
- Test the location against healthcare, education, transport, and everyday services.
Puerto Rico vs Florida: Investor Snapshot
The decision extends beyond a headline income-tax rate. Use this comparison to identify the questions a household needs to resolve before choosing a property or relocation date.
Decision | Puerto Rico | Florida |
|---|---|---|
Tax planning | Analyze decree eligibility and federal sourcing together | Evaluate federal treatment despite no state personal income tax |
Housing | Check residence requirements, title, and everyday suitability | Check intended occupancy and household needs |
Financial comparison | Include compliance and relocation expenses | Include actual housing and ownership expenses |
Investment risk | Verify local comparables and property-specific risks | Apply the same evidence standard to the relevant local market |
Long-term fit | Assess the ability to maintain the required move and records | Assess family, business, and lifestyle priorities |
Luxury Properties for Sale in Puerto Rico
Christie's International Real Estate Puerto Rico presents luxury properties for sale across urban, resort, and coastal settings. These four listings provide different starting points for a property search. Confirm current availability and obtain independent advice on suitability for a principal residence or any proposed investment use.
1858 Mcleary, San Juan, PR
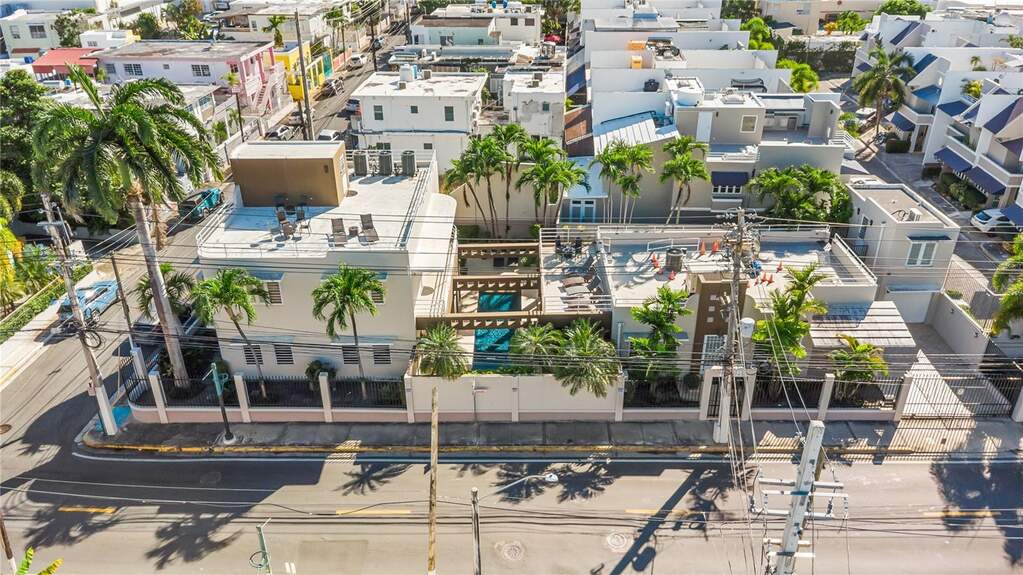
This Ocean Park-area property is offered for sale with multiple residential units totaling five bedrooms and six bathrooms. Its description includes a pool, rooftop terraces, and backup water and power systems.
3307 Ave Isla Verde PH, Carolina
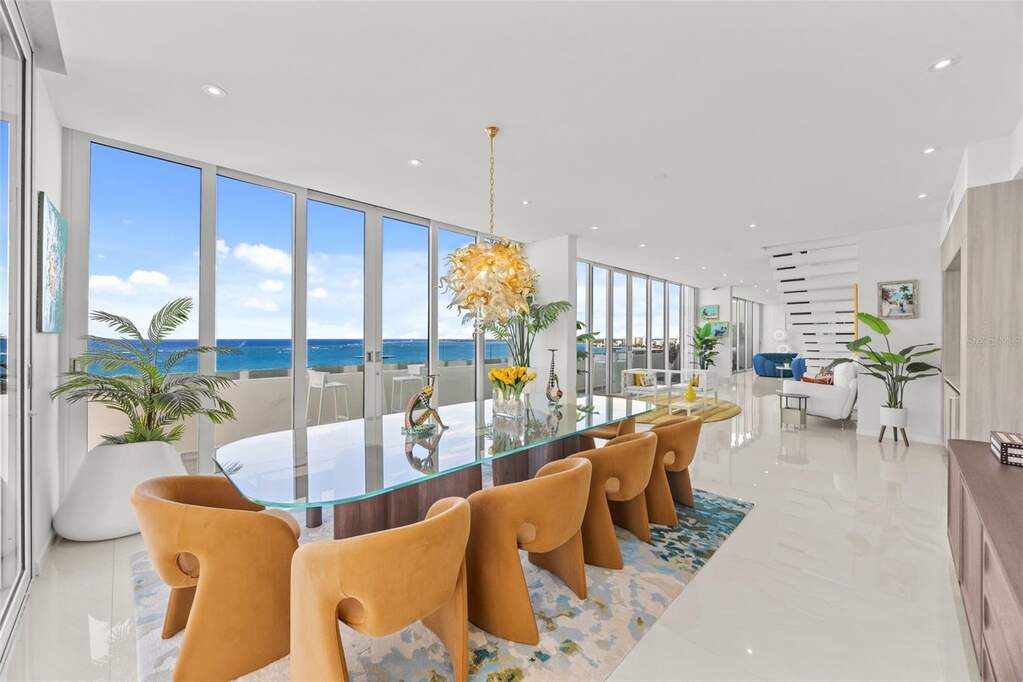
This Isla Verde penthouse is offered for sale with approximately 6,370 square feet of living area. The description includes covered and uncovered terraces, ocean and city views, and five private parking spaces.
800 The Redonda Estate, Dorado
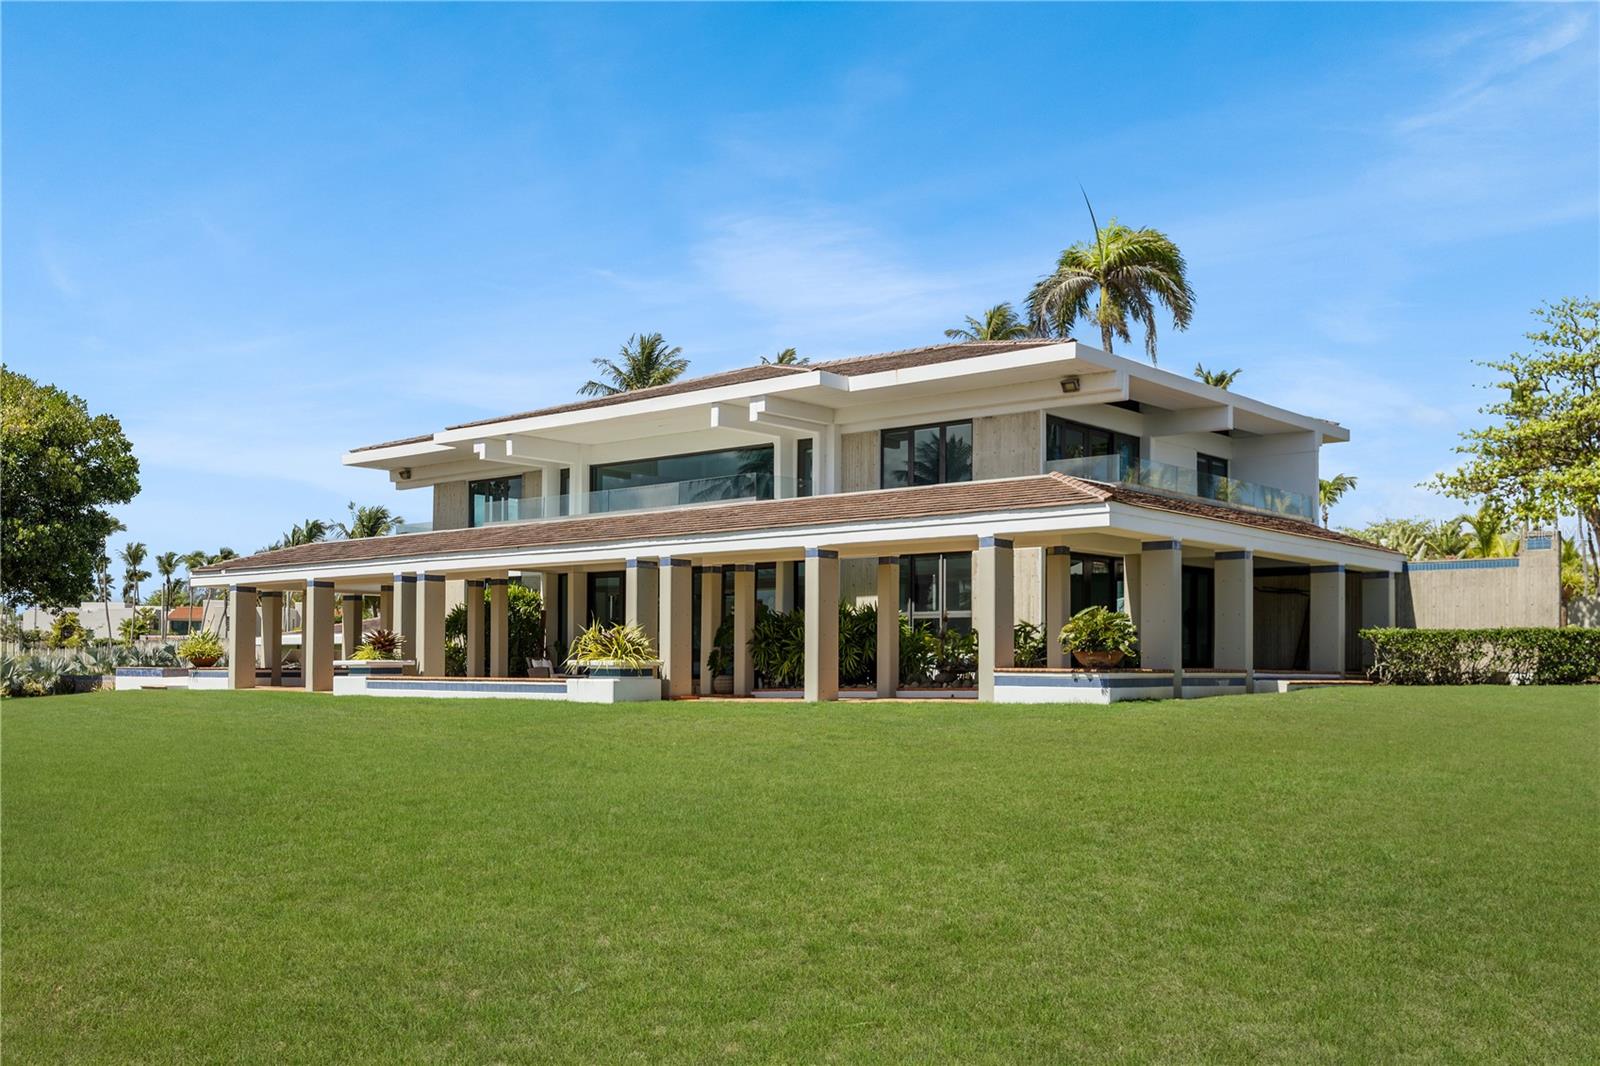
This active Dorado Beach Resort listing occupies more than three acres overlooking Mata Redonda Lagoon and the West Golf Course. It includes a main residence, separate guest house, infinity-edge pool, water cistern, and diesel backup generator.
Lot 4 Ibiza Street, Aguadilla
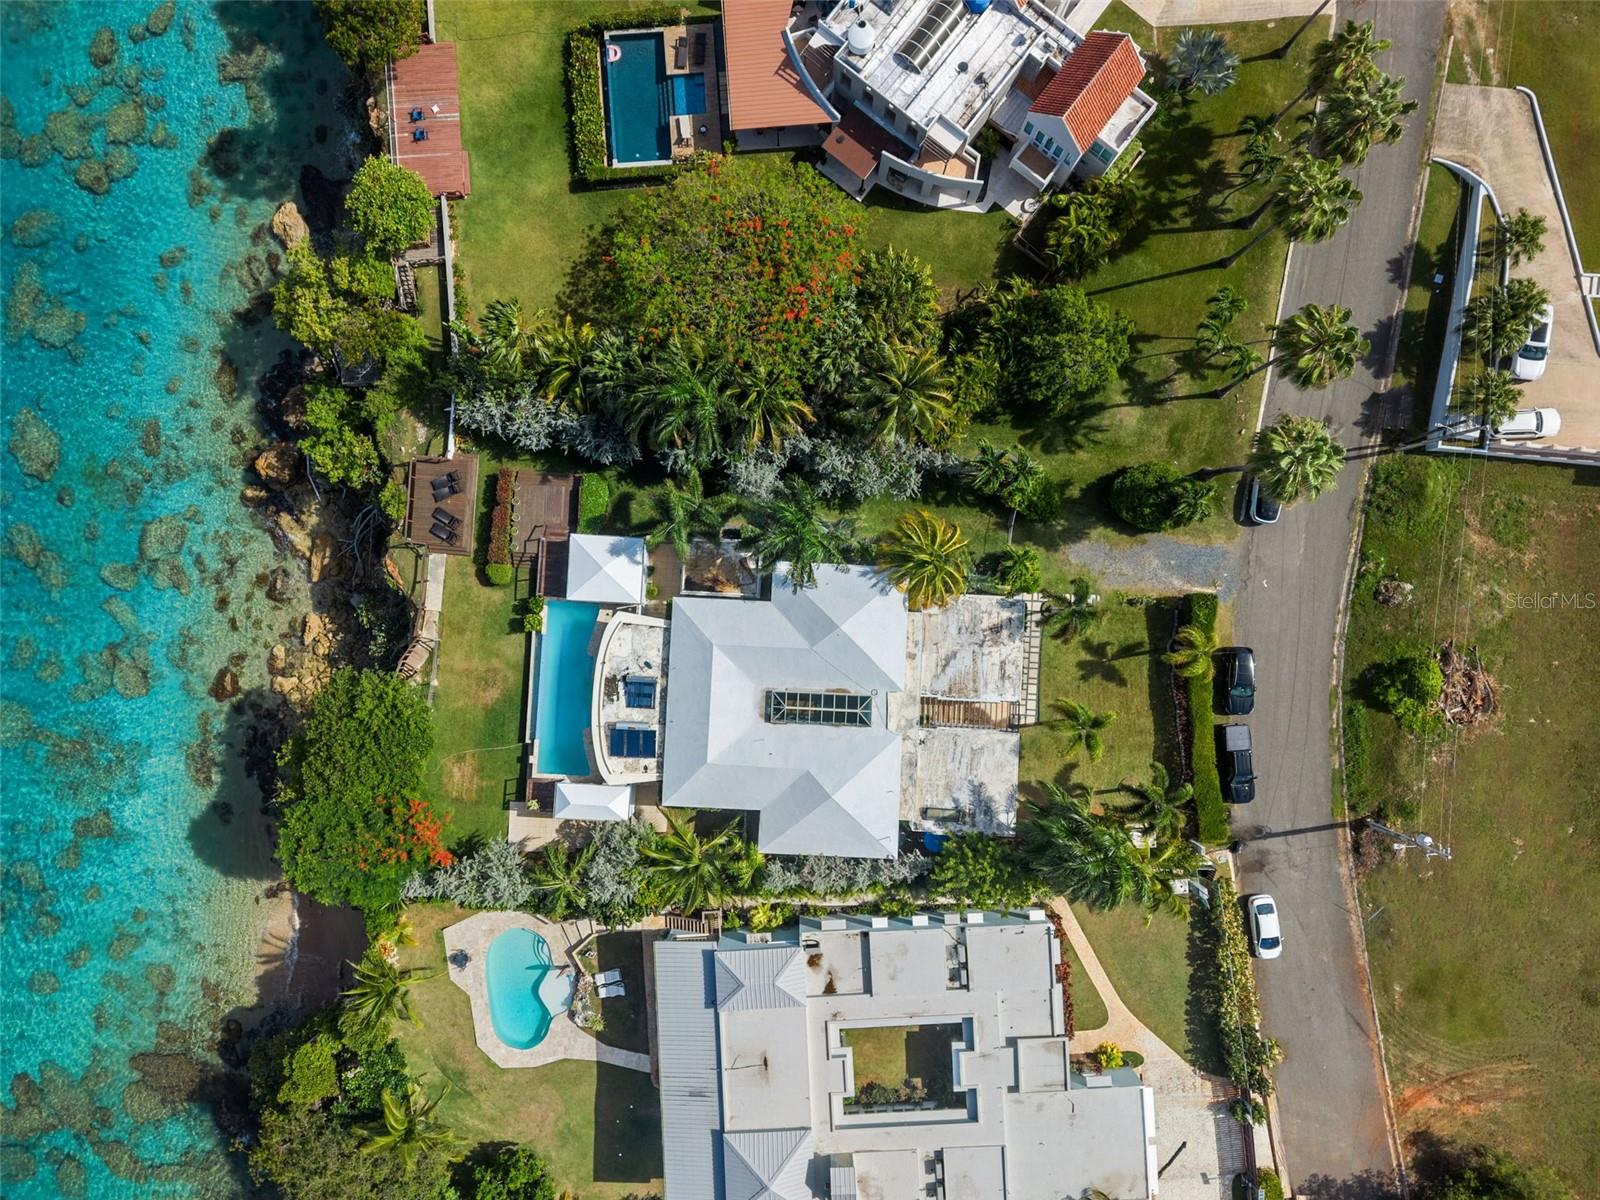
This active Aguadilla listing, described as Villa Flamboyán, offers five bedrooms and approximately 3,751 square feet of living space. Its cliffside setting includes ocean views, terraces, and an infinity pool.
Conclusion: Choosing a Tax and Property Strategy
Act 60 can be relevant to a Miami investor's relocation decision, but its value depends on eligible income, federal tax rules, and sustained compliance. Compare those factors with the actual costs and practical demands of living in either jurisdiction. Select a property for its condition, location, ownership requirements, and household fit rather than an assumed tax outcome.
If you want to rent, buy, or sell luxury property in Puerto Rico, Christie's International Real Estate Puerto Rico is here to guide you. Explore Puerto Rico luxury properties and speak with our team about your real estate plans.
FAQs
These answers address common issues in the Florida-to-Puerto Rico comparison. Confirm the application cohort, decree terms, and treatment of specific assets with qualified advisers.
Is Act 60 better than Florida residency for every investor?
No single answer applies to every household. Income sourcing, asset history, compliance costs, and the ability to make the required move affect the comparison, alongside housing and lifestyle needs.
Does buying a Puerto Rico home establish tax residency?
A property purchase alone does not satisfy federal bona fide residency or guarantee decree approval. Review the residency tests, eligibility, and the applicable primary-home requirements as separate parts of the plan.
Are Puerto Rico property taxes always lower than Florida's?
Use actual assessments, exemptions, and ownership expenses for the homes being compared. Broad percentage ranges do not establish which property will cost less to own.
Does an investor decree automatically exempt rental income?
Do not assume that treatment. Rental operations, capital gains, and passive investment income require their own analysis under the applicable law and decree.
Related Articles
Continue reviewing decree suitability, location choices, and the distinction between housing and residency with these guides.