Closing costs in Puerto Rico—gastos de cierre en Puerto Rico—depend on the property, the documents required, your financing, and the allocation negotiated in the purchase contract. For an elite property, an itemized estimate is more useful than a single percentage of the purchase price. Separate closing fees from your down payment, prepaid expenses, and money already deposited.
This guide explains the main charges, compares cash and financed purchases, and shows how to build a budget without counting the same expense twice. Legal and financial sources checked September 15, 2026; this is general information, not an individual closing quote or legal or tax advice.
Key Takeaways
- Obtain written, itemized quotes; there is no single closing-cost percentage that fits every luxury purchase.
- Notarial fees follow statutory rules; stamps and Property Registry charges are separate items.
- A mortgage can add lender charges, mortgage-deed costs, an appraisal, prepaids, and escrow funding.
- Confirm association balances, assessments, insurance, and the buyer/seller allocation before calculating cash to close.
Closing Costs (Gastos de Cierre) for Luxury Properties: The Master Breakdown

Build your estimate around the actual transaction. A cash purchase eliminates loan-specific charges, but it still requires a review of title, deed expenses, applicable government charges, and property condition. Some due-diligence bills are paid before closing; record those payments so they are not charged again in your final funds calculation.
1) Professional Fees That Drive Luxury Closings
A Puerto Rico notary is an authorized legal professional acting impartially in the notarial function. Under Article 77 of the Puerto Rico Notarial Act, instruments valued above $10,000 through $5 million generally carry agreed fees between 0.50% and 1%, with a $250 minimum. Above $5 million, that bracket applies to the first $5 million; fees on the excess are agreed with the notary. Special rules and exceptions can apply.
Ask for a written breakdown by instrument and for separate identification of additional legal services. Do not assume the sale deed, mortgage deed, title investigation, and independent buyer representation are all included in one fee. A separate buyer’s attorney can review the contract and ownership structure; obtain a scope and quote rather than using an unsupported island-wide flat fee.
Title work and title insurance are also distinct. A title examination identifies recorded ownership, liens and restrictions; insurance covers specified risks subject to policy terms and exceptions. Request separate owner’s and lender’s policy quotes, identify the insured amounts and endorsements, and ask whether any simultaneous-issue pricing applies.
2) Government Fees: Stamps, Registry, and Transfer Items
Request separate lines for deed stamps, certified-copy charges, presentation, and registration. The Colegio Notarial’s list of stamps and vouchers identifies different charge categories; they should not be replaced with a universal “transfer tax” percentage.
Under the Property Registry tariff amended by Law 209-2015, registration of a right valued above $25,000 generally uses $50 for the first $25,000 plus $4 per additional $1,000 or fraction, with a separate $15 presentation fee per document. Have the notary confirm the applicable valuation basis, rights, documents, and exemptions. A mortgage or cancellation may create additional charges.
Property-tax balances and closing prorations are separate from deed stamps. Request current CRIM records, confirm any exemption status, and document which party pays outstanding taxes and adjustments. Do not count Registry charges both within a combined filing allowance and again as a separate line.
3) Due Diligence and Luxury-Specific Requirements
- Survey or boundary work where needed: obtain a quote based on the parcel and scope.
- Home inspections and specialist reports: consider structure, roof, pool, electrical systems, generator, water storage, and corrosion exposure as relevant.
- Permit and environmental review: identify existing approvals and any proposed changes before commissioning reports.
- Association documentation: request balances, assessments, transfer charges, prepaid dues, and any membership requirements in writing.
4) Financing Add-Ons (If You’re Not Paying Cash)
Request the lender’s itemized charges for origination, points, underwriting, appraisal, credit checks, and flood determination. Add mortgage-deed expenses and any required insurance or initial escrow deposits. Charges depend on the loan and provider; a loan-to-value assumption is not a financing approval.
Quick Summary: Cash vs. Financed “Cash-to-Close” Buckets
The CFPB distinguishes closing costs from cash to close: closing costs exclude the down payment, while cash to close reflects the amount still payable after loan proceeds, deposits, credits, and adjustments. Keep bills already paid outside closing separate.
- Cash purchase: unpaid purchase price plus unpaid buyer charges and adjustments, less applicable credits.
- Financed purchase: buyer’s remaining equity contribution plus unpaid buyer charges and adjustments, less applicable credits.
- Use the final settlement statement to reconcile every deposit, prepaid item, and credit.
Budget Planner (Luxury Puerto Rico Closing Costs)

Use one row for each charge and record who pays it, whether it is already paid, and whether it is included in another quote. Replace pending amounts with written figures as the transaction progresses.
Cost bucket | How to establish the amount | If financing |
|---|---|---|
Notarial services | Written quote by instrument under the applicable tariff | Add mortgage-deed services; check any special rules |
Separate legal advice | Agreed scope and fee | Check lender or entity-related work |
Title examination and insurance | Itemized search, policy and endorsement quotes | Separate lender policy and any combined pricing |
Deed stamps and certified copies | Document-specific calculation | Additional mortgage documents may apply |
Registry presentation and registration | Tariff calculation for each right and document | Add relevant mortgage filings without duplication |
CRIM and other property adjustments | Current records and contract allocation | Confirm tax amounts used for escrow |
Survey, inspections and permit review | Property-specific scope and provider quote | Identify lender-required work separately |
HOA/condo and club charges | Written balances, assessments and transfer requirements | Avoid counting the same contribution twice |
Insurance and other prepaids | Quoted premium and coverage start date | Add prepaid interest and required escrow funding |
Origination, points and lender services | Not applicable to an all-cash purchase | Use lender disclosures and written terms |
How Much Should You Set Aside?
Add the unpaid costs assigned to you, the down payment or remaining cash price, and applicable adjustments. Subtract deposits and credits only once. Maintain a separate contingency for unresolved items and post-closing needs; the appropriate amount depends on what remains unquoted. A percentage target cannot substitute for this reconciliation.
What Surprises Luxury Property Buyers

A high purchase price does not automatically trigger every inspection, permit, or community charge. Costs arise from the property’s condition, governing documents, proposed use, and transaction requirements. Identify those triggers early.
Stamp Duties, Registry Charges, and Tax Adjustments
Ask the closing team to name the legal basis and calculation for each government charge. Annual CRIM property taxes, documentary stamps, and registration charges are different obligations. An older assessment does not establish a discount on an assumed transfer tax.
If the seller is a nonresident, Hacienda’s guidance on real-estate withholding identifies potential buyer withholding obligations. Have the tax adviser confirm the applicable calculation, payment and reporting process before disbursing proceeds. Withholding is not automatically an additional percentage to add on top of the agreed price.
HOA Reserves and Capital Contributions
Request the association’s current statement, approved assessments, reserve information, transfer charges, and rules for advance dues. Club membership may be separate from property ownership. Do not assume every luxury community requires a $10,000–$50,000 contribution or three to six months of prepaid dues. The governing documents and current written figures should drive the budget.
Environmental and Coastal Compliance
For coastal property, ask the relevant professionals to review flood exposure, drainage, boundaries, existing permits, and any planned construction. Whether a survey, environmental study, or additional permit is needed depends on the parcel and proposed activity; an existing-home purchase should not be assigned a blanket environmental fee.
Obtain insurance quotes early. The OCC explains when a lender must require flood insurance for property in a Special Flood Hazard Area; lenders can also impose coverage requirements under their loan terms. Confirm wind and flood coverage, exclusions, deductibles, effective dates, and whether any repairs are a condition of coverage.
Financing-Related Expenses

Compare lenders using the same purchase price, loan amount, term, and rate-lock assumptions. Review the interest rate and points together with origination charges, third-party services, required reserves, and cash to close. Request written confirmation that the lender can finance the particular property and ownership structure.
Loan Origination and Processing
- Identify points and origination charges separately from underwriting or document fees.
- Ask which services you may shop for and which providers the lender requires.
- Clarify prepaid interest, insurance premiums, initial escrow funding, and any mortgage-insurance requirement.
- Distinguish reserves that must remain in your account from money payable at settlement.
Appraisal and Inspection Costs
A lender’s appraisal estimates value for underwriting; it is not a substitute for an independent inspection. Obtain quotes for each required report and confirm the scope, delivery date, and whether a report can serve more than one purpose. This helps avoid overlapping charges without omitting necessary due diligence.
Pre-Closing Funds Preparation Checklist

Start early, but follow the contract and closing team’s confirmed deadlines rather than a universal 45/30/15-day schedule. Preparing funds is different from wiring them to a third party.
Fund Preparation Timeline
- At contract stage: request the cost allocation, document checklist, financing timeline, and initial itemized estimate.
- During due diligence: obtain title, association, insurance and inspection information; document funding sources and any currency-conversion needs.
- Before closing: reconcile the final figures, confirm loan conditions, review documents, and arrange the final walkthrough close to possession.
- Transfer funds only on the agreed schedule after independently verifying instructions; confirm receipt.
For mortgages covered by the rule, the lender must provide the Closing Disclosure at least three business days before closing. Ask which disclosures apply to your loan; cash purchases and certain other transactions use different documentation.
Follow the CFPB’s closing-funds fraud guidance: verify the recipient and account instructions in person or through a previously established trusted phone number. Do not rely solely on a last-minute email changing wire details.
Required Documentation
Confirm the exact list with your lender and closing professionals. It may include:
- Bank statements showing fund sources
- Wire transfer confirmations after payment
- Currency conversion records if applicable
- Gift documentation if funds are gifted
- Business documentation and signing authority for entity purchases
Contingency Fund Recommendations
- Keep a separate reserve for unresolved quotes or adjustments.
- Prepare separate funds for immediate property needs.
- Consider utility deposits and connection fees.
- Budget for security-system activation if needed.
- Plan for documented repairs or upgrades.
Sample Closing-Cost Calculation
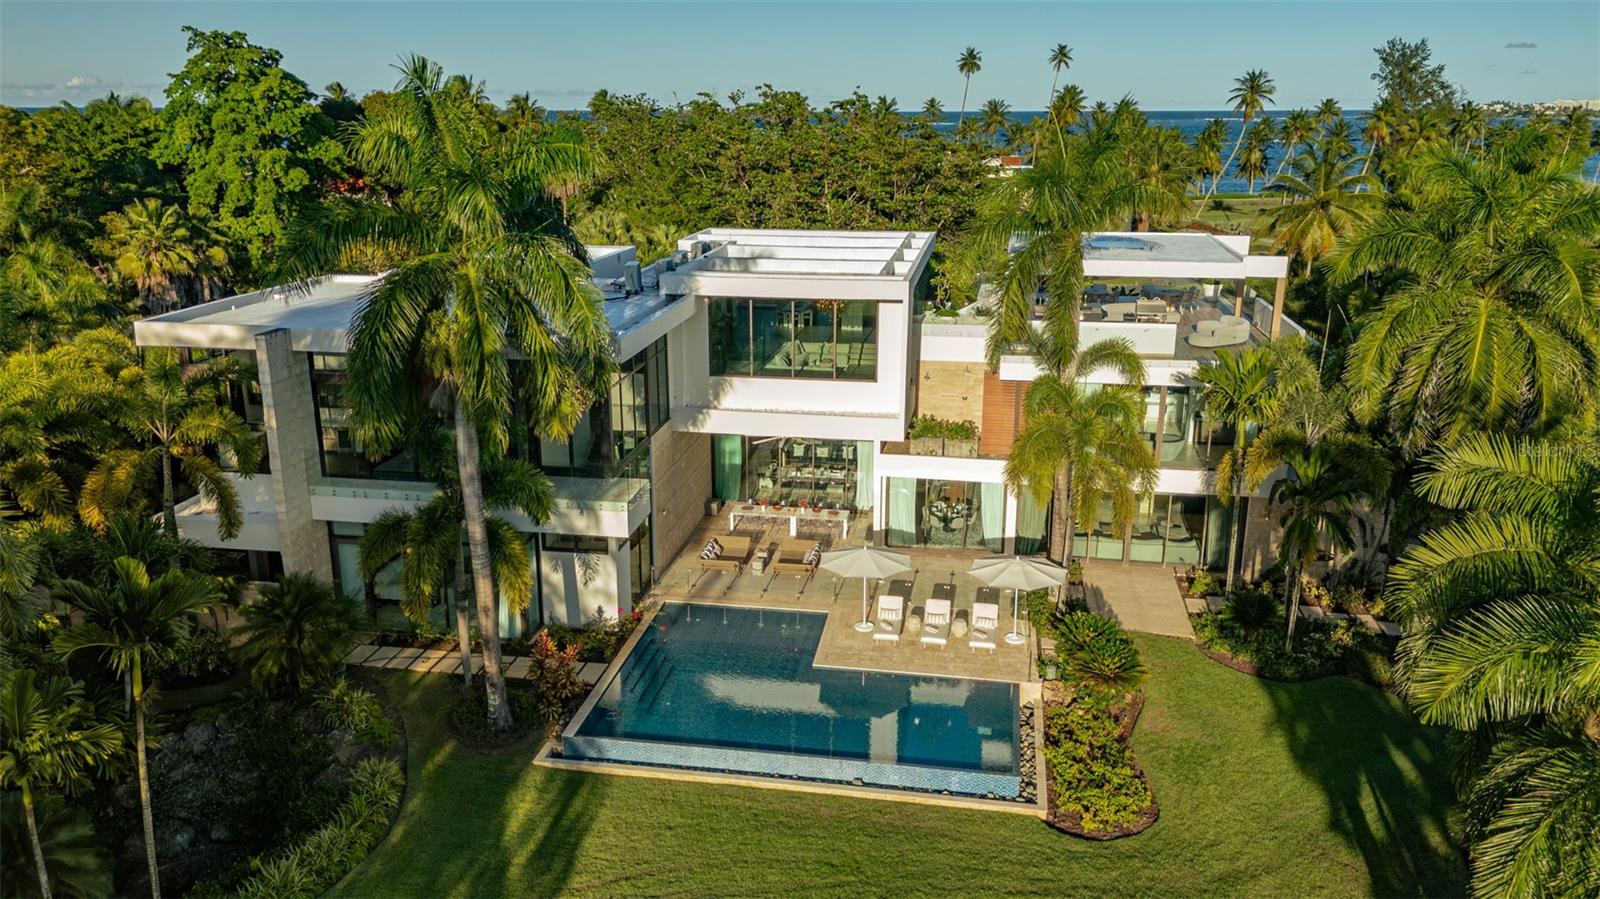
200 DORADO BEACH DRIVE #2210, DORADO PR, 00646
Estimated Closing-Cost Totals
A reliable total is pending those quotes. For notarial services, apply the statutory bracket to the first $5 million and obtain an agreed fee for the excess; do not substitute 1.5% of the entire price. List any mortgage-deed services separately. Replace every pending amount before treating the worksheet as a funding instruction.
Estimated Cash Needed at Closing
- All cash: $10,999,995 + unpaid buyer costs and net adjustments − deposits and applicable credits.
- 60% LTV example: $4,399,998 + unpaid buyer costs and net adjustments − deposits and applicable credits.
Use only costs still due at closing in these formulas. Reconcile deposits, credits, and each filing charge against the final settlement statement before arranging payment.
Conclusion
Closing costs for elite properties in Puerto Rico are best planned through an itemized budget tied to the contract, current statutory charges, and written provider quotes. Keep transaction fees, financing costs, prepaids, and the purchase-price balance distinct so your cash-to-close figure is clear.
Schedule a property consultation with Christie’s International Real Estate Puerto Rico to discuss your search and transaction timeline. Confirm the legal and financial figures with your notary, tax adviser, lender, and other providers before committing funds.
FAQs
Who typically pays closing costs in Puerto Rico—buyer or seller?
The purchase contract should specify each party’s costs and credits. Articles 1287–1288 of Puerto Rico’s Civil Code address deed-execution expenses and the selection of the notary, subject to a different agreement. Do not assume every government or notarial charge belongs to the buyer. Have the closing professional confirm the allocation before signing.
Are closing costs deductible or creditable for U.S. tax purposes?
Some items may affect your tax picture, but not as a simple “closing-cost deduction.” IRS Publication 530 distinguishes qualifying interest or points from settlement expenses that may be added to the property’s basis. Treatment depends on the item and your circumstances. Confirm both Puerto Rico and U.S. treatment with your tax adviser.
What can delay closing even if funds are ready?
Common delays include incomplete Property Registry documentation, unresolved liens or HOA balances, missing municipal permits/certifications, and bank compliance reviews. Starting due diligence early and requesting a document checklist upfront helps identify issues before the scheduled closing.
Can foreign investors purchase elite properties in Puerto Rico, and are there additional closing costs or requirements for them?
Foreign buyers should confirm the proposed ownership structure, identification, signing authority, and banking requirements with Puerto Rico counsel and the lender. The IRS issues an ITIN for a federal tax purpose when an individual is not eligible for an SSN; it is not automatically required merely because a buyer lacks a Social Security number. Request separate quotes for any international document, translation, tax-planning, or entity work.
Are there any tax benefits or exemptions for investing in luxury real estate in Puerto Rico?
A luxury-home purchase does not itself establish eligibility for Act 60 or an exemption from closing charges. Law 38-2026 amended the resident-investor provisions, including different treatment for applications submitted from January 1, 2027. Have advisers verify the relevant program, decree, dates, and income treatment; include a closing-charge exemption only when the notary confirms its legal basis.
Are closing costs lower when paying cash?
An all-cash purchase avoids loan-specific fees, mortgage documentation and lender-required services. It does not eliminate deed, title, registration, insurance or due-diligence considerations. Compare itemized totals for the same property and cost allocation rather than applying a fixed cash-versus-financed percentage.